Stock Analysis · Mineros S.A (MNSAF)
Overview
Mineros S.A. is a Latin American precious-metals producer focused mainly on gold. The company operates mining assets in Colombia and Nicaragua and also has a smaller alluvial mining business in Colombia. In simple terms, it extracts gold, processes it, and sells the metal into the market, so its results are heavily influenced by how much gold it produces, what it costs to produce it, and the international gold price.
Revenue is overwhelmingly tied to gold sales, with a small contribution from silver. Based on the company’s recent annual disclosures, the business mix is approximately:
- Nicaragua underground gold operations: about 55% to 65% of revenue. This includes the Hemco district and related processing activities.
- Colombia underground gold operations: about 25% to 35% of revenue. This is centered on the Nechí-related and other Colombian producing assets.
- Colombia alluvial mining and other: about 5% to 10% of revenue. This includes gold recovered from alluvial operations and a small amount of by-product sales.
- Silver and other minor by-products: typically below 5% of revenue.
That concentration means Mineros is not a diversified mining conglomerate. It is a relatively focused gold producer, and that can be attractive when gold prices are strong, but it also leaves the company more exposed to mine-level issues than larger global peers.
The business has recently shown a meaningful improvement in scale and profitability. Revenue rose sharply in 2025, while operating income and net income expanded even faster, suggesting that stronger prices and operating leverage have had a major effect on earnings. The cost structure also looks healthier than it did a few years ago, with operating expenses staying controlled relative to sales growth.
Over the last several years, Mineros moved from a moderate revenue base to a much larger earnings profile. The most noticeable trend is that profit growth has outpaced revenue growth, which usually points to better margins, improved mine performance, or stronger realized metal prices.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $2.19B | |
| Beta ⓘ | 1.23 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.03 | 16.90 |
| P/B Ratio ⓘ | 3.61 | 1.65 |
| FCF Yield ⓘ | 1.41% | 5.76% |
| Dividend Yield ⓘ | 1.32% | 2.13% |
| EBIT / EV ⓘ | 19.83% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 46.40% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 11.29% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 34.29% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 5.54% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 12.69% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 12.53% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 23.38% | 4.91% |
| ROIC (5Y Median) ⓘ | 23.37% | 7.70% |
| ROA (5Y Median) ⓘ | 7.79% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.04 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.36 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.03 | 0.95 |
| Net Debt / Assets ⓘ | 1.49% | 13.69% |
| EBITDA / Interest ⓘ | 52.31 | 12.34 |
| Operating Margin (Latest) ⓘ | 38.84% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 24.89% | 11.80% |
| Debt to Equity (Latest) ⓘ | 9.28% | 40.56% |
| Profit Margin (Latest) ⓘ | 19.33% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $30.99M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +2344.41% | +68.89% |
| 12M Return (excl. last month) ⓘ | +130.24% | +30.21% |
| 6M Return ⓘ | +101.44% | -4.16% |
| Price vs. 200-Day MA ⓘ | +53.43% | -1.27% |
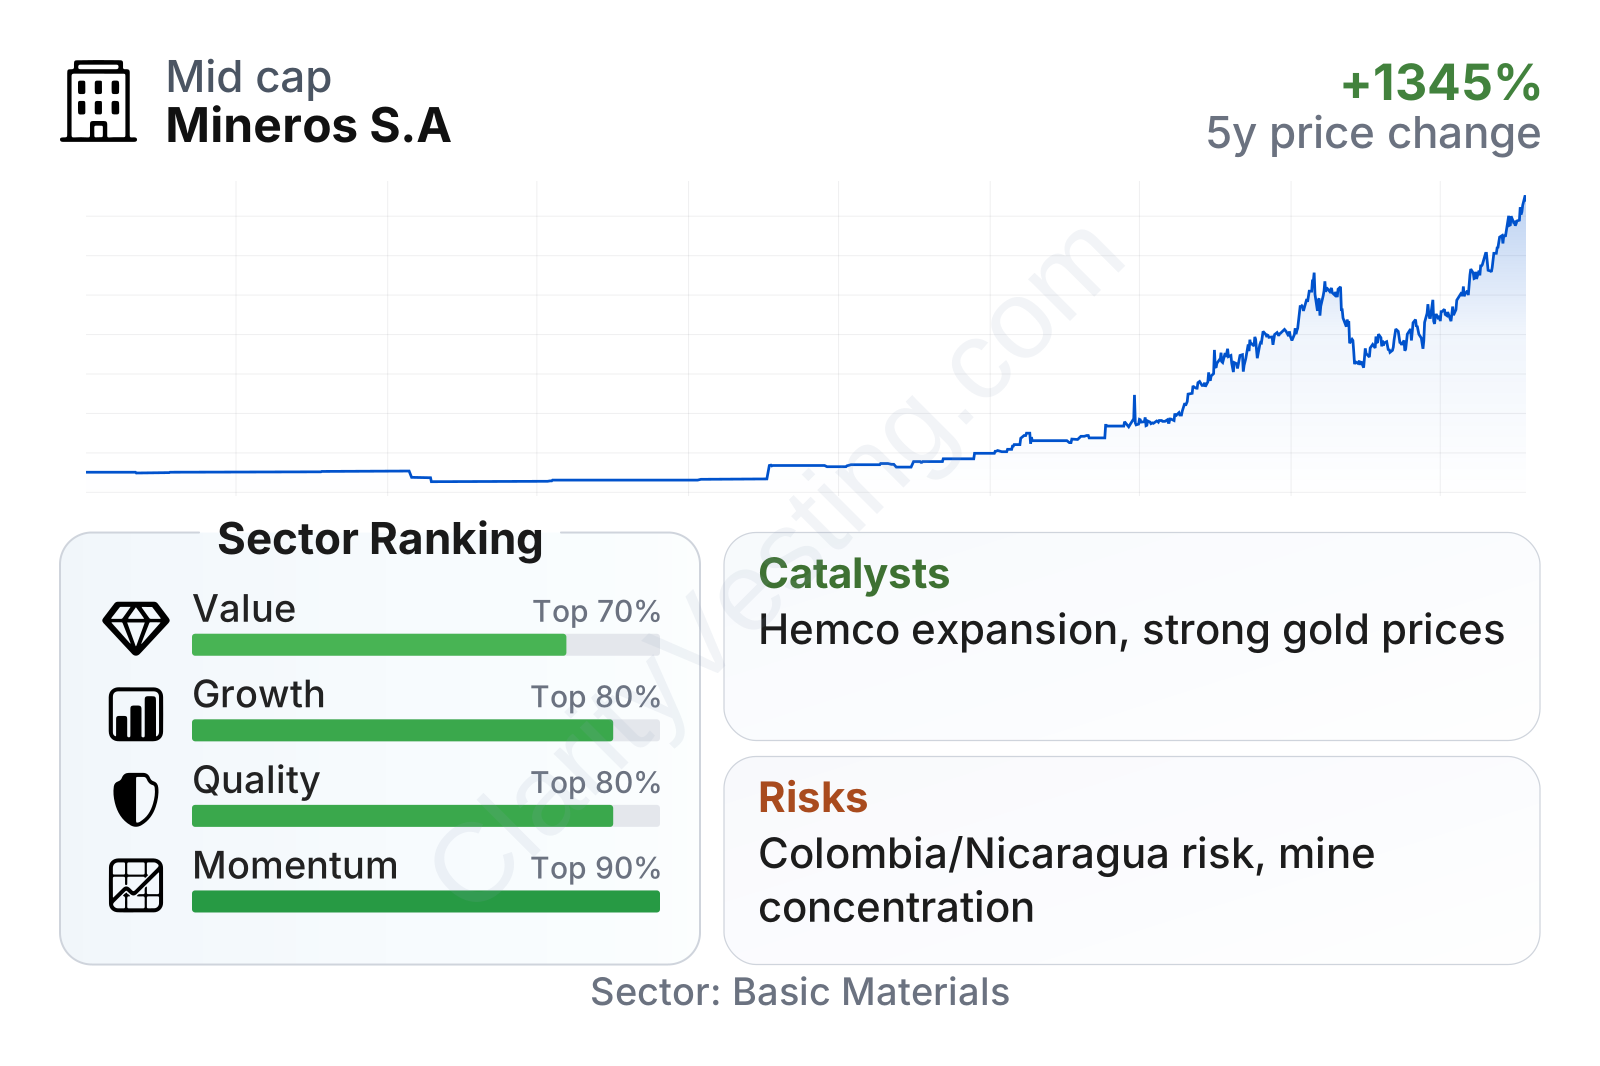
Mineros is a mid-sized gold producer with above-average growth, strong profitability, and unusually low leverage for its sector. On valuation, the picture is mixed: earnings multiples look moderate, while asset-based valuation is richer than the sector median. The quality profile stands out most clearly, with very low net debt, high interest coverage, and margins well above many gold peers. Momentum has also been exceptionally strong, which helps explain why the stock has rerated sharply since 2024.
The share price history shows a dramatic recovery after a weak 2023. That rebound likely reflects a combination of stronger operating results, higher gold prices, and a market reassessment of the company’s earnings power. The move has been substantial enough that the stock now carries more expectations than it did when it was trading at depressed levels.
Growth
Gold mining is not a classic high-growth industry in the way software or semiconductors can be, but it is part of a sector that can enjoy long favorable periods when gold prices rise, reserve replacement is successful, and new projects are brought into production on time. In 2026, the backdrop remains supportive because gold continues to benefit from central-bank buying, geopolitical uncertainty, and investor demand for hard assets. That creates a constructive setting for efficient producers.
Mineros appears better positioned than many smaller miners because its strategy is not based on a single early-stage project. It already has producing assets, operating cash generation, and a balance sheet that gives it room to invest. For a long-term reader, that matters: growth funded by existing operations is usually less fragile than growth that depends mainly on issuing shares or taking on heavy debt.
The revenue trend has clearly accelerated. After a softer period in 2023 and early 2024, year-over-year growth turned sharply positive and has recently been running far above the industry median. That suggests Mineros is not only benefiting from the gold price but is also seeing a stronger company-specific improvement than many peers.
Cash generation has also improved materially. Free cash flow was negative in earlier periods, then turned positive and climbed meaningfully before moderating again. Even with that pullback, the move from negative to positive cash generation is important because it shows the business is currently capable of funding itself more comfortably than in the past.
Another growth support is the company’s operating base in Nicaragua, where Mineros has been developing its Hemco district through underground mining, processing infrastructure, and exploration. If reserve conversion and mine development continue successfully, that asset can remain a key engine of production and margin support. In Colombia, the company’s long operating history and knowledge of local geology can also help it sustain output, although expansion there is generally more incremental.
A practical catalyst is simple but powerful: when a gold producer has rising production or improving grades at the same time as the metal price stays elevated, earnings can scale very quickly. Mineros’ recent financial performance suggests it is currently in that kind of phase. If exploration, mine planning, and throughput improvements continue, the company has a credible path to extending that momentum.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


