Stock Analysis · MannKind Corp (MNKD)
Overview
MannKind Corp is a biotechnology company focused on inhaled therapies and drug-delivery technology. Its best-known product is Afrezza, an inhaled rapid-acting insulin for adults with diabetes. The company also develops and manufactures dry-powder formulations and inhalation devices, and it increasingly uses that platform in partnerships with other companies. In simple terms, MannKind is no longer just a single-product diabetes company: it is trying to become a broader inhaled-therapeutics and manufacturing platform business.
The business now has several revenue streams, with the largest coming from collaborations and product sales tied to its technology and commercial portfolio. Based on the latest annual results and recent quarterly disclosures, the revenue mix is approximately as follows:
- Collaboration and services revenue: about 45% to 55%. This includes development work, manufacturing services, licensing-related payments, and milestone-style revenue tied to partners using MannKind’s technology or production capabilities.
- Afrezza net revenue: about 25% to 35%. This is the company’s inhaled insulin franchise in the United States, including sales through specialty and retail distribution channels.
- Tyvaso DPI-related revenue and other product supply revenue: about 15% to 25%. This reflects manufacturing and supply activity connected to MannKind’s role in dry-powder inhalation programs, most notably with United Therapeutics.
- Other revenue: a small remaining portion. This can include small amounts from royalties, device-related activity, and other partner programs.
That mix matters because it shows a business in transition. Afrezza remains important, but external partnerships and contract manufacturing have become a major part of the model, helping the company scale faster than a stand-alone diabetes launch likely could.
The financial flow over the last several years shows a meaningful step-up in revenue from 2023 through 2025, along with a move from deep operating losses to operating profitability in 2024 and a much smaller net profit in 2025. At the same time, selling, administrative, and research spending also climbed, which shows management is still investing heavily to build a larger platform.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.11B | |
| Beta ⓘ | 1.08 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | N/A | 3.08 |
| FCF Yield ⓘ | -1.67% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 0.70% | 0.57% |
| PEG ⓘ | 4.39 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 42.90% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 38.41% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -32.03% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -33.69% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 89.66% | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.22% | 3.24% |
| ROA (Latest) ⓘ | -7.11% | 3.01% |
| ROIC (5Y Median) ⓘ | -10.77% | 4.60% |
| ROA (5Y Median) ⓘ | -3.10% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | 27.95 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.22 | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 9.22 | 1.00 |
| Net Debt / Assets ⓘ | 37.95% | 5.45% |
| EBITDA / Interest ⓘ | 0.67 | 9.64 |
| Operating Margin (Latest) ⓘ | 2.53% | 9.27% |
| Operating Margin (5Y Median) ⓘ | 4.37% | 7.38% |
| Debt to Equity (Latest) ⓘ | -492.36% | 28.58% |
| Profit Margin (Latest) ⓘ | -11.08% | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$18.57M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -13.20% | +42.80% |
| 12M Return (excl. last month) ⓘ | -25.31% | +18.50% |
| 6M Return ⓘ | +31.03% | +7.57% |
| Price vs. 200-Day MA ⓘ | -13.08% | +5.12% |
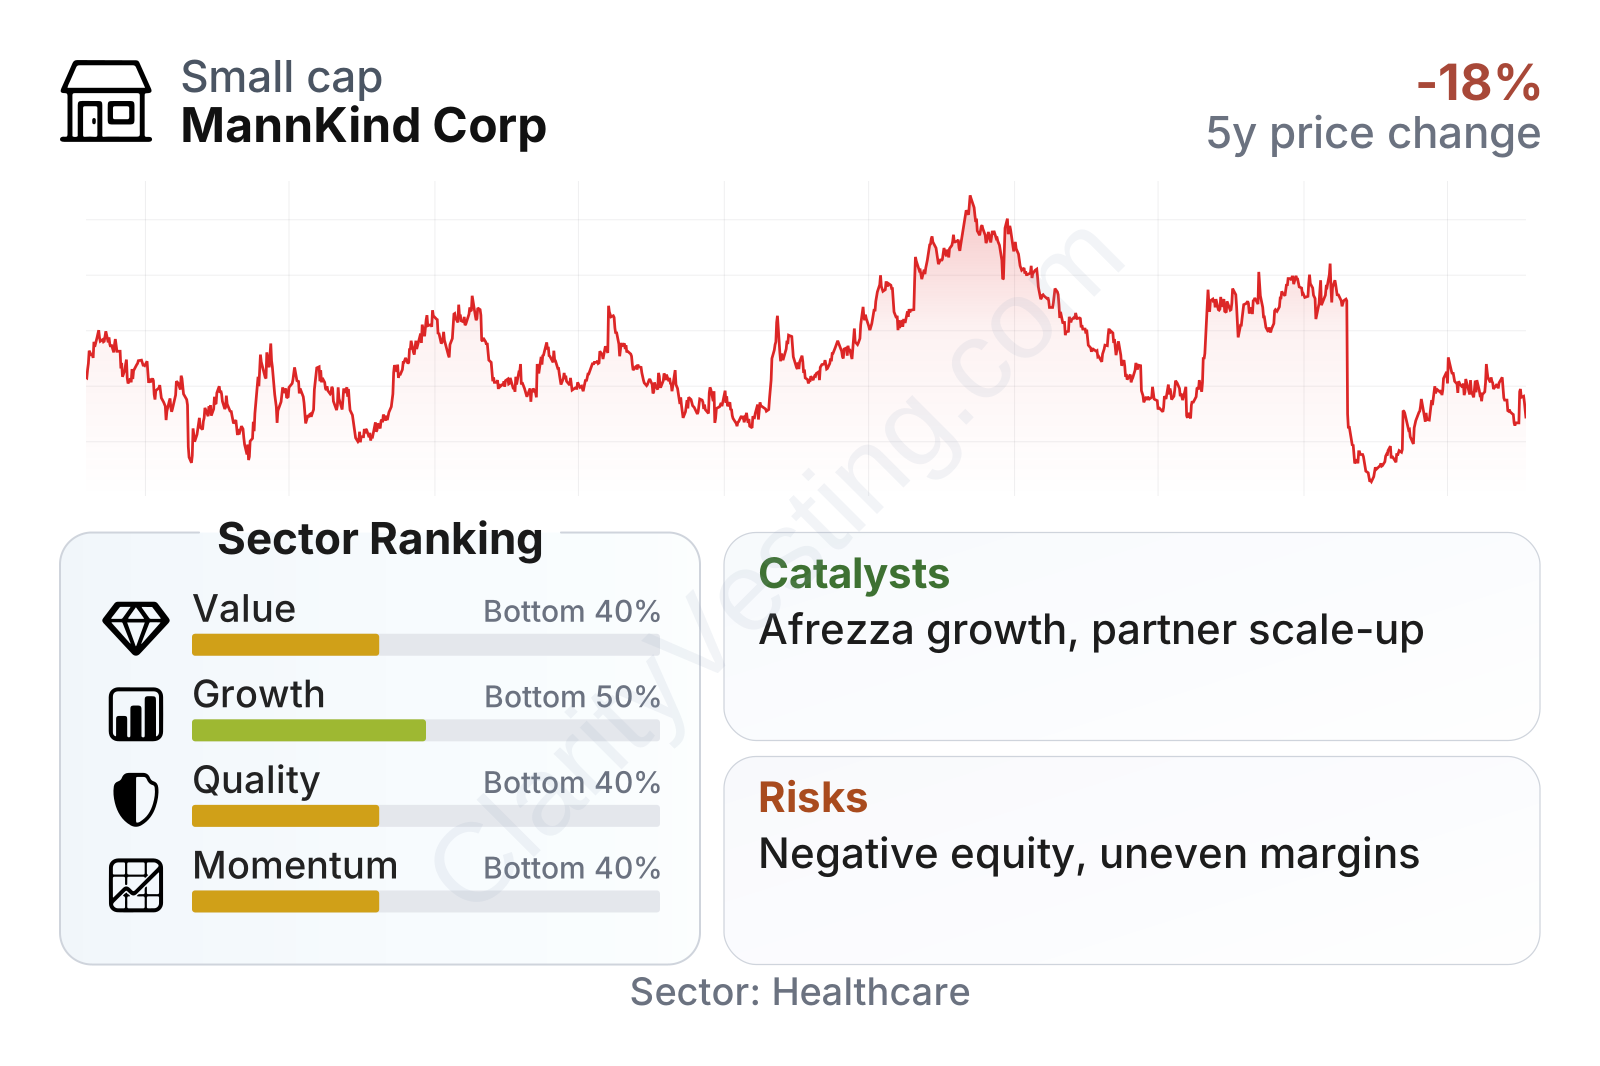
MannKind is a small-cap healthcare company with above-average share-price volatility. The overall profile is mixed: revenue growth has been much stronger than the healthcare sector median, but quality, value, and momentum rankings remain in the lower half of the sector. That combination usually points to a company with real commercial progress but still limited financial resilience. The recent pullback in profitability and free cash flow also helps explain why the market has remained cautious despite strong top-line expansion.
Growth
MannKind operates in a part of healthcare that still offers room for growth. Diabetes remains a very large global market, and inhaled delivery is attractive because it can offer convenience and faster onset for some therapies. Beyond diabetes, the company’s core opportunity is broader: proving that its dry-powder inhalation platform can be used across more products, more partners, and more disease areas. If that happens, revenue can become less dependent on any single drug.
The company’s recent strategy is logical. Instead of relying only on Afrezza prescriptions, MannKind has built a second engine around partnerships, manufacturing, and platform licensing. That approach can reduce commercialization risk because partners may fund development, absorb part of the launch burden, or create recurring supply revenue once products scale.
Revenue growth has been unusually strong for a company of this size. Recent year-over-year growth has often stayed well above the sector median, even though the quarterly pattern has been uneven. Over a five-year period, revenue per share growth has also been far ahead of the typical biotechnology peer. This suggests that the company’s platform strategy is producing real commercial traction rather than just one-time accounting noise.
Cash generation improved dramatically from deeply negative levels in 2022 and 2023 to positive territory in 2024 and 2025, although the latest trailing figure has slipped back below zero. That does not erase the progress, but it shows the business has not yet reached a consistently self-funding stage. For a long-term assessment, the key question is whether rising partner revenue and product volume can keep funding research, capacity expansion, and commercial activity without another long stretch of cash burn.
Several catalysts stand out. Afrezza still has room for growth if awareness, insurance coverage, and physician adoption improve. MannKind also continues to invest in its inhaled pipeline, including clofazimine inhalation suspension and other development programs. A particularly important external driver is the company’s role in supplying and supporting dry-powder inhalation products for partners. If those programs expand commercially or add new indications, MannKind could benefit without bearing all of the end-market risk itself.
Recent company updates also point to significant opportunity from manufacturing scale-up and broader use of its formulation and device technology. For a business this size, even a handful of successful partner milestones can have an outsized impact on revenue growth and operating leverage.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


