Stock Analysis · 3M Company (MMM)
Overview
3M Company is a diversified industrial and technology manufacturer best known for making thousands of specialized products used in factories, hospitals, offices, homes, transportation, electronics, and infrastructure. Its portfolio includes adhesives, abrasives, filtration products, industrial safety solutions, medical supplies, dental and health information products, consumer tapes and home-care items, and materials used in electronics and automotive applications. The company’s model has historically relied on applied science, manufacturing know-how, a large patent base, and a broad distribution network.
Since the healthcare business Solventum was separated in 2024, 3M has become a more focused industrial company. Based on its latest annual reporting structure, revenue is mainly generated from three business groups:
- Safety and Industrial — about 42%: personal protective equipment, industrial adhesives and tapes, abrasives, filtration, closure systems, and products used in manufacturing and maintenance.
- Transportation and Electronics — about 31%: materials and components for automotive, aerospace, semiconductors, electronics assembly, display applications, and electrical markets.
- Consumer — about 27%: home improvement, cleaning, stationery, packaging, and well-known retail products such as Scotch, Command, and related brands.
This mix gives 3M exposure to both cyclical industrial demand and steadier consumer channels. It also means the company is less dependent on a single end market than many narrower industrial peers. Over the last several years, however, reported revenue has been reshaped by divestitures, the healthcare separation, and legal-related charges, so headline comparisons need to be read carefully.
The financial flow over recent years shows a business that still converts a large share of sales into gross profit, but with earnings that were heavily disrupted by one-time items in 2023 and then normalized afterward. It also shows a smaller post-spin company with lower revenue than in 2021, but still substantial profitability and cash generation.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Conglomerates | |
| Market Cap ⓘ | $88.38B | |
| Beta ⓘ | 1.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 28.75 | 22.29 |
| P/B Ratio ⓘ | 22.13 | 1.98 |
| FCF Yield ⓘ | 3.03% | 6.26% |
| Dividend Yield ⓘ | 1.86% | 1.92% |
| EBIT / EV ⓘ | 4.83% | 4.83% |
| PEG ⓘ | 1.61 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.50% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -6.44% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -9.18% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | -23.77% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -1.74% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | -30.11% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | -21.85% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 20.48% | 10.75% |
| ROA (Latest) ⓘ | 9.15% | 5.41% |
| ROIC (5Y Median) ⓘ | 25.69% | 9.37% |
| ROA (5Y Median) ⓘ | 9.23% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 2.17 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.67 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.66 | 1.39 |
| Net Debt / Assets ⓘ | 25.71% | 19.27% |
| EBITDA / Interest ⓘ | 6.65 | 9.58 |
| Operating Margin (Latest) ⓘ | 18.57% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 20.13% | 10.30% |
| Debt to Equity (Latest) ⓘ | 363.39% | 64.82% |
| Profit Margin (Latest) ⓘ | 11.90% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $2.68B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +162.21% | +67.77% |
| 12M Return (excl. last month) ⓘ | +7.29% | +12.05% |
| 6M Return ⓘ | +18.82% | 0.00% |
| Price vs. 200-Day MA ⓘ | +9.35% | +0.67% |
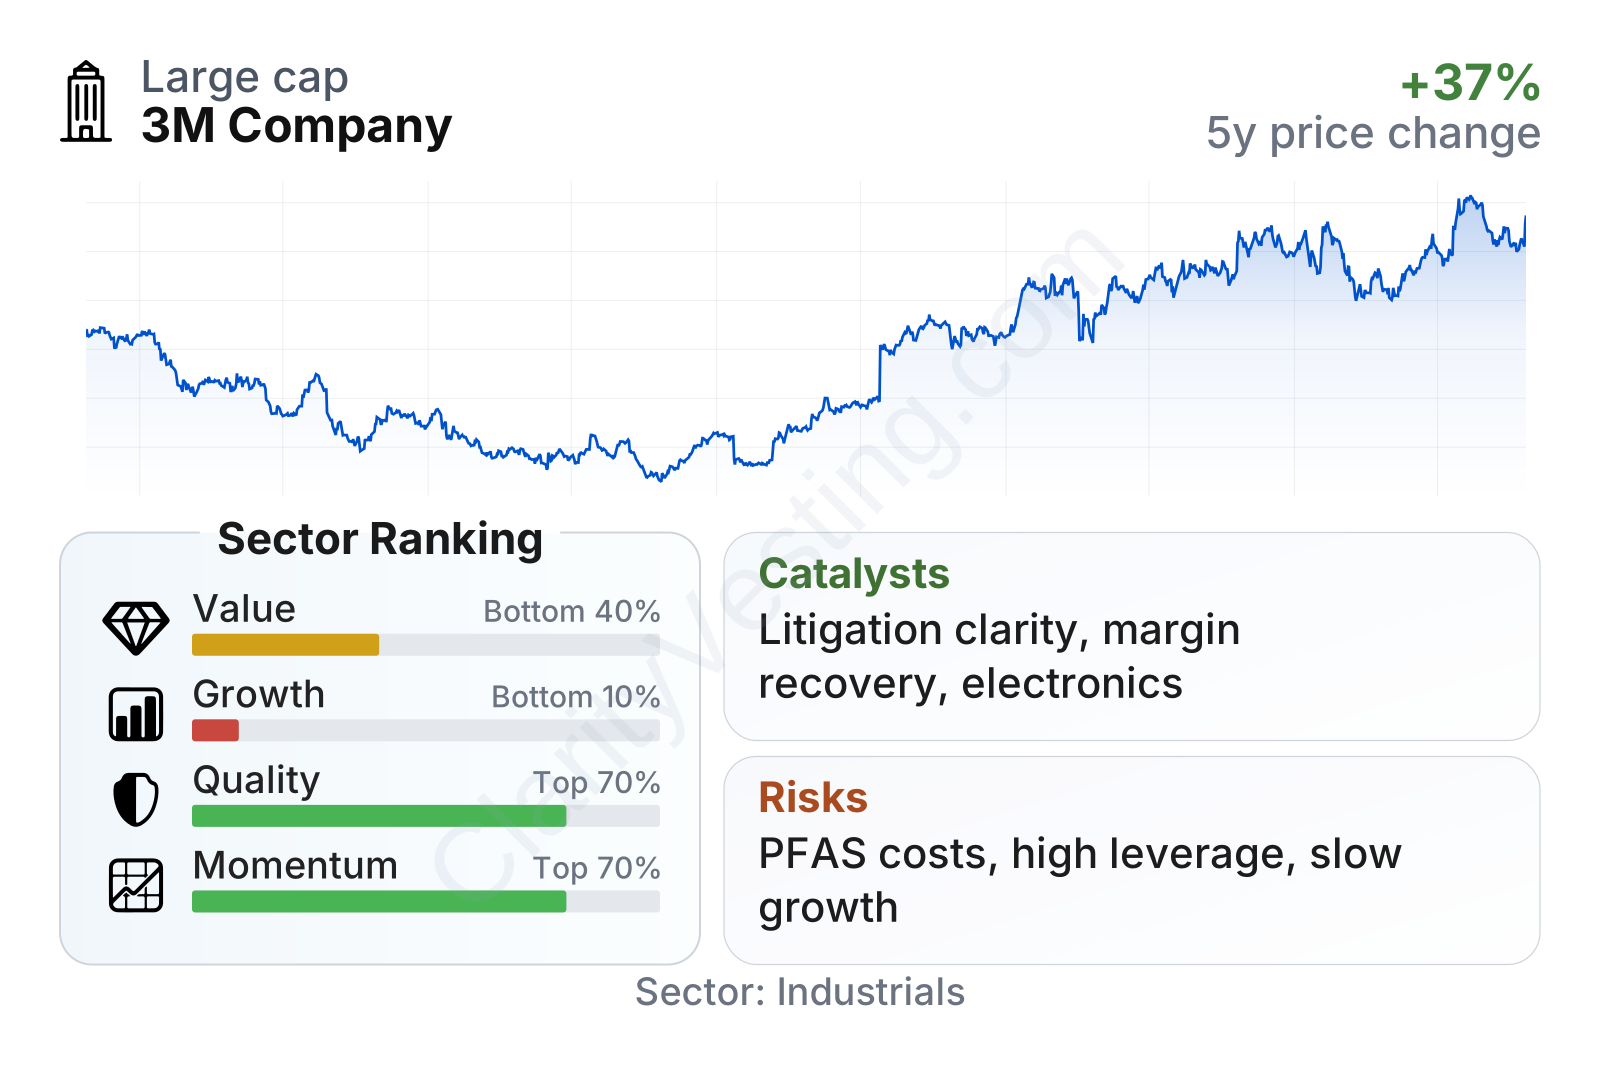
3M remains a very large industrial company, and its stock has recovered sharply from the low levels seen during the period when litigation and restructuring concerns were at their highest. In the factor breakdown, quality stands out more favorably than growth or value. Profitability metrics remain stronger than many industrial peers, but revenue growth and multi-year per-share trends are weak relative to the sector. The valuation profile also looks richer than the sector median, which suggests the market is placing more weight on stabilization and legal overhang reduction than on strong underlying growth.
Growth
3M operates in sectors that are not high-growth in the same way as software or biotechnology, but they are durable and broad: industrial automation, electrification, electronics materials, automotive content, worker safety, infrastructure repair, and branded household products. These markets tend to grow over time with manufacturing activity, product innovation, and replacement demand rather than through sudden leaps.
The company’s strategy appears centered on becoming simpler after the healthcare separation, improving execution, focusing research spending on higher-return applications, and restoring more consistent organic growth. That approach is logical for a business like 3M because its long-term strength comes less from volume expansion alone and more from pricing power, product mix, and cross-selling across many niches. Recent revenue trends show that the business has moved back into modest year-over-year growth after a long stretch of declines, although the pace remains subdued compared with the broader industrial sector.
Cash generation is another important part of the growth picture because 3M’s future flexibility depends on how much cash it can devote to debt reduction, restructuring, research, and shareholder distributions. Free cash flow has been volatile, including a sharp drop around 2025, but it has returned to positive territory. Even so, the current level is still below earlier peaks, which means the recovery is real but incomplete.
There are a few concrete catalysts that could support better business momentum. Electronics and semiconductor-related demand can help the Transportation and Electronics segment if end markets remain healthy. Industrial production normalization, especially in manufacturing and automotive channels, would also support volumes. In addition, 3M has been pursuing operational improvement programs designed to simplify the organization and improve margins. If those efforts continue to work, earnings can grow faster than revenue even without a major top-line surge.
Recent company updates have also pointed to progress in resolving major legal matters and advancing restructuring actions. For a company like 3M, that is important because a clearer legal and corporate structure can remove a major barrier to management focus and market confidence, creating room for the market to pay more attention to operating performance rather than exceptional charges.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


