Stock Analysis · MMG Limited (MMLTF)
Overview
MMG Limited is a mining company focused mainly on copper, with additional exposure to zinc, lead, gold, silver, and other by-products. The group owns and operates large mines in Latin America, Australia, and Africa, and its business model is straightforward: extract ore, process it into concentrates or metal products, and sell those materials into global industrial supply chains. Copper is the central theme because it is widely used in power grids, electric vehicles, construction, and electronics.
The company’s revenue is largely tied to a small number of major mining assets. Based on its latest annual disclosures and operating profile, the revenue mix is centered on copper and can be summarized approximately as follows:
- Copper: about 75% to 85% of revenue. This mainly comes from copper concentrate and related sales from flagship operations such as Las Bambas in Peru and Kinsevere in the Democratic Republic of the Congo.
- Zinc and lead: about 10% to 20% of revenue. This is mainly associated with the Dugald River operation in Australia, which produces zinc concentrate with lead and silver by-products.
- Gold, silver, and other by-products: generally less than 10% of revenue. These materials help support overall economics but are not the core driver of the group.
That concentration matters. MMG is not a diversified mining giant spread across many unrelated commodities. It is primarily a copper producer with some useful support from zinc and by-products. That gives the company direct leverage to copper market conditions, which can be attractive in strong copper cycles but also increases dependence on one commodity and a handful of large mines.
The broader operating picture has improved recently. Revenue and operating income recovered sharply after a weaker period, and the cost structure appears much healthier than it was in 2023. The latest results also suggest a large share of revenue is now flowing through to operating profit and cash generation more efficiently than before, helped by stronger production and pricing.
The long-term trend shown here is a business that went through a difficult earnings trough in 2022 and especially 2023, then rebounded strongly in 2024 and even more in 2025. Revenue expanded, operating profit improved faster than sales, and interest costs became less burdensome relative to earnings, which is an important shift for a capital-intensive miner.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $14.00B | |
| Beta ⓘ | 1.61 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.11 | 17.36 |
| P/B Ratio ⓘ | 6.89 | 1.73 |
| FCF Yield ⓘ | 25.40% | 5.81% |
| Dividend Yield ⓘ | N/A | 1.98% |
| EBIT / EV ⓘ | 34.02% | 6.34% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 61.20% | 11.15% |
| RPS Growth (5Y CAGR) ⓘ | 0.42% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -0.50% | -12.80% |
| BVPS Growth (5Y CAGR) ⓘ | -22.23% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -3.37% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -4.85% | 0.20% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 37.63% | 9.26% |
| ROA (Latest) ⓘ | 9.39% | 4.92% |
| ROIC (5Y Median) ⓘ | 8.19% | 7.82% |
| ROA (5Y Median) ⓘ | 1.35% | 3.88% |
| Net Debt / EBIT (Latest) ⓘ | 0.14 | 1.37 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.43 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.10 | 0.92 |
| Net Debt / Assets ⓘ | 4.12% | 13.56% |
| EBITDA / Interest ⓘ | 12.34 | 12.28 |
| Operating Margin (Latest) ⓘ | 38.97% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 23.10% | 11.82% |
| Debt to Equity (Latest) ⓘ | 67.53% | 39.91% |
| Profit Margin (Latest) ⓘ | 13.43% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $3.56B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +244.39% | +68.93% |
| 12M Return (excl. last month) ⓘ | +84.62% | +36.53% |
| 6M Return ⓘ | +9.00% | 0.00% |
| Price vs. 200-Day MA ⓘ | -3.49% | -0.18% |
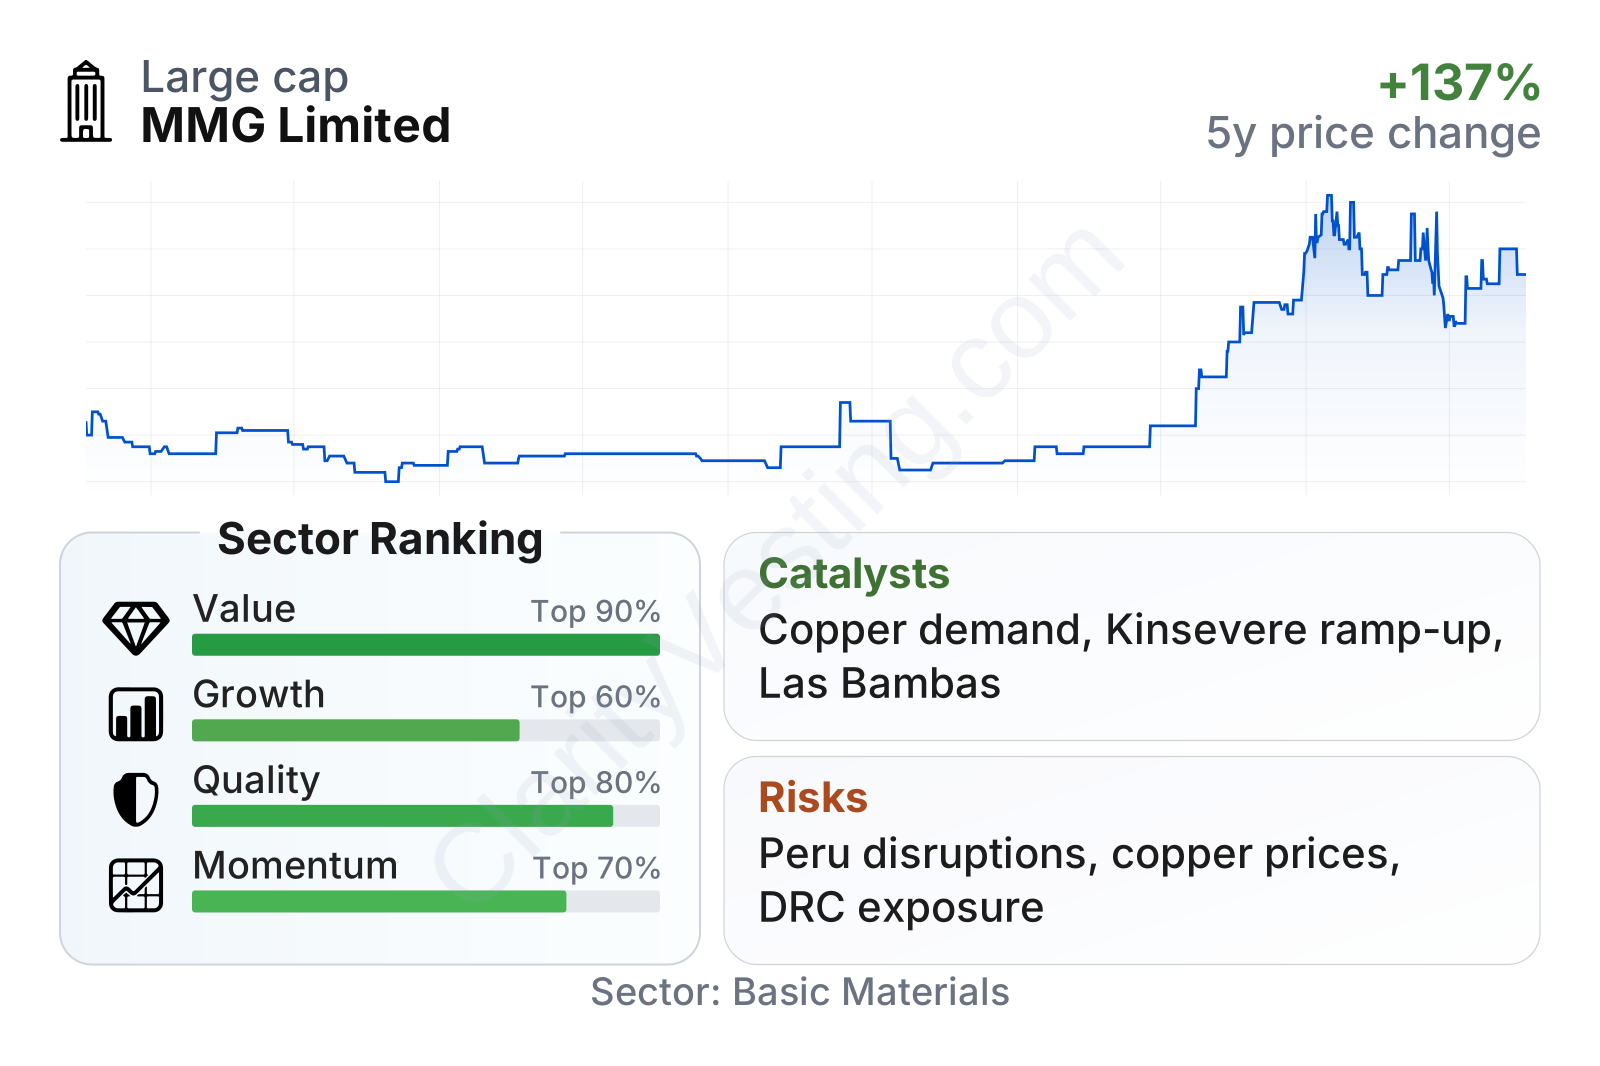
MMG is now a fairly large mining company by market value, but its share price history still shows the volatility typical of commodity producers. After a long stretch of weakness and sideways trading, the stock re-rated strongly through 2025 and into 2026. Even after that move, the metrics still point to a mixed but interesting profile: valuation looks favorable on earnings and cash flow relative to much of the sector, quality is strong on current profitability and returns on capital, while growth is more moderate when viewed across a full five-year period instead of only the latest rebound year.
What stands out most is the contrast between very strong recent profitability and cash flow versus a more uneven longer-term record. Current return on invested capital, operating margin, and free cash flow are well above sector medians, but book value growth and free cash flow growth over five years are weaker. In simple terms, MMG looks much stronger today than its multi-year averages suggest.
Growth
MMG operates in a sector with credible long-term demand support. Copper is one of the key materials behind electrification. Power networks, renewable energy, electric vehicles, charging systems, and industrial modernization all require large amounts of copper. That does not guarantee straight-line growth every year, because commodity markets move in cycles, but it does create a favorable long-term backdrop for well-positioned producers.
The company’s strategy also makes industrial sense. MMG’s growth is built around expanding output from existing core assets rather than trying to become a sprawling conglomerate. Las Bambas remains one of the world’s more significant copper mines, Kinsevere has been a major focus for expansion, and Dugald River adds zinc exposure with meaningful by-product value. This approach can be powerful when management executes well, because expanding around known assets is often less risky than building an entirely new portfolio from scratch.
The latest annual performance points to a major rebound rather than a steady linear climb. Year-over-year revenue growth is far ahead of the sector median, showing how strongly MMG benefited from improved operating conditions. However, the five-year revenue-per-share trend is much more subdued. For long-term readers, that distinction is important: the company is showing strong near-term momentum, but the main question is whether this recovery can turn into durable growth across a full commodity cycle.
One of the clearest catalysts is the company’s exposure to copper supply tightness. New large copper mines are difficult to permit, expensive to build, and often located in politically sensitive jurisdictions. That can make existing producing assets more valuable over time, especially when they are already operating at scale. MMG therefore has a natural advantage from owning established mines in a market where replacement supply is not easy to bring on quickly.
Recent company updates have also emphasized operational progress at key sites, especially around production ramp-up and project execution. For MMG, that matters more than abstract sector optimism. If output volumes continue improving while copper prices remain supportive, earnings can rise much faster than revenue because mining businesses have substantial operating leverage.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


