Stock Analysis · Mineralys Therapeutics Inc (MLYS)
Overview
Mineralys Therapeutics is a clinical-stage biotechnology company focused on hypertension, especially forms of high blood pressure that remain difficult to control with standard medicines. Its lead program is lorundrostat, an aldosterone synthase inhibitor designed to lower excess aldosterone, a hormone that can drive persistent hypertension and contribute to cardiovascular and kidney damage. The company’s strategy is concentrated rather than diversified: it is building its value around one main drug candidate and the clinical evidence needed to support future regulatory filings and commercialization.
At this stage, Mineralys does not operate like a mature pharmaceutical company. It is still developing products and has not yet established recurring commercial sales. That means the business is currently driven by research progress, trial execution, financing capacity, and the perceived future market opportunity for its lead asset rather than by present-day product revenue.
Its revenue mix is therefore very limited today.
- Product revenue: approximately 0% — no approved product sales have been reported.
- Collaboration or licensing revenue: not a meaningful recurring source based on recent filings — the company’s financial profile remains primarily that of a pre-commercial biotech.
- Interest and other income: small and non-core — any reported income outside operations does not change the overall picture that Mineralys is still in development mode.
The operating cost structure is much clearer than the revenue base. Spending is dominated by research and development, which is typical for a company running late-stage clinical trials. Over the last several years, R&D has represented the vast majority of operating expenses, while general and administrative costs have also increased as the company prepared for larger studies and potential future commercialization.
The expense flow shows a business with no commercial revenue yet and a sharp ramp in clinical investment. Research and development has become the central use of cash, far outweighing overhead, which confirms that the company’s valuation rests mainly on whether lorundrostat can successfully reach the market.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.84B | |
| Beta ⓘ | 0.69 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 3.33 | 3.08 |
| FCF Yield ⓘ | -7.56% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -20.36% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -45.22% | 3.24% |
| ROA (Latest) ⓘ | -55.15% | 3.01% |
| ROIC (5Y Median) ⓘ | -64.15% | 4.60% |
| ROA (5Y Median) ⓘ | -47.46% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | -6.09% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | N/A | 9.27% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.38% |
| Debt to Equity (Latest) ⓘ | 17.72% | 28.58% |
| Profit Margin (Latest) ⓘ | N/A | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$138.80M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +127.07% | +42.80% |
| 12M Return (excl. last month) ⓘ | -20.16% | +18.50% |
| 6M Return ⓘ | -28.86% | +7.57% |
| Price vs. 200-Day MA ⓘ | -22.02% | +5.12% |
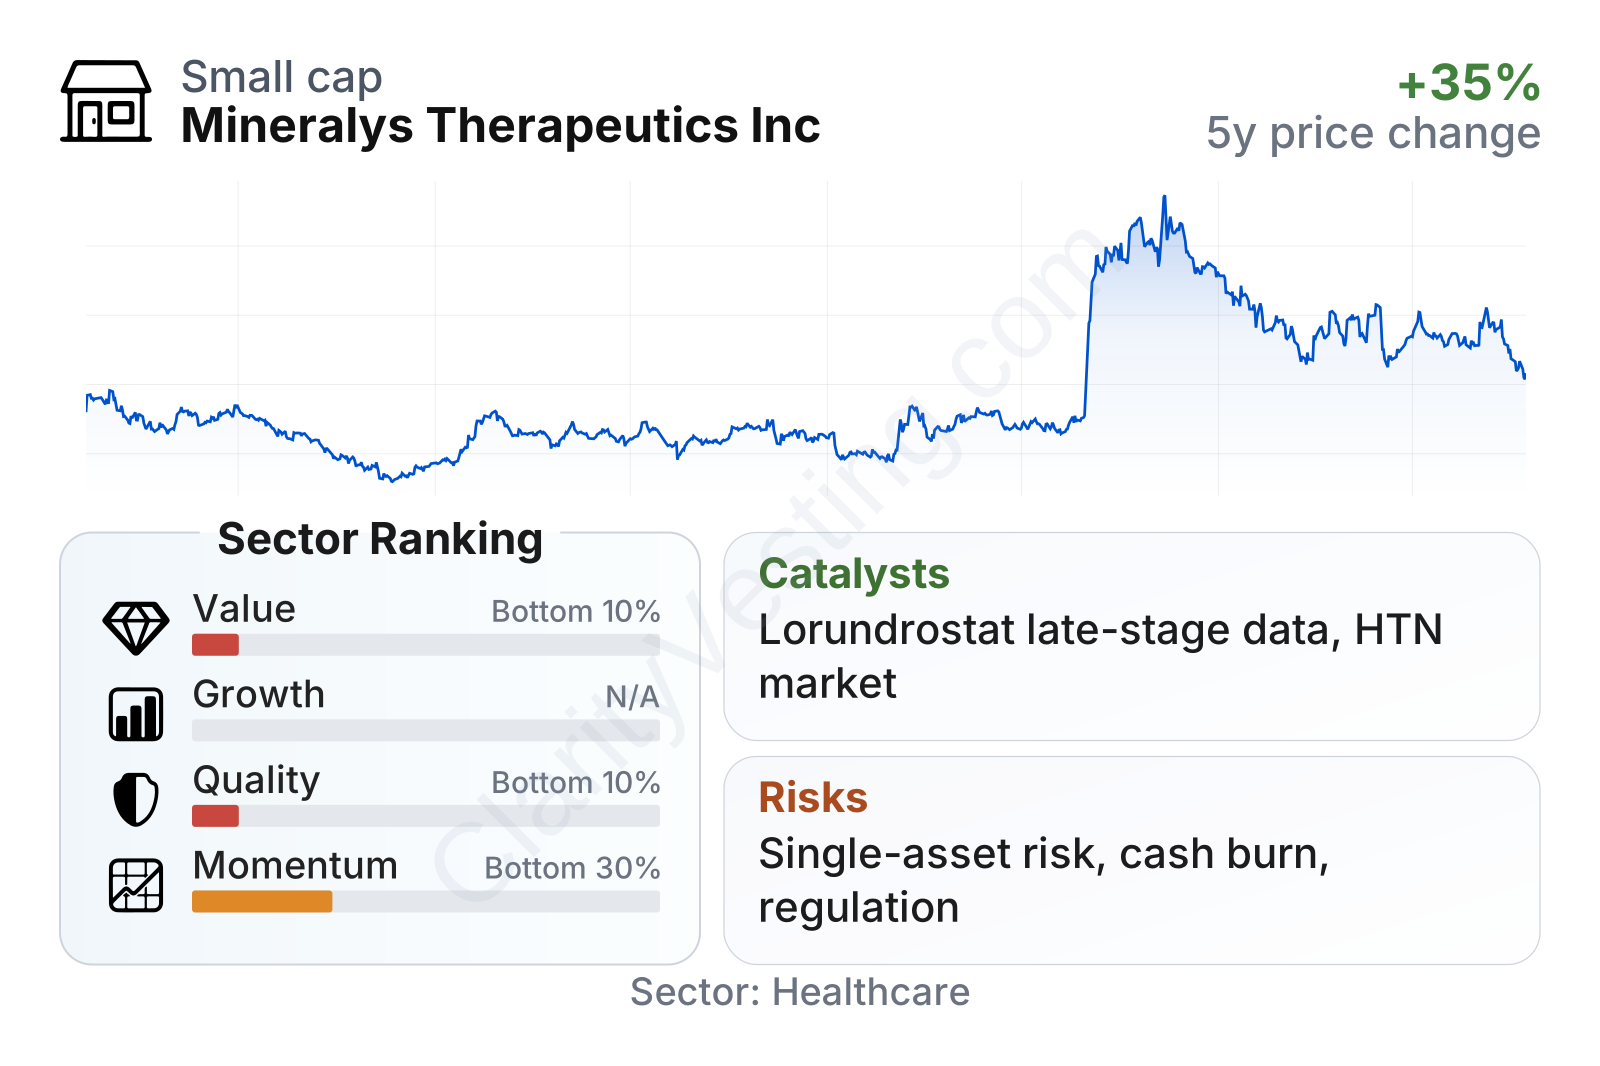
Mineralys sits in an unusual position financially: it has a mid-sized biotech market value, low share-price volatility compared with many small drug developers, and a balance sheet that appears lightly levered. At the same time, traditional valuation and profitability measures screen poorly because the company has no meaningful revenue and is still generating sizable losses and negative free cash flow. Relative to the broader healthcare sector, value and quality metrics rank near the bottom, which is common for a clinical-stage biotech but still important for long-term readers to keep in mind. Momentum has been stronger than average over the last few years, although the stock has also shown large swings tied to clinical expectations.
The share-price history reflects that pattern clearly. After trading at much lower levels earlier in its public life, the stock re-rated sharply in late 2025 and has since remained well above its initial listing area. That kind of move usually signals that the market materially changed its view of the probability and size of the company’s future opportunity, but it also means expectations are now more demanding.
Growth
Mineralys is operating in a large and growing therapeutic area. Hypertension is one of the most common chronic conditions worldwide, and a meaningful subset of patients remain uncontrolled despite multiple existing drugs. Within that broad market, resistant and uncontrolled hypertension represent the more attractive niche because they involve patients with high unmet need and create room for new mechanisms if those treatments show strong efficacy and acceptable safety. That gives Mineralys exposure to a very large patient pool, even though it is targeting a specialized biological pathway.
The company’s strategic logic is straightforward. Instead of trying to compete broadly across many disease areas, it is focusing on a specific hormonal driver of hypertension that may be particularly relevant in hard-to-treat patients. If lorundrostat can show durable blood-pressure reduction with a manageable safety profile, Mineralys could carve out a meaningful place in treatment despite entering a crowded cardiovascular market. This strategy makes sense because physicians already understand aldosterone biology, and that can lower the educational barrier compared with a completely novel treatment concept.
A major growth catalyst is the continued advancement of the lorundrostat development program. Public company materials in 2026 indicate Mineralys has remained focused on moving the asset through late-stage clinical work and positioning it for potential registration. For a company without approved products, each important trial update can significantly change perceived future revenue potential, partnership interest, and competitive standing.
There is also a broader industry tailwind. Large pharmaceutical companies continue to show interest in cardiovascular and cardiometabolic assets with differentiated mechanisms, especially when they address large populations and can fit into established prescribing channels. If Mineralys delivers compelling data, that could improve optionality around future commercialization routes, whether independent or through external partnerships.
Cash use remains heavy, but the trend has improved from the deepest outflow period. That suggests Mineralys is still consuming significant capital to fund development, while showing some moderation in the pace of cash burn. For a pre-revenue biotech, that matters because future growth depends not just on clinical success, but also on how efficiently the company can fund the path to a potential launch.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


