Stock Analysis · Mitie Group plc (MITFF)
Overview
Mitie Group plc is a UK-based facilities transformation and business services company. In simple terms, it helps organizations run buildings and essential operations. Its work includes cleaning, engineering maintenance, security, landscaping, waste services, pest control, energy and decarbonization support, and technology-enabled workplace services. The group serves a wide mix of customers, with a particularly strong presence in government, healthcare, transport, defense, retail, and corporate workplaces.
Mitie’s business model is built around long-term service contracts. That usually makes revenue more recurring than in project-based construction or consulting businesses, although margins tend to be relatively thin because many services are labor-intensive. In recent years, the company has also been adding higher-value work in areas such as security technology, fire and telecom infrastructure, and energy efficiency, which can improve contract depth and customer retention.
Based on recent annual reporting, Mitie’s revenue is mainly generated from integrated facilities management and technical services, with a smaller contribution from specialist projects and higher-margin solutions. Exact public splits can vary by reporting format and contract mix, but the business can be summarized approximately as follows:
- Facilities management and technical services: about 75% to 85% — building maintenance, engineering services, cleaning, landscaping, waste, front-of-house, and workplace operations.
- Security-related services: about 10% to 20% — manned guarding, monitoring, intelligence-led services, and security systems.
- Projects, telecom, fire, energy, and other specialist services: about 5% to 15% — infrastructure upgrades, decarbonization work, telecom engineering, and related specialist support.
This mix matters because it shows that Mitie is not a single-service operator. It is increasingly positioned as a broad outsourcing platform, which can help it cross-sell multiple services into the same customer base.
The long-term income flow shows a business that has been expanding steadily, with revenue rising from just under £4.0 billion in fiscal 2022 to above £5.6 billion in fiscal 2026. Gross profit has also grown, but net income has been less smooth, which reflects the low-margin nature of the industry and the effect of financing, tax, and integration or operating costs. The broad picture is positive on scale, but it also highlights that execution discipline matters a lot because small changes in margin can have a large effect on profit.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $3.55B | |
| Beta ⓘ | 0.89 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 34.38 | 22.45 |
| P/B Ratio ⓘ | 7.35 | 1.98 |
| FCF Yield ⓘ | 11.65% | 6.31% |
| Dividend Yield ⓘ | 1.64% | 1.96% |
| EBIT / EV ⓘ | N/A | 4.81% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.70% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 13.29% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 7.46% | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 1.42% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 2.67% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 82.05% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 43.14% | 10.92% |
| ROA (Latest) ⓘ | 8.06% | 5.41% |
| ROIC (5Y Median) ⓘ | 23.44% | 9.21% |
| ROA (5Y Median) ⓘ | 4.99% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 1.27 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.45 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 0.75 | 1.43 |
| Net Debt / Assets ⓘ | 17.47% | 19.27% |
| EBITDA / Interest ⓘ | 12.21 | 9.53 |
| Operating Margin (Latest) ⓘ | 3.27% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 3.15% | 10.27% |
| Debt to Equity (Latest) ⓘ | 107.60% | 65.48% |
| Profit Margin (Latest) ⓘ | 1.47% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $413.18M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +138.90% | +58.56% |
| 12M Return (excl. last month) ⓘ | +49.27% | +15.63% |
| 6M Return ⓘ | +12.10% | +4.19% |
| Price vs. 200-Day MA ⓘ | +59.64% | +0.93% |
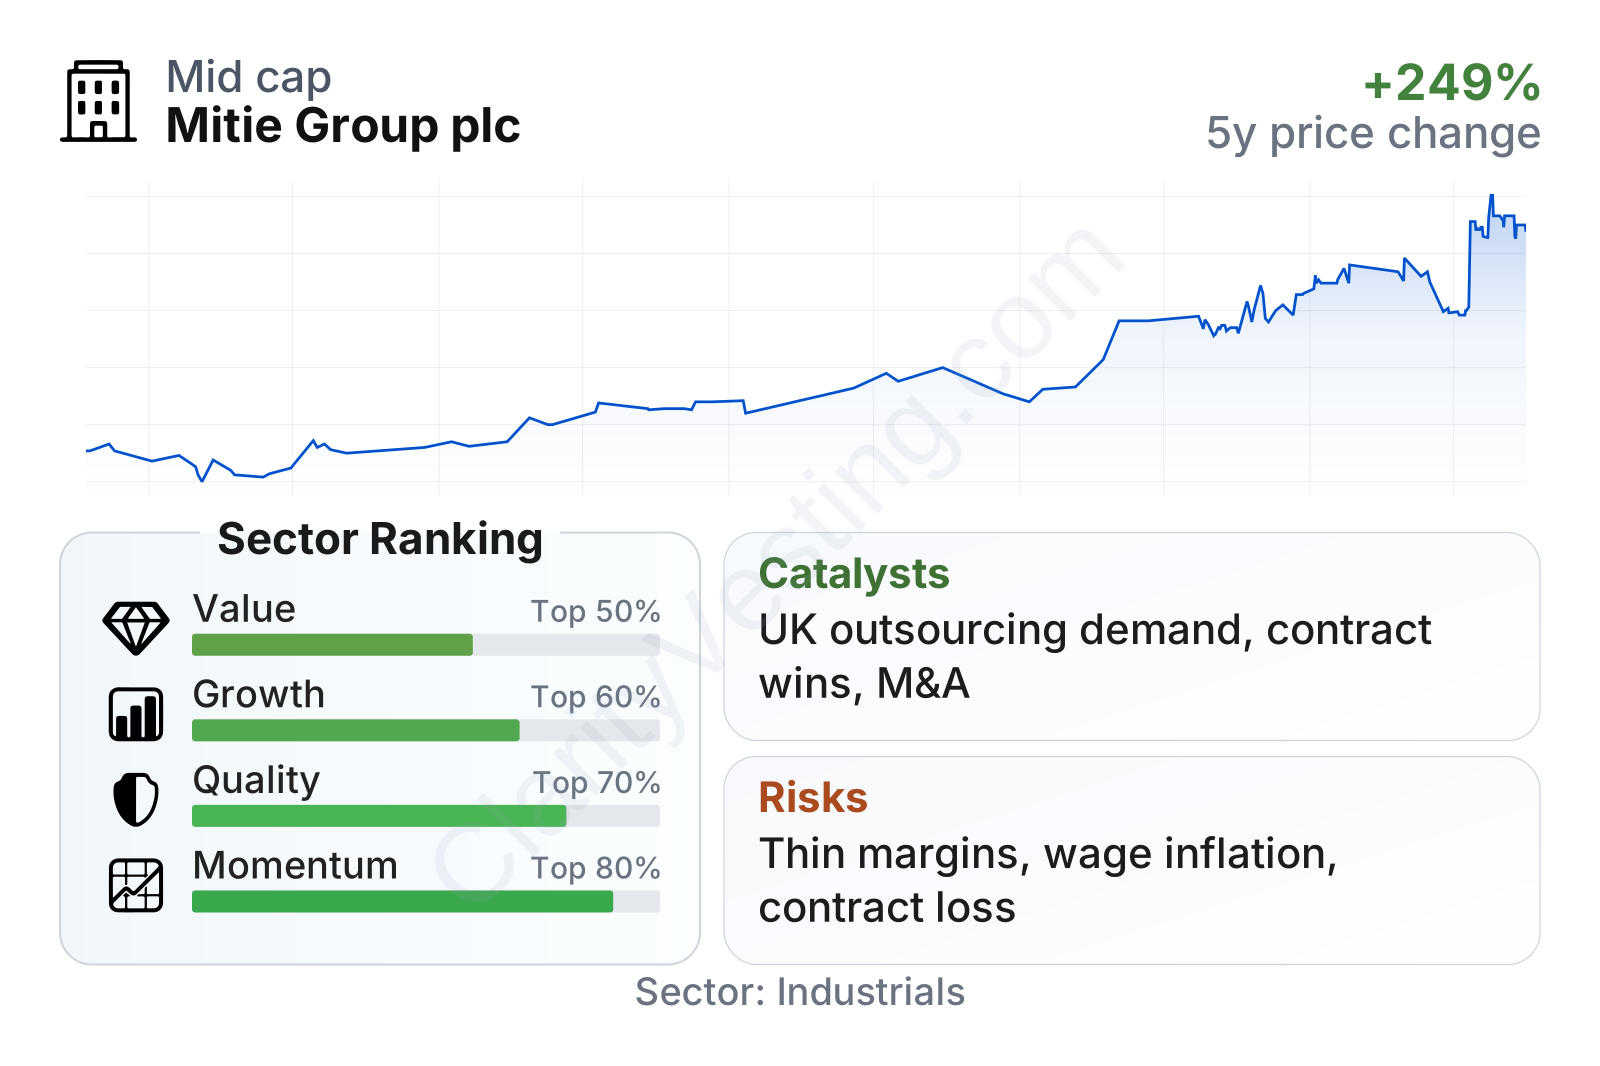
The overall profile is mixed but interesting. On growth, Mitie sits modestly above the sector median in revenue expansion, and its five-year revenue-per-share trend is notably stronger than many peers. On quality, returns on capital are strong and leverage looks manageable, with net debt ratios below sector medians and interest coverage in a comfortable range. The weaker area is profitability: operating and net margins remain low versus the broader sector, which is typical for outsourced services but still limits earnings resilience. Cash generation stands out more favorably, with free cash flow yield materially above the sector median. Momentum is also strong, as the share price has significantly outperformed many industrial service peers over one, three, and shorter trailing periods.
Mitie is a mid-sized company by market value rather than a giant global outsourcer. Its beta is below 1, which suggests the share price has not been unusually volatile versus the broader market. That said, lower share-price volatility does not remove the operational sensitivity that comes with labor costs, contract pricing, and public-sector exposure.
Growth
Mitie operates in a sector that has supportive long-term drivers. Large organizations increasingly outsource non-core functions to save money, simplify operations, and comply with stricter safety, security, and sustainability standards. Demand is also being shaped by aging buildings, energy-efficiency requirements, digital monitoring, and the need for more specialized security services. Those trends are favorable for providers that can bundle many services together, and Mitie is one of the better-known platforms in the UK market.
The company’s strategy appears logically aligned with those trends. It has been building scale in integrated facilities management while also moving toward higher-value adjacencies such as telecom infrastructure, security solutions, decarbonization, and specialist engineering. This approach can strengthen customer relationships because once a provider is embedded across several building services, switching becomes more disruptive for the client.
A major recent growth catalyst has been contract momentum and selective acquisitions. Mitie has used acquisitions not only to add revenue, but also to deepen capabilities in areas where customers increasingly want one supplier rather than several niche vendors. In the current environment, that matters because customers are often looking for cost control, compliance support, and measurable energy savings at the same time.
Another useful catalyst is public-sector and infrastructure exposure. Government bodies, transport networks, healthcare systems, and defense-related facilities often require ongoing outsourced support even in slower economic periods. That does not make the business immune to budget pressure, but it can make demand steadier than in more cyclical industrial activities.
The recent financial trend also supports the growth case at an operating level. Revenue has climbed consistently over the past several fiscal years, and operating income has improved from the levels seen earlier in the decade. While net profit has not risen as smoothly, the company has still shown an ability to grow the business and maintain cash generation through varying conditions.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


