Stock Analysis · Mesoblast Ltd (MESO)
Overview
Mesoblast Ltd is a biotechnology company focused on developing and commercializing medicines based on allogeneic, or donor-derived, cellular therapies. In simple terms, it works with specialized cells designed to reduce harmful inflammation and help repair tissue. The company’s programs are aimed at serious diseases where standard treatment options are limited, especially in inflammatory conditions and certain heart-related diseases.
Its business model is still transitioning from a development-stage biotech profile toward a commercial one. That means Mesoblast has historically relied more on licensing arrangements, milestone payments, and financing than on large recurring product sales. In the most recent fiscal year, revenue rose sharply, reflecting a mix of commercial and collaboration-related inflows rather than a broad, fully mature product base.
The main revenue sources appear to be:
- Commercial product revenue and product-related sales: the largest share in the latest fiscal year, likely around 60% to 70% of total revenue. This includes sales tied to the company’s lead marketed therapy and related supply activity.
- Royalties, license, and collaboration revenue: likely around 25% to 35%. This can include partner payments, licensing income, and other collaboration-related recognition.
- Other revenue: a smaller portion, likely under 10%, including miscellaneous items that are not part of core product sales.
One important change stands out in the company’s recent financial profile: annual revenue expanded from a very small base to more than $100 million, while gross profit turned clearly positive. That is a meaningful shift from prior years, when revenue was low and cost of revenue exceeded sales.
The revenue picture has improved significantly over the past year, but spending remains very high. Research and development and selling expenses both increased sharply, which shows Mesoblast is trying to support commercialization and pipeline progress at the same time.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.81B | |
| Beta ⓘ | 0.86 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 3.14 | 2.97 |
| FCF Yield ⓘ | -2.34% | 3.11% |
| Dividend Yield ⓘ | N/A | 2.04% |
| EBIT / EV ⓘ | -2.45% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 390.70% | 7.35% |
| RPS Growth (5Y CAGR) ⓘ | 58.04% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -52.80% | -18.43% |
| BVPS Growth (5Y CAGR) ⓘ | -11.88% | 3.94% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.61% |
| FCF Growth (5Y CAGR) ⓘ | -9.27% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.74% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.34% |
| ROA (Latest) ⓘ | -7.39% | 2.95% |
| ROIC (5Y Median) ⓘ | -8.12% | 4.60% |
| ROA (5Y Median) ⓘ | -12.99% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.02 |
| Net Debt / Assets ⓘ | 3.16% | 5.85% |
| EBITDA / Interest ⓘ | N/A | 9.60 |
| Operating Margin (Latest) ⓘ | -42.62% | 9.19% |
| Operating Margin (5Y Median) ⓘ | -792.80% | 7.53% |
| Debt to Equity (Latest) ⓘ | 22.40% | 29.44% |
| Profit Margin (Latest) ⓘ | -47.82% | 3.52% |
| Free Cash Flow (Latest) ⓘ | -$42.36M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +472.92% | +34.80% |
| 12M Return (excl. last month) ⓘ | +12.65% | +19.33% |
| 6M Return ⓘ | -1.22% | +7.18% |
| Price vs. 200-Day MA ⓘ | -13.23% | +3.20% |
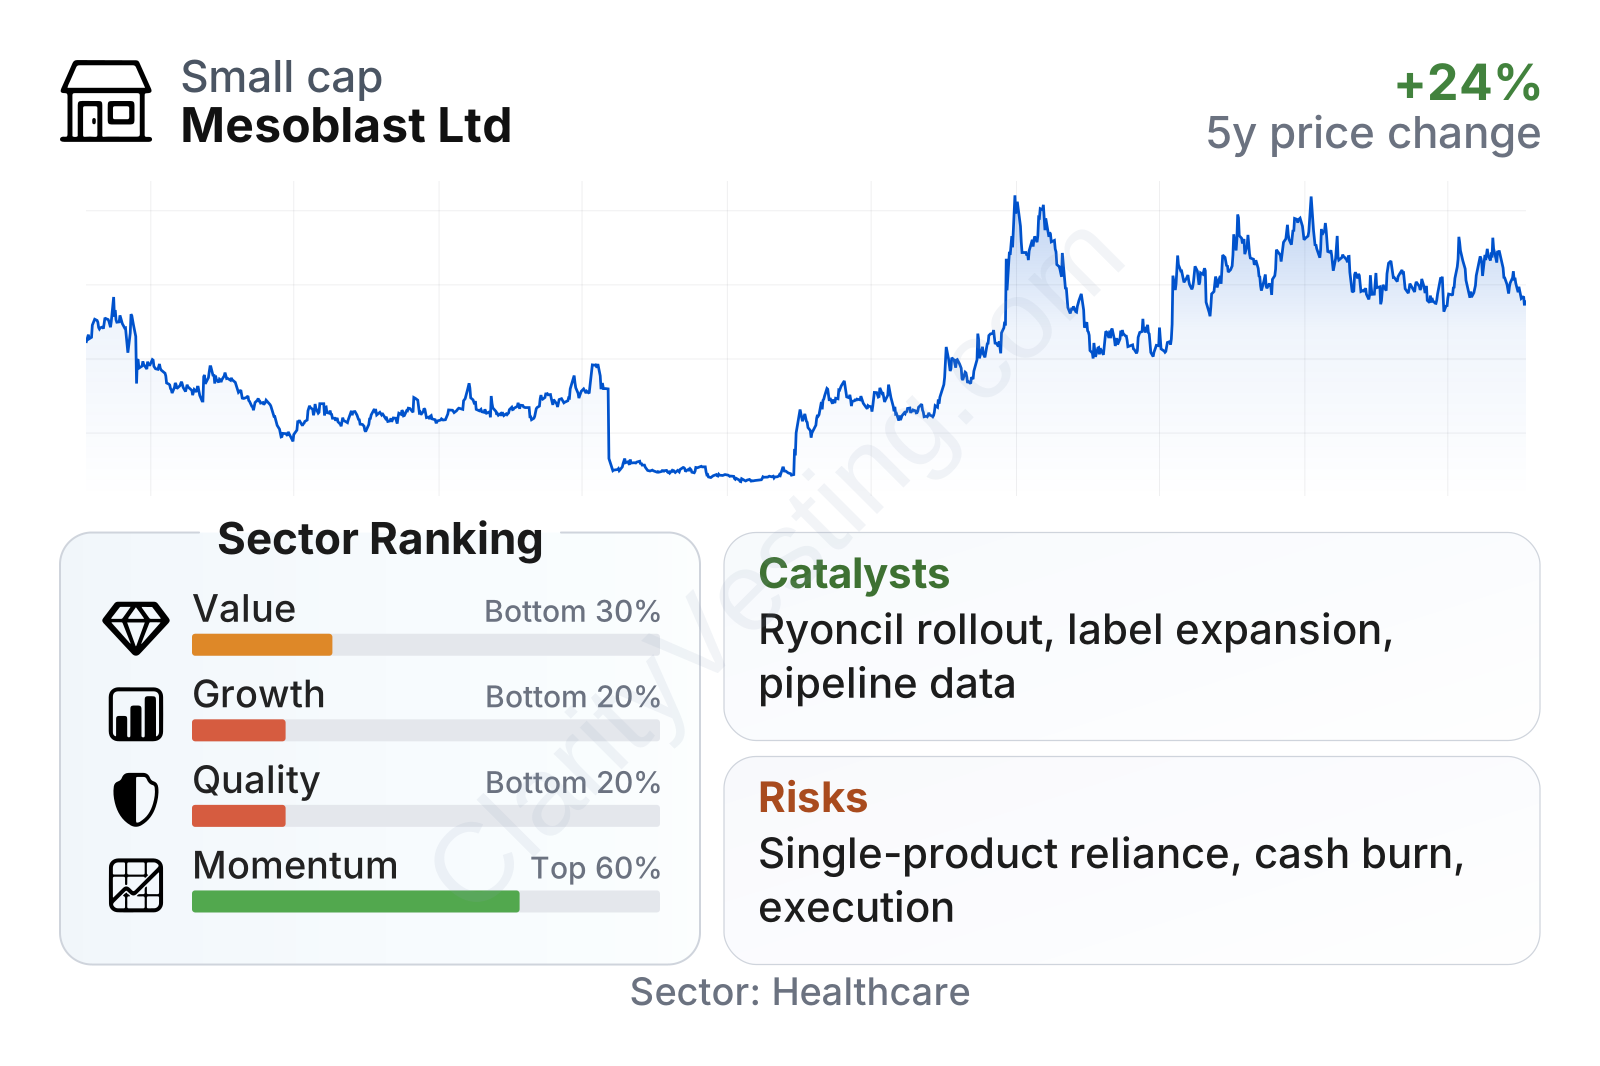
Mesoblast is now a mid-sized biotech by market value, and the stock has been highly volatile over the past few years. The factor summary is mixed: momentum has been better than much of the healthcare sector over the longer period, but value, quality, and growth rankings remain weak relative to peers. That combination is typical of a company whose share price is reacting to regulatory and commercial milestones faster than its fundamentals are fully stabilizing.
The balance sheet is not heavily leveraged by biotech standards, with debt-to-equity below the sector median, but profitability and cash generation remain negative. The market is therefore assigning value mainly to future product expansion and pipeline outcomes rather than current earnings power.
Growth
Mesoblast operates in a sector with long-term growth potential. Cell therapy and regenerative medicine remain important areas in biotechnology because they target diseases that are often difficult to treat with conventional drugs. If a company in this field secures regulatory approvals and reimbursement, revenue can scale quickly from a small starting point. That is the opportunity Mesoblast is trying to capture.
The company’s strategy is centered on advancing a limited number of high-value cellular therapy programs rather than spreading resources across many early-stage assets. Its lead commercial focus has been Ryoncil, while other key programs include candidates in inflammatory and cardiovascular settings. This narrower approach can make sense for a company of its size because it concentrates capital and management attention on the assets with the clearest near- to medium-term payoff.
Recent revenue growth has been extraordinary, but the context matters. Growth rates above 300% and even much higher reflect both a low starting base and a step-change in commercialization. This is encouraging because it shows the company has moved beyond the period of very limited revenue generation, but it does not yet prove that sales have reached a stable recurring pattern.
Cash flow shows the other side of the picture. Free cash flow has stayed negative, although losses had improved for several years before worsening again recently. That suggests Mesoblast is still in the phase where expansion requires meaningful cash outlays ahead of fully established operating returns.
A major catalyst is the continued commercial rollout of Ryoncil following U.S. regulatory progress, alongside efforts to broaden physician adoption and payer coverage. Another catalyst is the company’s pipeline, especially if late-stage data, label expansion, or additional approvals strengthen confidence in its platform. In biotech, one successful regulatory or commercial milestone can materially change the earnings outlook, and Mesoblast is still at a stage where such milestones matter a great deal.
Recent company communications have also emphasized manufacturing readiness, launch execution, and broader access efforts. For a cell therapy company, these are not routine details: they are central to whether scientific progress can become durable revenue.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


