Stock Analysis · Meitu Inc (MEIUF)
Overview
Meitu Inc is a Chinese internet company best known for photo and video editing apps. Its products started with consumer image beautification tools, but the business has gradually shifted toward paid digital content creation services powered by artificial intelligence. In simple terms, Meitu helps users edit images, create visual content, and use AI features for beauty, design, and productivity.
The company’s revenue base has changed significantly in recent years. According to its latest annual reporting and company disclosures, the largest contributor is now paid subscriptions and related imaging services, while advertising and older internet traffic monetization have become less important. A smaller part comes from products and solutions aimed at business users.
Main sources of revenue, from largest to smallest, are approximately:
- Paid subscriptions and in-app consumer services: about 60% to 70% of revenue. This includes VIP memberships, premium editing tools, AI image and video functions, and other digital content creation features across Meitu’s apps.
- Advertising: about 15% to 25% of revenue. This includes ad placements and traffic monetization inside Meitu’s apps and platforms.
- Imaging and design solutions for business users: about 10% to 20% of revenue. This includes software-as-a-service and workflow tools for commercial photography, e-commerce visual production, and related enterprise solutions.
- Other activities: a small residual share, depending on the reporting period.
That mix matters because subscription revenue is usually more predictable than advertising. It also tends to carry better margins when a company already has a large installed user base. Meitu’s financial progression over the last several years suggests that this transition has been central to its turnaround: revenue has expanded steadily, gross profit has risen faster than costs, and operating income moved from losses in 2021 and 2022 to solid profitability afterward.
The long-term pattern is encouraging: revenue has more than doubled since 2021, gross profit has increased even faster, and operating income has swung from negative territory to a meaningful profit. Research and development spending has also stayed high, which shows Meitu is still funding product improvement rather than simply harvesting its existing app base.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 31, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Internet Content & Information | |
| Market Cap ⓘ | $2.42B | |
| Beta ⓘ | 1.39 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.88 | 18.47 |
| FCF Yield ⓘ | 96.62% | 14.23% |
| Dividend Yield ⓘ | 19.02% | 2.78% |
| EBIT / EV ⓘ | N/A | 4.73% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 22.10% | 6.10% |
| RPS Growth (5Y CAGR) ⓘ | 20.81% | 4.57% |
| EPS Growth (5Y CAGR) ⓘ | -26.68% | -17.96% |
| Margin Growth (5Y Trend) ⓘ | 28.83% | 1.32% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 5.75% |
| DPS Growth (5Y CAGR) ⓘ | 39.84% | 5.19% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 14.78% | 9.19% |
| ROIC (5Y Median) ⓘ | 6.17% | 8.24% |
| Net Debt / EBIT (Latest) ⓘ | -2.47 | 1.92 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.98 | 2.88 |
| Net Debt / EBITDA (Latest) ⓘ | 0.13 | 1.22 |
| Net Debt / Assets ⓘ | 1.70% | 18.63% |
| EBITDA / Interest ⓘ | N/A | 8.36 |
| Operating Margin (Latest) ⓘ | 11.64% | 15.68% |
| Operating Margin (5Y Median) ⓘ | 10.81% | 13.39% |
| Debt to Equity (Latest) ⓘ | 26.00% | 59.65% |
| Profit Margin (Latest) ⓘ | 18.91% | 8.74% |
| Free Cash Flow (Latest) ⓘ | $2.34B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +196.03% | +46.16% |
| 12M Return (excl. last month) ⓘ | -11.56% | +1.26% |
| 6M Return ⓘ | -23.49% | 0.00% |
| Price vs. 200-Day MA ⓘ | -19.45% | +0.87% |
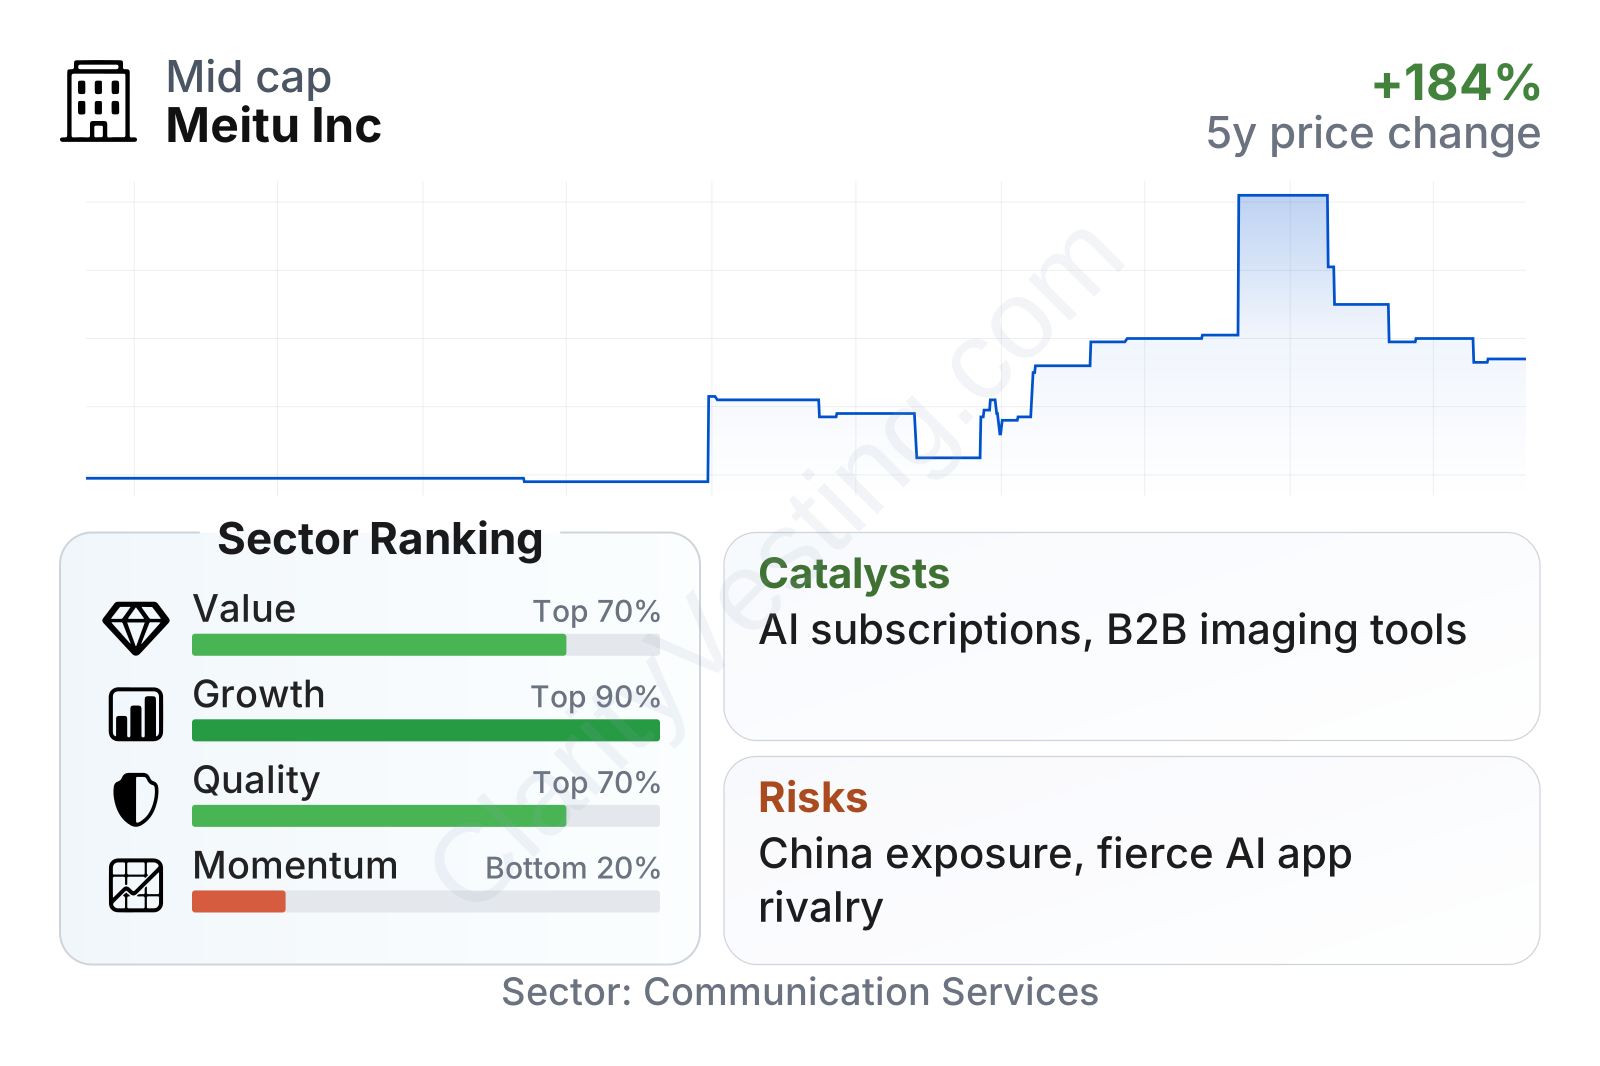
Meitu currently looks like a mid-sized company with a valuation multiple close to the sector median on earnings, but with much faster top-line growth than many peers. Revenue growth of a little above 20% year over year and a five-year revenue-per-share growth rate around the same level stand out clearly. Profitability is mixed in relative terms: operating margin is below the sector median, but net margin is stronger, and return on invested capital is above median. The balance sheet is also a positive point, with very low leverage and net cash characteristics rather than heavy debt. The weaker area is market momentum: after a very strong three-year share price run, the stock has pulled back notably over the last six to twelve months and now trades well below its 200-day average.
Growth
Meitu operates in a sector with durable structural tailwinds. Image creation, short-form video, digital self-expression, online marketing visuals, and AI-assisted content production are all growing categories. The broader theme is straightforward: more people and businesses need visual content, and they increasingly want software that makes production faster, easier, and more personalized.
Meitu’s strategy fits that trend well. Instead of relying mainly on ad-supported traffic, it has pushed users toward recurring paid features. That shift makes business sense because AI-enhanced editing tools can be monetized directly through subscriptions, credits, or premium packages. A recurring-revenue model can also be more resilient than advertising during weaker ad cycles.
Another important growth angle is the company’s move from consumer entertainment into more practical use cases. Meitu is not only helping people retouch selfies; it is also building tools that can support creators, e-commerce merchants, and professional image workflows. If that expansion continues, it could broaden the addressable market beyond casual users.
Recent company communications have continued to highlight AI-driven product upgrades, including text-to-image, image enhancement, portrait generation, and workflow tools tied to commercial visual production. Those developments matter because AI features often support both higher pricing and higher user engagement. If Meitu can keep converting free users into paid users while adding business-oriented solutions, growth could remain supported by both volume and pricing.
The company’s recent financial trajectory reinforces that view. Revenue rose from roughly RMB 1.7 billion in 2021 to around RMB 3.8 billion in 2025, while operating income improved from a loss to more than RMB 900 million over the same period. That combination suggests Meitu is not pursuing growth at any cost; it has shown it can scale while improving operating economics.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


