Stock Analysis · Madrigal Pharmaceuticals Inc (MDGL)
Overview
Madrigal Pharmaceuticals is a biotechnology company focused on liver disease. Its main commercial product is Rezdiffra (resmetirom), a treatment for adults with non-cirrhotic metabolic dysfunction-associated steatohepatitis, or MASH, with moderate to advanced liver fibrosis. This matters because MASH is a large and growing disease area with limited approved treatment options, and Madrigal moved from being a development-stage biotech into a commercial-stage company after U.S. approval of Rezdiffra in 2024.
The business is still highly concentrated. Based on recent company filings, revenue is overwhelmingly tied to one product and one market, which makes the company easy to understand but also less diversified than larger pharmaceutical groups.
- Net product sales of Rezdiffra in the United States: approximately 100% of current revenue. This includes sales to specialty distributors and pharmacies serving eligible MASH patients.
- Other revenue sources: minimal or not yet meaningful. Madrigal does not currently have a broad portfolio of marketed medicines, so there is little offset if Rezdiffra adoption slows.
The financial flow also shows a clear transition: revenue expanded sharply after launch, gross profit is strong because manufacturing costs are modest relative to sales, and spending remains very heavy in commercialization and ongoing research. Selling and administrative costs have risen substantially as the company builds market access, physician education, and patient support infrastructure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $11.64B | |
| Beta ⓘ | -0.99 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.06 |
| P/B Ratio ⓘ | 27.81 | 3.08 |
| FCF Yield ⓘ | -1.77% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | -2.58% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 71.20% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -35.30% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 22.68% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -25.05% | 3.29% |
| ROA (Latest) ⓘ | -24.94% | 3.02% |
| ROIC (5Y Median) ⓘ | -73.36% | 4.75% |
| ROA (5Y Median) ⓘ | -74.49% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.99 |
| Net Debt / Assets ⓘ | 4.42% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | -22.87% | 9.25% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.80% |
| Debt to Equity (Latest) ⓘ | 66.40% | 28.99% |
| Profit Margin (Latest) ⓘ | -25.32% | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$206.28M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +248.57% | +37.48% |
| 12M Return (excl. last month) ⓘ | +23.04% | +20.85% |
| 6M Return ⓘ | -5.69% | +9.73% |
| Price vs. 200-Day MA ⓘ | -2.19% | +4.69% |
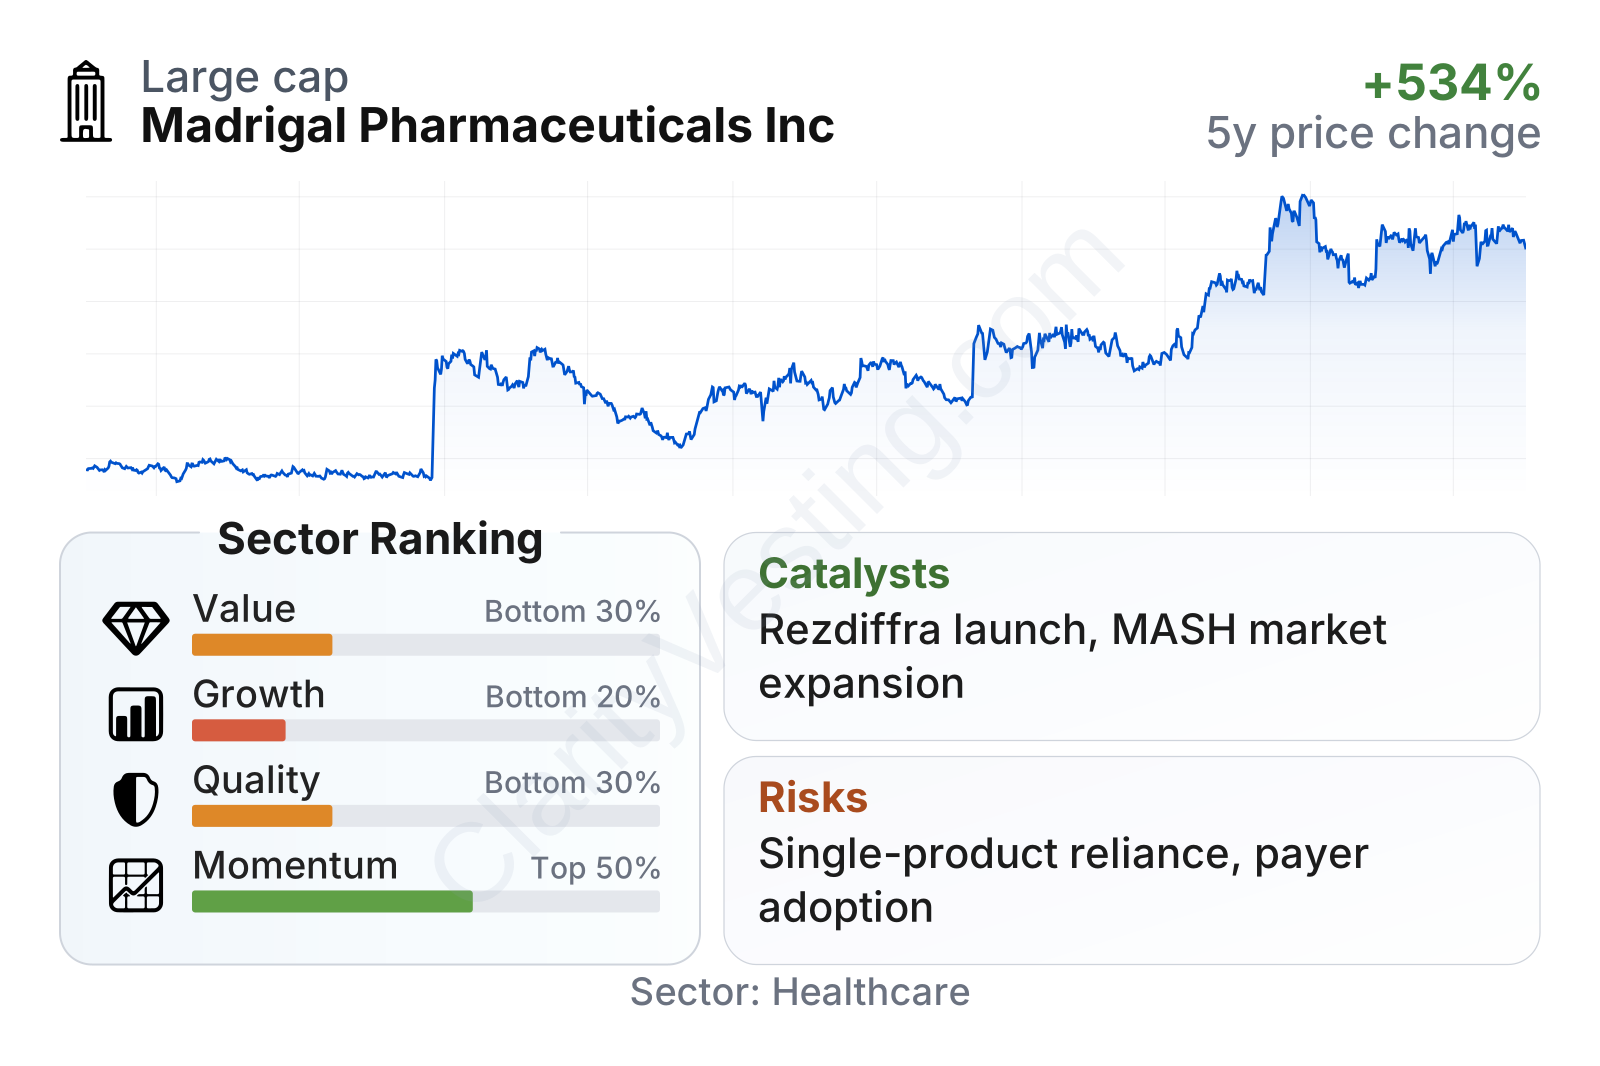
Madrigal now has the profile of a newly commercial biotech rather than a pre-revenue developer. The company is already generating meaningful sales, but profitability and cash generation remain negative as it invests heavily behind launch execution. Relative to the healthcare sector, the table points to a weak value and quality profile, which is common for companies in this stage, while share-price performance over the last three years has been much stronger than the sector median. The combination of rapid sales expansion and still-negative margins explains why traditional valuation measures look stretched.
Growth
Madrigal operates in an attractive long-term area. MASH is linked to obesity, diabetes, and metabolic disease, all of which are increasing globally. That gives the company exposure to a large patient population that has historically had very few approved treatment options. In simple terms, the sector backdrop is favorable because diagnosis rates, physician awareness, and treatment demand are all likely to improve over time.
The company’s strategy is straightforward and largely coherent: establish Rezdiffra as the first major approved therapy in MASH, expand physician adoption, improve payer access, and potentially broaden use through additional evidence and international expansion. For a small product portfolio, first-mover status can be very valuable because doctors, insurers, and treatment pathways often form early around the first approved option in a new category.
Recent revenue growth has remained very high on a year-over-year basis, although the pace is naturally moderating from the earliest launch quarters. That is normal after an initial commercial ramp. Even with that slowdown, growth remains far above the healthcare sector median, showing that the product launch is still in a strong expansion phase rather than a mature one.
Cash flow is still negative, but the trend has improved from the deepest outflows seen during the heavy launch buildout. This suggests that sales are beginning to absorb part of the commercial cost structure, though the company has not yet reached self-funding status. For long-term analysis, the key question is not whether cash flow is positive today, but whether Rezdiffra can scale enough to cover operating expenses over the next several years.
Recent company updates have reinforced the main growth case. Management has continued to emphasize expanding prescriber reach, improving reimbursement coverage, and generating more clinical and real-world evidence around Rezdiffra. Additional data in broader patient groups, progress toward approvals outside the United States, and any signs of faster diagnosis of MASH could all materially enlarge the addressable market. These are important catalysts because the biggest current limitation is not necessarily the size of the disease population, but how quickly eligible patients are identified and moved into treatment.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


