Stock Analysis · Medibank Private Limited (MDBPF)
Overview
Medibank Private Limited is one of Australia’s largest health insurers. Its core business is private health insurance, where members pay regular premiums and the company helps cover hospital and medical costs that are not fully paid by the public system. Beyond insurance, Medibank also operates health services and care-related activities, including telehealth, mental health support, prevention programs, and services delivered through its broader health platform.
The business is mainly driven by recurring premium income, which gives it a steadier revenue base than many other financial companies. Based on recent annual reporting, revenue is concentrated in a small number of activities:
- Private health insurance premiums: approximately 85% to 90% of group revenue. This is the main engine of the company and includes hospital and extras cover sold under Medibank and ahm.
- Health services and other operating income: approximately 10% to 15% of revenue. This includes healthcare management, virtual care, preventative health, and other service contracts.
That concentration matters. It means Medibank’s long-term profile depends mostly on membership trends, premium pricing, claims costs, and regulation in Australian private health insurance, while the health services arm offers a smaller but strategically useful second leg for growth.
Over the last several years, total revenue has moved upward from a little above A$7.0 billion to more than A$9.3 billion, while net income has also improved overall despite some volatility along the way. The broad pattern is a company with a large, recurring customer base and rising scale, although margins can shift as claims costs and operating expenses move.
The operating picture shows a business that has expanded revenue consistently, with gross profit and operating income also rising over time. The latest year stands out for stronger earnings, although some line items appear unusually volatile versus prior years, so the cleaner long-term takeaway is steady top-line growth supported by recurring premium revenue.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Insurance - Specialty | |
| Market Cap ⓘ | $10.74B | |
| Beta ⓘ | 0.06 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 35.45 | 12.26 |
| P/B Ratio ⓘ | 3.04 | 1.23 |
| FCF Yield ⓘ | 9.05% | 10.40% |
| Dividend Yield ⓘ | 4.92% | 3.02% |
| EBIT / EV ⓘ | N/A | 8.14% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 12.60% | 9.35% |
| RPS Growth (5Y CAGR) ⓘ | 17.38% | 12.19% |
| EPS Growth (5Y CAGR) ⓘ | -34.61% | -9.53% |
| BVPS Growth (5Y CAGR) ⓘ | 16.12% | 4.99% |
| Margin Growth (5Y Trend) ⓘ | 2.19% | -3.86% |
| FCF Growth (5Y CAGR) ⓘ | -10.24% | 4.81% |
| DPS Growth (5Y CAGR) ⓘ | 19.72% | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.49% |
| ROE (Latest) ⓘ | 47.12% | 13.90% |
| ROA (Latest) ⓘ | 25.43% | 1.55% |
| ROIC (5Y Median) ⓘ | 22.61% | 7.86% |
| ROE (5Y Median) ⓘ | 22.43% | 12.17% |
| ROA (5Y Median) ⓘ | 10.85% | 1.30% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.66 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | -0.16 | 0.92 |
| Operating Margin (Latest) ⓘ | N/A | 22.30% |
| Operating Margin (5Y Median) ⓘ | 8.94% | 24.63% |
| Debt to Equity (Latest) ⓘ | 11.27% | 58.56% |
| Profit Margin (Latest) ⓘ | 6.87% | 26.57% |
| Free Cash Flow (Latest) ⓘ | $971.74M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +142.34% | +88.33% |
| 12M Return (excl. last month) ⓘ | +30.43% | +19.38% |
| 6M Return ⓘ | +42.60% | +4.75% |
| Price vs. 200-Day MA ⓘ | N/A | +3.50% |
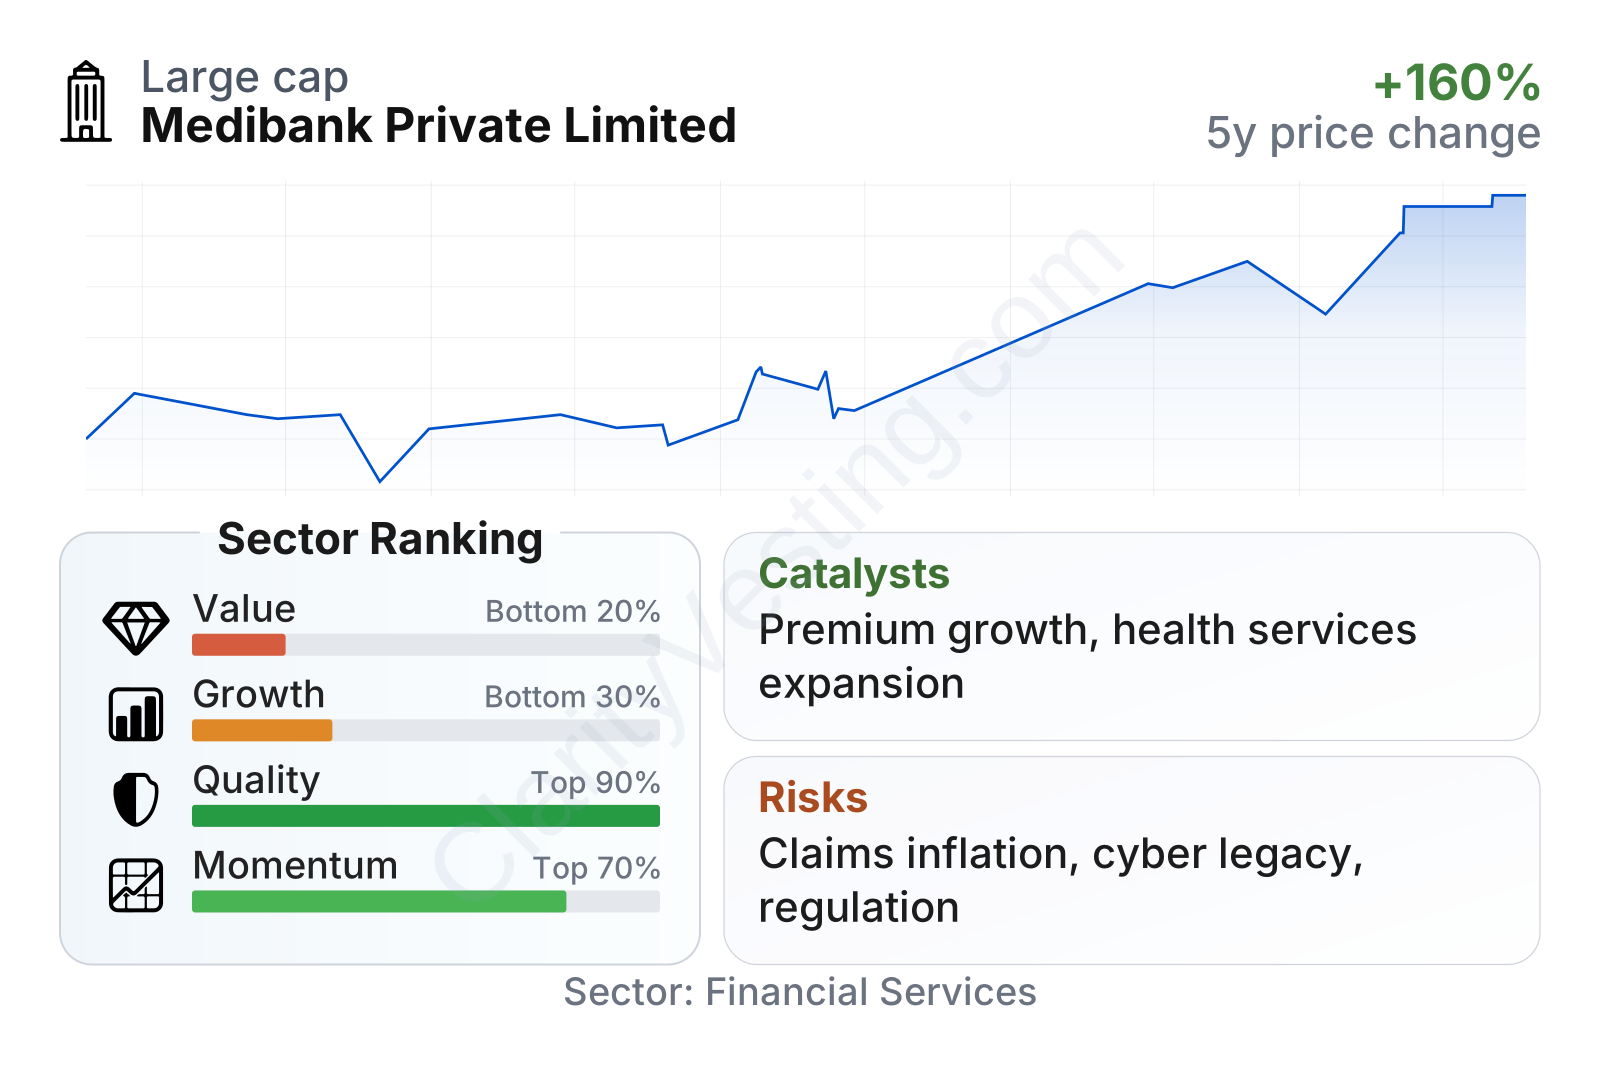
Medibank is a large insurance company by market value, but its share price behavior has been unusually calm, with a very low beta. Profitability metrics are strong relative to the broader financial sector: return on equity is around 47% and return on assets is also far above sector norms. The balance sheet looks conservative, with debt to equity near 11% and net debt metrics indicating low leverage.
At the same time, the valuation profile is not cheap on standard measures. The earnings multiple and price-to-book ratio both sit well above sector medians, which explains why the value ranking is weak even though quality is high. Growth is mixed: revenue and book value have advanced at a healthy pace, but earnings and free cash flow trends over five years have been less consistent.
Market performance has been solid. Over the last three years and over shorter recent periods, the stock has outperformed the sector median, which suggests improving confidence in the company’s earnings resilience and business quality.
Growth
Medibank operates in a sector that tends to grow more slowly than technology or high-end consumer markets, but it benefits from powerful structural drivers. Australia has an aging population, ongoing demand for healthcare, and a mixed public-private system that leaves room for private insurers to remain relevant. Healthcare spending usually rises over time, and private cover can become more attractive when customers want faster access, broader provider choice, or additional services not fully covered elsewhere.
The company’s strategy appears sensible for that environment. The core objective is to defend and expand its insurance membership while building a broader healthcare platform around it. That matters because a pure insurer mainly captures value from underwriting and premium pricing, while an insurer with health services can also improve member engagement, lower churn, and potentially manage claims more effectively through prevention and early intervention.
Medibank also has room to benefit from pricing discipline. In private health insurance, annual premium adjustments approved by regulators can help offset rising medical costs over time, even if there is sometimes a lag. If membership remains stable and claims inflation stays manageable, this can support gradual earnings growth.
The longer-term earnings record is not perfectly smooth, so the main growth case is less about rapid profit expansion and more about durable compounding from a sticky customer base, disciplined capital use, and selective expansion in adjacent care services. That is reinforced by the company’s strong returns on capital and low leverage.
Book value per share has trended upward over recent years, with a particularly strong step-up in the latest period. That supports the view that underlying capital strength has been building, even when earnings growth looked uneven on a multi-year basis.
A notable catalyst in recent years has been the company’s continued recovery from the 2022 cyberattack. While that incident damaged reputation and created costs, Medibank has since shown an ability to retain scale, restore operating momentum, and keep growing revenue. For a long-term view, the key opportunity is whether it can turn that recovery into stronger member trust and deeper use of its broader health ecosystem.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


