Stock Analysis · Masco Corporation (MAS)
Overview
Masco Corporation is a building products company focused mainly on home improvement and residential construction. Its best-known activities are plumbing fixtures, decorative architectural products, and related home products sold under established brands through home centers, wholesalers, dealers, and e-commerce channels. The business is tied closely to repair and remodeling activity, but it also has exposure to new home construction.
Based on recent annual reporting, Masco generates revenue primarily from two operating segments.
- Plumbing Products — about 60% to 65% of revenue: This includes faucets, showering products, valves, bath hardware, and other plumbing-related items. Key brands include Delta and Hansgrohe. This is the company’s largest business and an important profit contributor.
- Decorative Architectural Products — about 35% to 40% of revenue: This segment includes paints, primers, specialty coatings, and other decorative products, led by Behr. It is heavily exposed to repaint and remodeling demand in North America.
Geographically, Masco is still predominantly tied to North America, with the United States as its main market, while Europe contributes a smaller but meaningful share through plumbing brands such as Hansgrohe.
Over the last several years, the business mix has remained fairly focused rather than highly diversified. Revenue has eased from the 2022 peak, but profitability has held up better than sales. That suggests pricing, brand strength, and operating discipline have partly offset softer housing-related demand.
The operating picture shows a company that has managed to preserve strong gross profit and operating income even while total revenue has trended lower from recent highs. That matters for a long-term view because it points to resilience in margins rather than dependence on volume alone.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $13.48B | |
| Beta ⓘ | 1.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.75 | 22.45 |
| P/B Ratio ⓘ | N/A | 1.98 |
| FCF Yield ⓘ | 10.78% | 6.31% |
| Dividend Yield ⓘ | 1.84% | 1.96% |
| EBIT / EV ⓘ | 8.18% | 4.81% |
| PEG ⓘ | 1.56 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -2.90% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 1.92% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | -8.38% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 6.22% |
| Margin Growth (5Y Trend) ⓘ | 6.79% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | 1.94% | 10.98% |
| DPS Growth (5Y CAGR) ⓘ | 10.27% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 35.88% | 10.92% |
| ROA (Latest) ⓘ | 16.52% | 5.41% |
| ROIC (5Y Median) ⓘ | 34.42% | 9.21% |
| ROA (5Y Median) ⓘ | 15.84% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 2.20 | 2.07 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.30 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 1.97 | 1.43 |
| Net Debt / Assets ⓘ | 54.53% | 19.27% |
| EBITDA / Interest ⓘ | 14.49 | 9.53 |
| Operating Margin (Latest) ⓘ | 17.59% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 14.99% | 10.27% |
| Debt to Equity (Latest) ⓘ | -956.99% | 65.48% |
| Profit Margin (Latest) ⓘ | 11.61% | 6.62% |
| Free Cash Flow (Latest) ⓘ | $1.45B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +32.90% | +58.56% |
| 12M Return (excl. last month) ⓘ | +0.15% | +15.63% |
| 6M Return ⓘ | +12.67% | +4.19% |
| Price vs. 200-Day MA ⓘ | -3.13% | +0.93% |
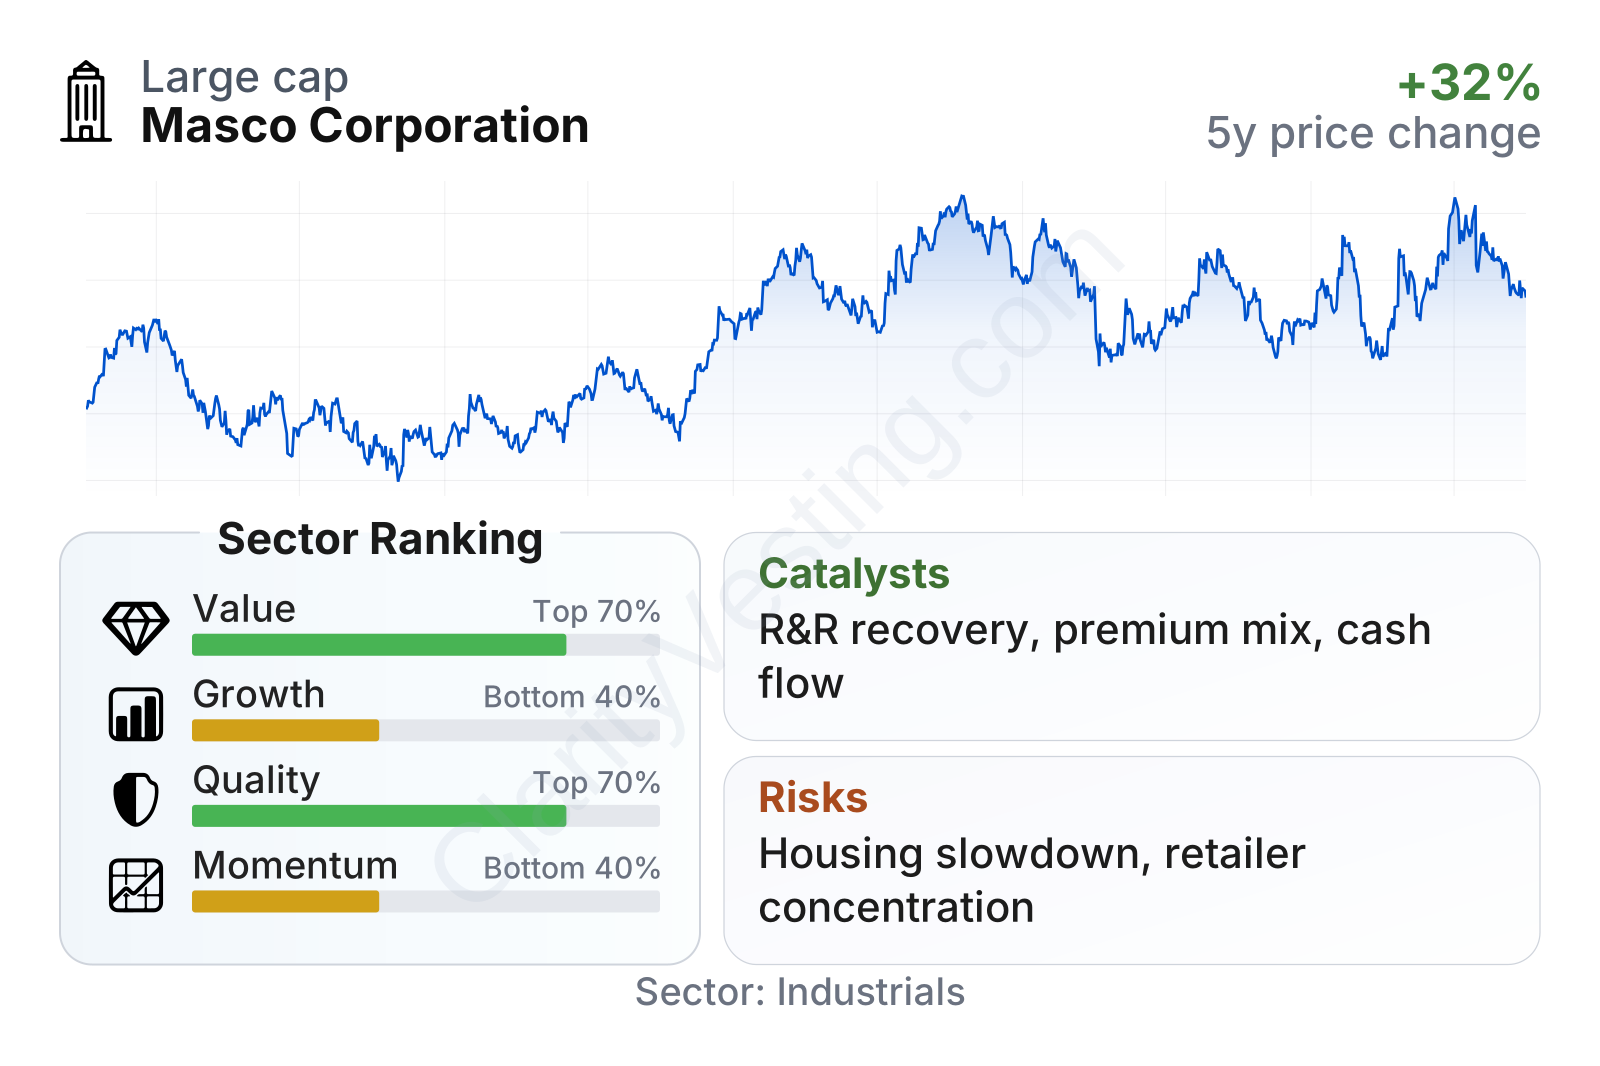
Masco is a mid-to-large building products company with above-average share price volatility, as shown by a beta around 1.3. On valuation, it screens below the sector median on earnings multiples while offering a stronger free cash flow yield than many peers. Quality metrics are a clear strength: returns on invested capital and assets are well above typical sector levels, and operating margins are also materially stronger than the industry median. The weaker area is growth, where recent revenue trends and longer-term sales expansion have lagged the broader sector.
The stock history shows a cyclical pattern rather than a straight line upward. Shares recovered strongly from 2022 lows, moved through a period of volatility, and more recently rebounded again. That behavior fits the company’s exposure to housing activity, renovation demand, and changing expectations around interest rates.
Growth
Masco operates in a sector that can grow over time, but it rarely does so smoothly. Long-term support comes from aging housing stock, ongoing repair and remodeling needs, premiumization in kitchens and bathrooms, water-efficiency upgrades, and the need for repainting and maintenance. In other words, the underlying demand is real, but it is cyclical and heavily influenced by mortgage rates, consumer confidence, and housing turnover.
Masco’s strategy is sensible for that environment. The company is concentrated in categories where brands matter, replacement demand is recurring, and distribution relationships are hard to replicate quickly. Plumbing fixtures and paint are not fast-moving technology markets, but they can be attractive because customers often value trust, design, and shelf presence more than the cheapest possible option. That tends to support pricing power and margin durability.
Recent top-line growth has been uneven. After stronger growth in 2021 and early 2022, revenue turned negative for an extended stretch, with only limited signs of stabilization afterward. A brief return to positive year-over-year growth in early 2026 was encouraging, but it was followed by another decline. That pattern suggests Masco is still navigating a slow demand backdrop rather than entering a clear multi-quarter expansion.
Cash generation is an important offset to the modest revenue profile. Free cash flow remains solid in absolute terms and has stayed near the high hundreds of millions to over $1 billion range in recent years. That gives Masco flexibility for dividends, share repurchases, debt service, and selective reinvestment even when sales growth is soft.
A meaningful catalyst is any improvement in the U.S. repair-and-remodel market if interest rates stabilize or decline. Lower financing pressure can support home turnover and renovation spending, both of which help Masco’s product categories. Another catalyst is continued product mix improvement in premium plumbing and paint, where brand-led pricing can lift profit even without rapid unit growth. Recent company communications have also emphasized productivity and cost discipline, which can protect earnings if volume recovery remains gradual.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


