Stock Analysis · MARA Holdings Inc (MARA)
Overview
MARA Holdings Inc is primarily a Bitcoin mining company. In simple terms, it operates large fleets of specialized computers that help secure the Bitcoin network and, in return, earn Bitcoin and related rewards. Over time, the company has tried to expand beyond just mining by building more control over its infrastructure, including data centers, energy-related arrangements, and digital asset management. Its results are therefore heavily influenced by Bitcoin prices, mining economics, and the cost of power and equipment.
The business is still concentrated in a small number of economic drivers. Based on recent annual disclosures and operating updates, the company’s revenue is dominated by digital asset mining, while the rest comes from smaller activities tied to hosting, technology, and other services when applicable.
- Bitcoin mining revenue: approximately 90% to 95% of total revenue in recent periods. This includes Bitcoin earned from block rewards and transaction fees, typically recognized based on the fair value of the digital assets received.
- Other revenue and services: approximately 5% to 10%. This can include hosting-related activity, technology or infrastructure services, and other smaller items that are not the core earnings engine.
The broad financial picture shows a company that has grown revenue sharply over the past several years, but with profitability that swings dramatically from year to year. Revenue increased from roughly $159 million in 2021 to about $907 million in 2025, yet earnings moved between large gains and large losses. That pattern is typical of a business tied to volatile digital asset prices and capital-intensive operations.
The long-term trend is clear: MARA has scaled its operations aggressively, but higher revenue has not translated into stable operating performance. Costs expanded rapidly in 2024 and 2025, and the business became much more expense-heavy as it pushed for growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Capital Markets | |
| Market Cap ⓘ | $2.54B | |
| Beta ⓘ | 5.25 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 12.01 |
| P/B Ratio ⓘ | 1.37 | 1.48 |
| FCF Yield ⓘ | -60.81% | 8.77% |
| Dividend Yield ⓘ | N/A | 3.01% |
| EBIT / EV ⓘ | -44.69% | 8.31% |
| PEG ⓘ | 0.10 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -34.90% | 6.70% |
| RPS Growth (5Y CAGR) ⓘ | 12.36% | 12.35% |
| EPS Growth (5Y CAGR) ⓘ | -13.04% | -0.27% |
| BVPS Growth (5Y CAGR) ⓘ | 9.15% | 4.83% |
| Margin Growth (5Y Trend) ⓘ | N/A | -4.16% |
| FCF Growth (5Y CAGR) ⓘ | -19.04% | 4.69% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 8.82% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -28.09% | 9.49% |
| ROE (Latest) ⓘ | -102.88% | 14.02% |
| ROA (Latest) ⓘ | -45.43% | 1.53% |
| ROIC (5Y Median) ⓘ | -1.17% | 7.80% |
| ROE (5Y Median) ⓘ | -7.27% | 12.09% |
| ROA (5Y Median) ⓘ | -4.21% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.88 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.71 |
| Operating Margin (Latest) ⓘ | -291.76% | 23.37% |
| Operating Margin (5Y Median) ⓘ | -8.14% | 24.29% |
| Debt to Equity (Latest) ⓘ | 130.82% | 59.34% |
| Profit Margin (Latest) ⓘ | N/A | 26.65% |
| Free Cash Flow (Latest) ⓘ | -$1.55B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -52.21% | +73.29% |
| 12M Return (excl. last month) ⓘ | -61.19% | +18.35% |
| 6M Return ⓘ | -62.47% | +3.24% |
| Price vs. 200-Day MA ⓘ | -51.83% | +2.17% |
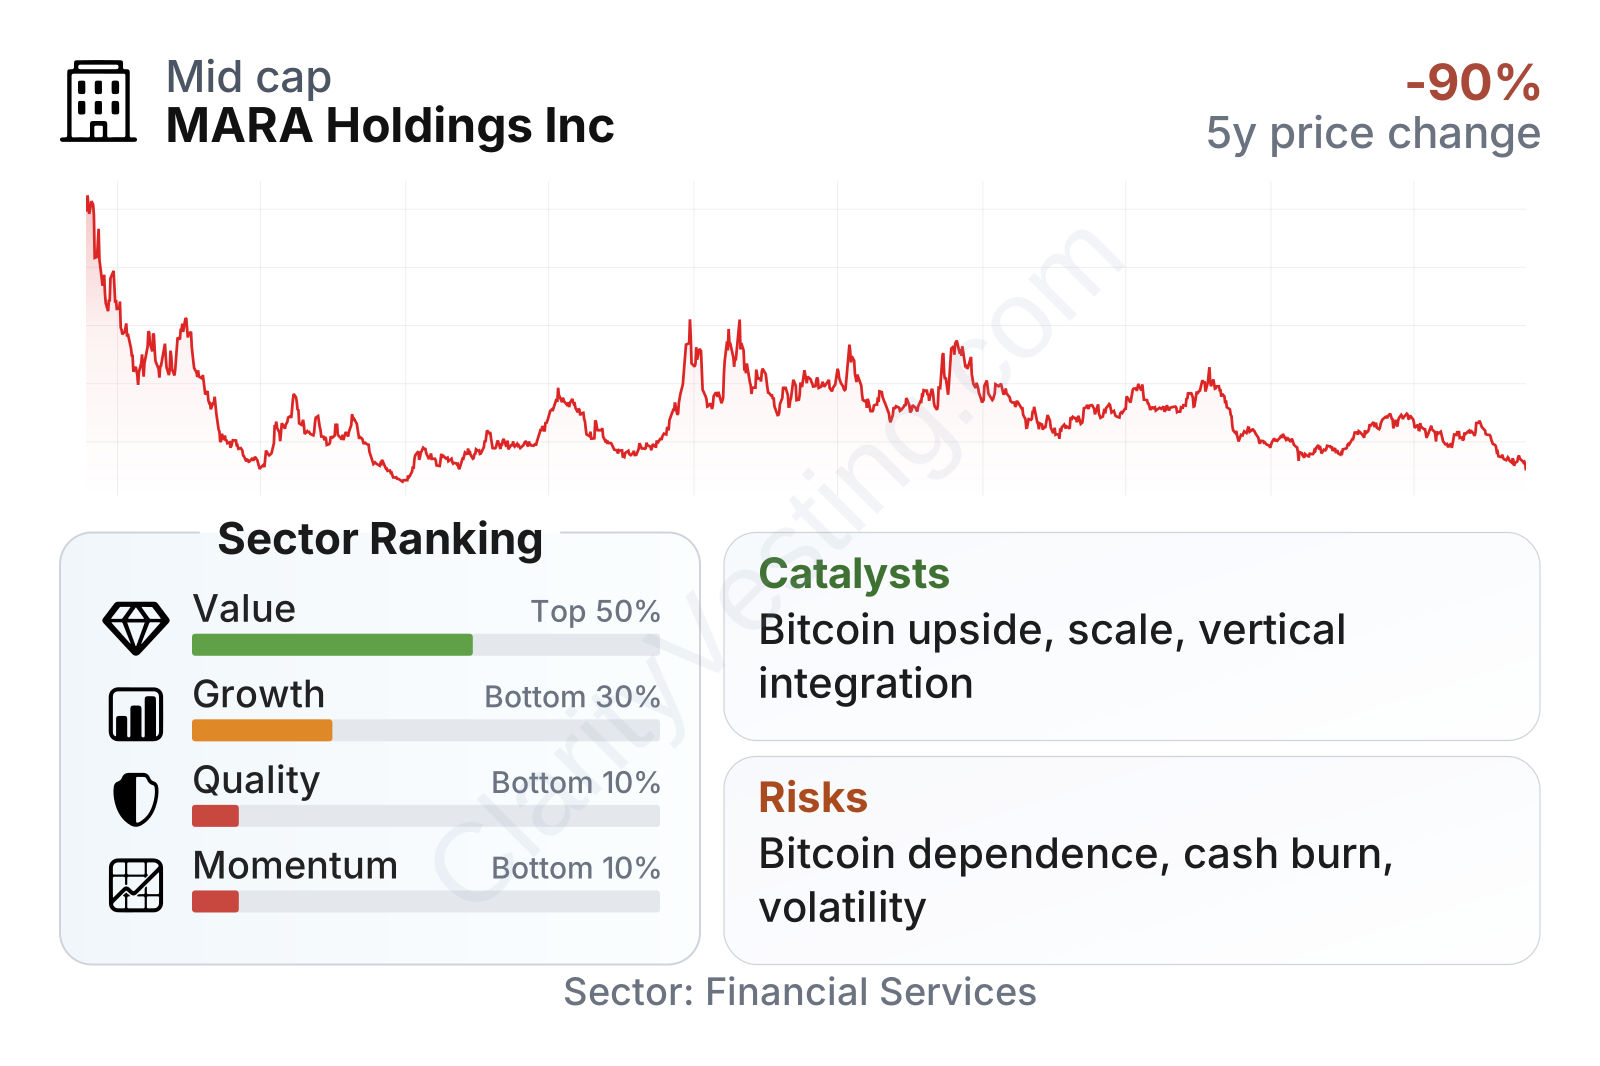
MARA is a mid-sized public company with very high share-price volatility. Its beta is above 5, which is exceptionally elevated and helps explain why the stock has moved sharply both up and down over short periods. The factor profile is weak overall: value ranks in the lower half of the sector, while growth, quality, and momentum all sit near the bottom of the peer group. The balance sheet looks less stretched than many financial-sector companies on debt-to-equity, but that is offset by negative free cash flow, weak operating returns, and recent share-price underperformance.
Growth
MARA operates in a sector that can expand quickly when Bitcoin adoption, institutional participation, and transaction activity increase. The company’s strategy also follows a logical industrial pattern: add mining capacity, improve control over power and infrastructure, and retain exposure to Bitcoin through treasury holdings. If Bitcoin remains an important digital asset over the next decade, scale can matter because larger operators may negotiate better equipment access, broader financing options, and more efficient energy arrangements.
There are also real signs of long-term balance-sheet building. Book value per share rose strongly over the past five years overall, even though it pulled back after 2024. That suggests the company was able to add net asset value during the expansion phase, helped by periods of strong digital asset pricing and equity capital access.
The difficulty is that growth has not been smooth. Recent metrics show year-over-year revenue declining by roughly 35%, which is far below the sector median growth rate. Free cash flow has also been deeply negative, showing that expansion has required heavy spending. In other words, MARA’s growth model is real, but it is expensive and highly cyclical.
Earnings per share illustrate this instability clearly. MARA moved from profits in some years to large losses in others, and the most recent trailing periods remain negative. For a long-term reader, this means that operating scale alone has not yet created a predictable earnings base.
One important catalyst is the company’s direct leverage to Bitcoin. When Bitcoin prices rise, mining economics, treasury values, and market sentiment can all improve quickly. Another potential tailwind is the broader shift in the mining industry toward larger, better-capitalized operators after weaker players were pressured by prior downturns. MARA has also continued presenting itself as a more vertically integrated digital infrastructure operator rather than just a pure miner, which could support a broader business model over time if execution improves.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


