Stock Analysis · Lundin Gold Inc (LUGDF)
Overview
Lundin Gold Inc is a gold mining company focused on one core asset: the Fruta del Norte mine in southeastern Ecuador. This is a large underground gold mine that also produces silver as a by-product. In simple terms, the company drills, extracts ore, processes it, and sells the recovered precious metals. Because the business is centered on a single producing mine, its performance depends heavily on how well that asset operates, how much metal it produces, and the market prices of gold and silver.
The company’s revenue mix is unusually simple because it is not spread across many mines or business lines. Based on recent annual reporting, revenue is overwhelmingly tied to precious metal sales from Fruta del Norte.
- Gold sales: approximately 94% to 97% of revenue. This is the main business driver and reflects doré production sold under commercial arrangements tied to international gold prices.
- Silver sales: approximately 3% to 6% of revenue. Silver is produced alongside gold and provides a smaller but useful additional income stream.
The business model is therefore easy to understand: one high-grade mine, one main metal, and cash generation that rises or falls mainly with production levels, operating costs, and gold prices. Over the last several years, the company has converted a growing share of revenue into operating profit and net income, showing stronger efficiency as the mine matured.
The financial flow highlights a sharp improvement since 2022. Revenue has expanded materially, while operating profit and net income have risen even faster, which suggests stronger realized metal prices and good cost absorption. The company has also moved from a period with meaningful financing costs to a much cleaner earnings profile.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $15.57B | |
| Beta ⓘ | 1.49 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.68 | 16.90 |
| P/B Ratio ⓘ | 28.47 | 1.65 |
| FCF Yield ⓘ | 7.12% | 5.76% |
| Dividend Yield ⓘ | 5.88% | 2.13% |
| EBIT / EV ⓘ | 8.70% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.50% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 23.97% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 32.63% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 12.94% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 14.51% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 29.77% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 92.43% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 90.52% | 9.26% |
| ROA (Latest) ⓘ | 57.34% | 4.91% |
| ROIC (5Y Median) ⓘ | 39.22% | 7.70% |
| ROA (5Y Median) ⓘ | 13.88% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.95 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | 65.56% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 48.51% | 11.80% |
| Debt to Equity (Latest) ⓘ | N/A | 40.56% |
| Profit Margin (Latest) ⓘ | 46.32% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.11B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +535.65% | +68.89% |
| 12M Return (excl. last month) ⓘ | +16.52% | +30.21% |
| 6M Return ⓘ | -16.63% | -4.16% |
| Price vs. 200-Day MA ⓘ | -2.94% | -1.27% |
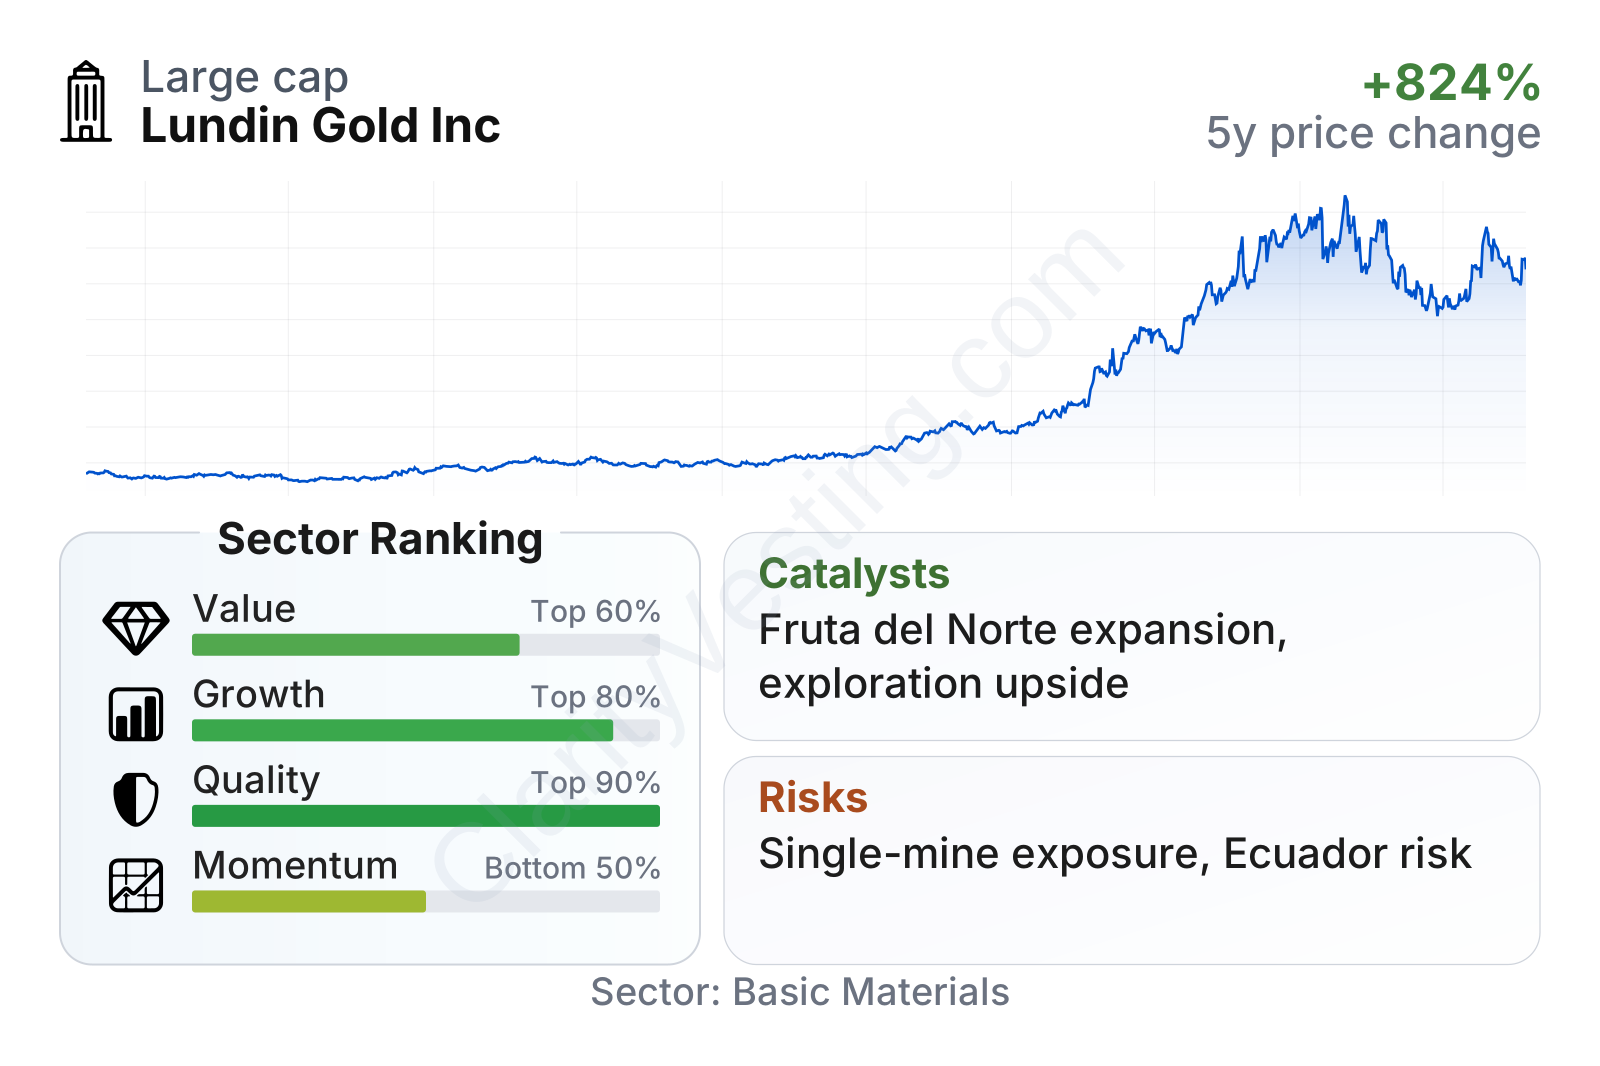
Lundin Gold stands out on quality and growth measures within the gold sector. Profitability is exceptionally strong, with operating and net margins far above typical peers, and free cash flow generation is also robust. On valuation, the picture is more mixed: earnings-based measures are not stretched relative to the sector, but the price-to-book ratio is extremely high, reflecting how strongly the market values the mine’s earning power rather than its accounting book value. Momentum has cooled after a very large multiyear share price run, which fits a stock that has already been re-rated significantly.
The company is also now a large-cap name in its niche, with above-average share price volatility. That matters because gold stocks often move with both metal prices and country-specific news, so short-term swings can be much larger than in a broad market index.
Growth
Gold mining is not a classic high-volume growth industry, but it remains a strategically important sector. Demand is supported by jewelry, investment, central bank purchases, and the metal’s role as a store of value during periods of inflation, currency weakness, or geopolitical stress. That backdrop can create favorable pricing conditions even when physical demand growth is not rapid in percentage terms.
For Lundin Gold, future growth depends less on entering many new businesses and more on extending and optimizing the value of Fruta del Norte. That strategy makes sense because the company already controls a world-class asset with high margins. In mining, a very profitable mine with exploration upside can create more value than a diversified portfolio of weaker operations.
Revenue growth has been uneven from quarter to quarter, which is normal for a miner because production timing, grades, shipment schedules, and metal prices can all shift results. Even so, the broader trend has been positive, with especially strong acceleration through 2024 and 2025. Longer-term growth rates remain far ahead of the sector median, showing that this has not been a one-quarter phenomenon.
Cash generation is one of the clearest positives. Free cash flow has climbed substantially over time, and recent levels place the company in a much stronger position to fund dividends, exploration, and expansion work without leaning heavily on outside financing. That is an important growth support because self-funded miners usually have more flexibility than those that need constant debt or equity issuance.
A key catalyst is ongoing exploration around Fruta del Norte and across the broader land package in Ecuador. If drilling continues to extend mine life or define additional resources near existing infrastructure, the economics can be especially attractive because processing and site facilities are already in place. Another potential driver is any sustained period of high gold prices, since a large share of additional price gains can flow into profit when a mine is already operating efficiently.
Recent company reporting and investor materials have also emphasized continued operational consistency, shareholder returns, and advancement of near-mine opportunities. For a company with one flagship operation, that combination matters: stable execution supports present cash flow, while exploration success is what can lengthen the runway.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


