Stock Analysis · Latigo Biotherapeutics Inc (LTGO)
Overview
Latigo Biotherapeutics is a clinical-stage biotechnology company focused on developing non-opioid pain medicines. Its research is centered on selectively targeting sodium channels involved in pain signaling, especially Nav1.8, with the goal of delivering pain relief without the addiction and safety issues associated with opioids. The company is still in the development stage, so its value depends much more on the progress of its drug candidates than on current commercial sales.
At this stage, Latigo does not report recurring product revenue. Based on recent public filings, its economics are currently driven by cash raised from financing rather than sales of approved medicines. That is common for young biotech companies, but it also means the business has not yet proven commercial demand.
The current revenue mix is therefore very simple:
- Product revenue: 0%. Latigo has no approved products on the market.
- Collaboration or licensing revenue: no meaningful recurring revenue disclosed as a major operating source in the latest annual reporting.
- Financing cash inflows: effectively the company’s main source of funding, coming from prior private financing rounds and public market capital raised to fund research and development.
That business profile makes Latigo less comparable to established pharmaceutical companies and more comparable to other early-stage biotech firms whose market value reflects pipeline potential, intellectual property, and clinical execution.
The spending pattern shows a classic development-stage biotech model: no revenue, heavy research spending, and rising operating losses as programs move forward. Research and development represented the overwhelming majority of operating expenses in 2025, which is consistent with a company prioritizing clinical progress over near-term profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $1.03B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | N/A | 3.08 |
| FCF Yield ⓘ | -8.87% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -7.45% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | N/A | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.24% |
| ROA (Latest) ⓘ | N/A | 3.01% |
| ROIC (5Y Median) ⓘ | N/A | 4.60% |
| ROA (5Y Median) ⓘ | N/A | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | N/A | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | N/A | 9.27% |
| Operating Margin (5Y Median) ⓘ | N/A | 7.38% |
| Debt to Equity (Latest) ⓘ | N/A | 28.58% |
| Profit Margin (Latest) ⓘ | N/A | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$91.31M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +42.80% |
| 12M Return (excl. last month) ⓘ | N/A | +18.50% |
| 6M Return ⓘ | N/A | +7.57% |
| Price vs. 200-Day MA ⓘ | N/A | +5.12% |
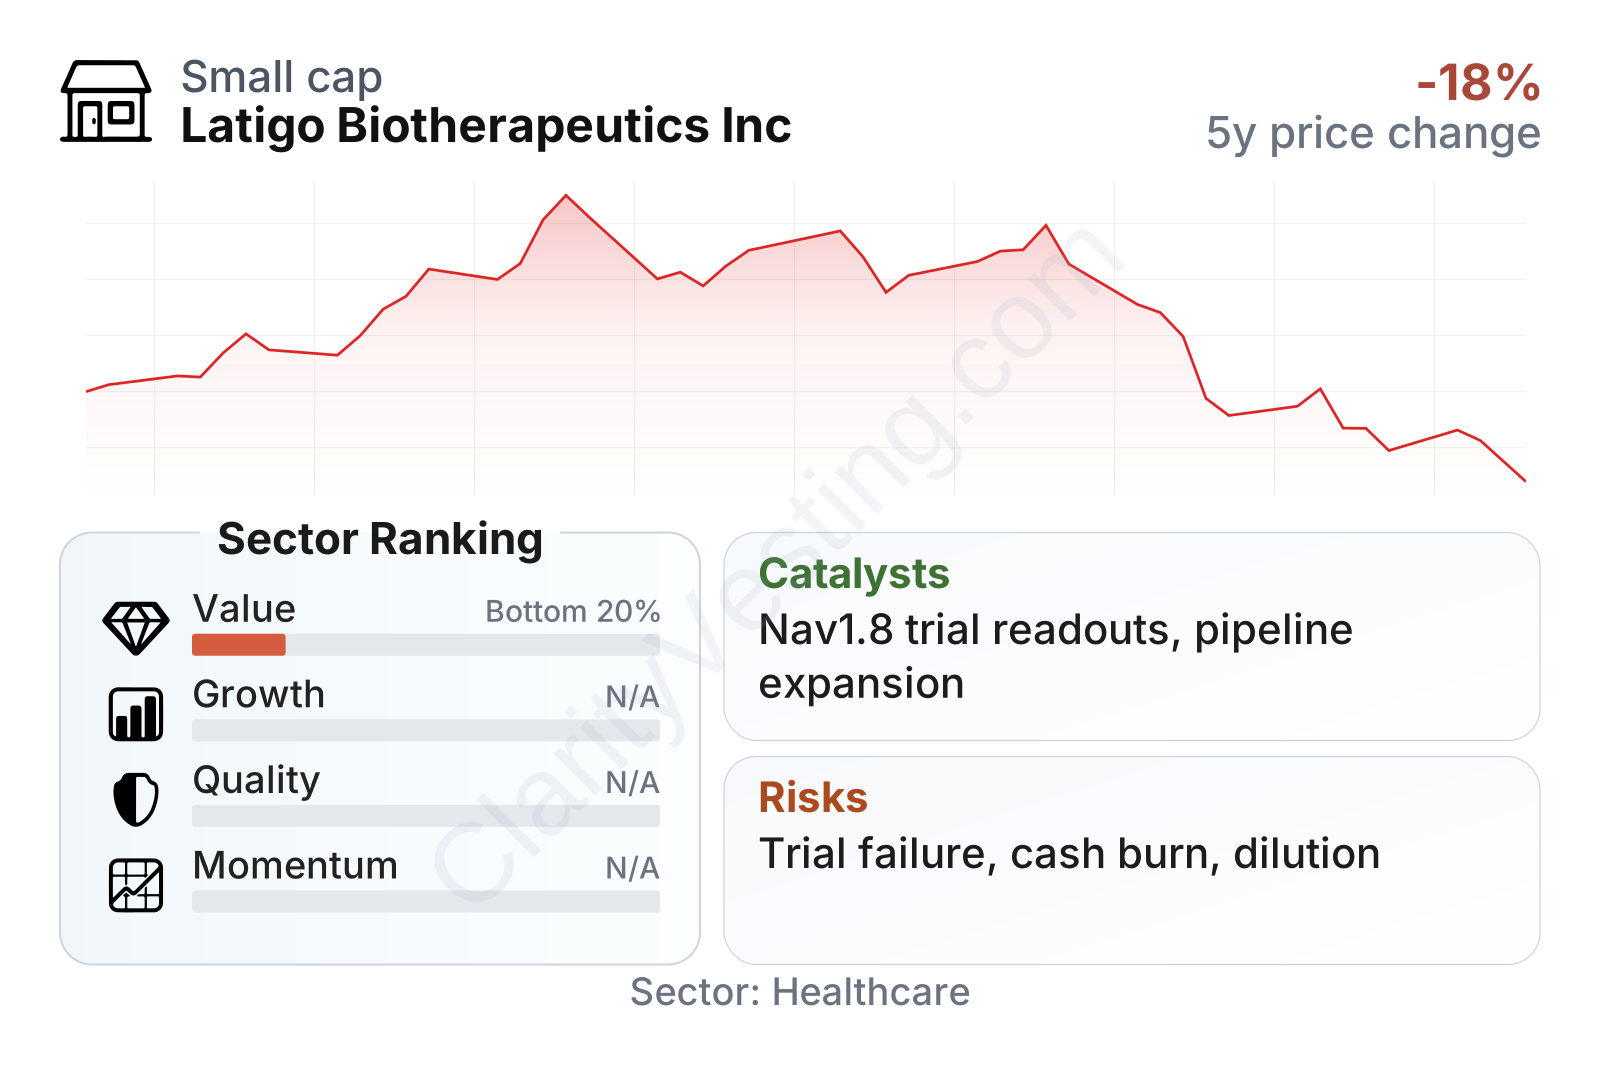
Latigo is still in a pre-revenue phase, so many traditional valuation and profitability measures look weak or are not very meaningful yet. The company screens poorly on value because it has negative free cash flow, negative operating earnings, and no earnings-based multiples to anchor the share price. Free cash flow was deeply negative, and that is expected for a biotech funding trials before commercialization.
On quality and growth metrics, the picture is also incomplete rather than simply poor. Revenue growth is 0% because there is no product revenue yet, while profit margin is also effectively 0% in practical terms because the company remains loss-making. The more useful takeaway is balance-sheet context: Latigo is a small-cap biotech with meaningful cash needs and no operating income, so future financing capacity matters more than current accounting ratios.
The stock history is still limited as a newly public company, which makes momentum signals less informative than they would be for a mature listed business. For long-term analysis, pipeline milestones matter far more than chart patterns at this stage.
Growth
Latigo operates in a part of healthcare with clear long-term demand. Chronic pain and acute pain remain very large treatment categories, and the medical system continues to search for alternatives to opioids. That broader industry backdrop is favorable because regulators, physicians, and payers all have reasons to support effective non-opioid options if they can show meaningful pain reduction with an acceptable safety profile.
The company’s strategy is coherent. Rather than trying to compete broadly across many therapeutic areas, Latigo is concentrated on pain biology and on ion-channel targets that are already scientifically validated as relevant to pain transmission. This focus can be an advantage because it allows management to allocate capital and scientific resources around a relatively narrow platform instead of spreading effort across unrelated programs.
Its main potential growth catalysts come from clinical progress. If the lead candidates generate convincing efficacy and safety data, Latigo could improve its strategic position substantially, either by advancing independently, partnering with a larger pharmaceutical company, or becoming more visible as an acquisition candidate. For a company like this, each successful clinical readout can shift perceived value far more than incremental quarterly financial changes.
Recent company communications have highlighted continued advancement of its pain pipeline, including programs aimed at both acute and chronic pain settings. That matters because success in more than one pain use case could widen the future commercial opportunity and reduce dependence on a single market niche. In biotech, the market often rewards platform breadth when it is paired with a clear biological rationale.
Another positive industry factor is that non-opioid pain development has attracted increasing attention after recent progress elsewhere in the sector. That does not guarantee Latigo will succeed, but it supports the idea that the company is operating in an area where strategic interest could remain strong if data are promising.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


