Stock Analysis · Lundin Mining Corporation (LNDMY)
Overview
Lundin Mining Corporation is a diversified base-metals producer with a strong emphasis on copper. The company operates mines in the Americas and Europe and sells metals that are essential to construction, industrial activity, power grids, electronics, and the energy transition. Copper is the centerpiece of the business, but Lundin Mining also produces meaningful amounts of gold, zinc, and nickel, which help diversify revenue and cash flow across commodity cycles.
The company’s revenue is mainly generated by the sale of mined metals and, in some cases, by-products recovered during processing. Based on the latest full-year company reporting, the revenue mix is roughly concentrated as follows:
- Copper: about 60% to 65% — the core product, used in electrical networks, renewable energy systems, industrial equipment, and transportation.
- Gold: about 15% to 20% — largely a by-product at some operations, helping support margins when copper markets are weaker.
- Zinc: about 10% to 15% — used mainly for steel galvanizing and industrial applications.
- Nickel: about 5% to 10% — important for stainless steel and increasingly relevant to battery supply chains.
- Other metals, including silver and lead: low single-digit share — smaller contributors that still add by-product value.
Lundin Mining is not the largest global miner, but it is large enough to operate multiple long-life assets and to pursue expansion projects that can materially affect future production. Its business profile is therefore simpler than that of the biggest diversified mining groups, while still offering more diversification than a single-mine company.
The recent financial progression has been volatile, which is normal in mining, but the broad direction has improved. Revenue moved from roughly $3.0 billion in 2022 to more than $4.0 billion in 2025, while gross profit expanded even faster. That pattern suggests a stronger production and pricing backdrop, although annual earnings can still swing sharply because of non-cash charges, financing costs, and commodity-price movements.
The multi-year flow of revenue and costs points to a business that became more profitable again after a weaker 2023-2024 period. Sales and gross profit both improved strongly into 2025, and net income rebounded sharply, showing how sensitive the company is to better mine performance and stronger metal markets.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $21.34B | |
| Beta ⓘ | 2.10 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.07 | 16.92 |
| P/B Ratio ⓘ | 3.72 | 1.66 |
| FCF Yield ⓘ | 5.26% | 5.83% |
| Dividend Yield ⓘ | 0.31% | 2.07% |
| EBIT / EV ⓘ | 7.86% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 38.10% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 6.33% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 3.58% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 9.96% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 168.46% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | -7.24% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 19.23% | 9.59% |
| ROA (Latest) ⓘ | 15.16% | 4.92% |
| ROIC (5Y Median) ⓘ | N/A | 7.91% |
| ROA (5Y Median) ⓘ | 2.54% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.15 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.93 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 51.69 | 12.38 |
| Operating Margin (Latest) ⓘ | 37.96% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 20.06% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | 32.51% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $1.12B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +73.47% |
| 12M Return (excl. last month) ⓘ | N/A | +27.59% |
| 6M Return ⓘ | -12.67% | -4.02% |
| Price vs. 200-Day MA ⓘ | N/A | -0.65% |
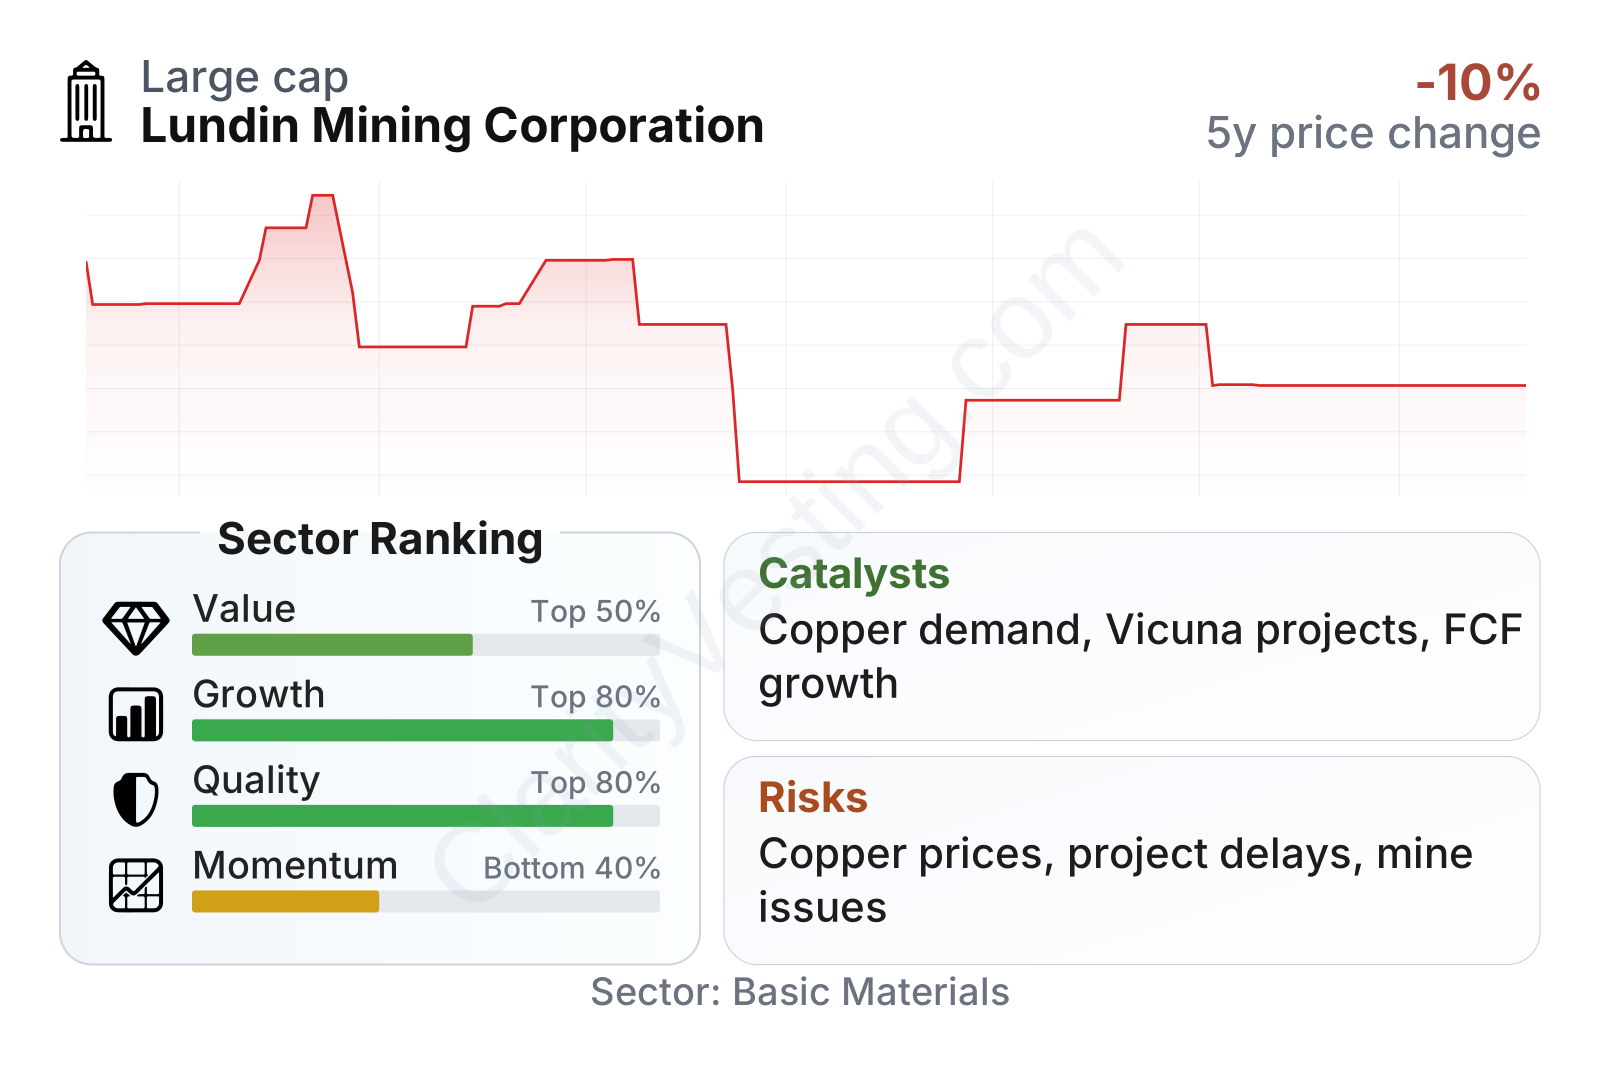
Lundin Mining sits in an interesting middle ground. On growth measures, it ranks well above much of the sector, supported by strong recent revenue expansion and very strong free-cash-flow improvement over a multi-year period. Profitability also looks solid in several areas, with return on assets and profit margin well ahead of typical sector levels. Free cash flow of a little over $1.1 billion over the trailing twelve months is a meaningful figure for a company of this size.
On valuation, the picture is more mixed. The earnings multiple is slightly below the sector median, which on its own does not look stretched. However, the price-to-book ratio is clearly above the sector median, and the dividend yield is well below what many materials companies offer. In other words, the market appears to be assigning some premium to asset quality and growth potential, but not to the point of an extreme earnings valuation.
Market behavior has been weaker than the sector recently. The stock drifted lower over the past several months, and momentum indicators place it near the lower end of the peer group. With a beta above 2, the shares have also been much more volatile than the broader market, which is typical for a miner tied to copper sentiment and project developments.
Growth
Lundin Mining operates in a part of the mining industry that has a strong long-term demand argument. Copper is central to electrification, grid expansion, data-center buildout, electric vehicles, and renewable power systems. Even when short-term industrial demand fluctuates, the long-range need for new copper supply remains a major industry theme because large new mines are difficult, expensive, and slow to develop.
The company’s strategy broadly fits that backdrop. It has been building a portfolio centered on copper, while still keeping supporting exposure to gold, zinc, and nickel. That gives it leverage to favorable copper fundamentals without making the entire business dependent on a single metal or one producing asset. For long-term analysis, that balance matters because mining returns are often shaped by both geology and capital allocation discipline.
A major growth catalyst is the company’s exposure to expansion and development projects that can lift copper output over time. Lundin Mining has also increased its strategic presence in large-scale copper development through its interest in the Vicuna district, including the Josemaria and Filo del Sol area, which is one of the more important emerging copper regions in South America. Assets like these are not overnight earnings drivers, but they can materially reshape the company’s future production base if execution stays on track.
Recent operating and financial trends also support the growth case. Revenue growth over the last year has been far stronger than the sector median, and free cash flow has improved dramatically compared with the company’s own earlier base. That matters because in mining, growth funded by internally generated cash is usually more durable than growth that depends mainly on debt or repeated equity issuance.
Another important catalyst is copper pricing itself. If the market remains structurally tight because of underinvestment in new supply and steady electrification demand, companies with meaningful copper exposure can see a strong effect on margins and cash generation. Lundin Mining is especially sensitive to that dynamic because copper is its largest revenue source by a wide margin.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


