Stock Analysis · Lennox International Inc (LII)
Overview
Lennox International Inc. is a climate control company focused on heating, ventilation, air conditioning, and refrigeration equipment. In simple terms, it makes and sells products that help homes, businesses, and food retailers control temperature and air quality. Its brands are used in residential homes, light commercial buildings, and stores that need refrigeration systems.
The company’s business is organized around three main segments. Based on its latest annual reporting, revenue is led by home HVAC equipment and related products, followed by commercial HVAC, then refrigeration.
- Home comfort solutions: about 65% of revenue — residential furnaces, air conditioners, heat pumps, indoor air quality products, replacement parts, and service-related products sold through dealers and distributors.
- Building climate solutions: about 20% of revenue — rooftop units, packaged HVAC systems, controls, and related products for light commercial buildings such as offices, retail locations, schools, and other facilities.
- Specialty climate solutions: about 15% of revenue — refrigeration systems, display cases, and services used by supermarkets, convenience stores, and other food retail customers.
Lennox is not a highly diversified industrial group. It is a more focused company centered on climate systems, which can be an advantage because management, distribution, and product development are concentrated in categories where it already has established brands and dealer relationships.
Over the last several years, the business mix has also benefited from a strong replacement market. Many HVAC systems eventually need to be replaced regardless of the broader economy, which gives Lennox some resilience compared with businesses that depend only on new construction. At the same time, better margins suggest the company has recently converted a larger share of sales into profit than it did a few years ago.
The long-term pattern points to rising revenue and, even more importantly, a noticeably larger share of that revenue flowing through to operating income and net income. That suggests pricing discipline, product mix improvement, and better operating efficiency have mattered as much as top-line growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $12.57B | |
| Beta ⓘ | 1.16 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.04 | 22.29 |
| P/B Ratio ⓘ | 9.83 | 1.98 |
| FCF Yield ⓘ | 5.88% | 6.26% |
| Dividend Yield ⓘ | 1.48% | 1.92% |
| EBIT / EV ⓘ | 6.88% | 4.83% |
| PEG ⓘ | 0.94 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 7.26% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -6.23% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 6.09% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 11.81% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 9.94% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 32.88% | 10.75% |
| ROA (Latest) ⓘ | 19.20% | 5.41% |
| ROIC (5Y Median) ⓘ | 46.21% | 9.37% |
| ROA (5Y Median) ⓘ | 21.99% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.93 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.95 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.73 | 1.39 |
| Net Debt / Assets ⓘ | 43.41% | 19.27% |
| EBITDA / Interest ⓘ | 20.30 | 9.58 |
| Operating Margin (Latest) ⓘ | 19.26% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 15.86% | 10.30% |
| Debt to Equity (Latest) ⓘ | 156.08% | 64.82% |
| Profit Margin (Latest) ⓘ | 14.87% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $738.70M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +8.26% | +67.77% |
| 12M Return (excl. last month) ⓘ | -31.91% | +12.05% |
| 6M Return ⓘ | -25.18% | 0.00% |
| Price vs. 200-Day MA ⓘ | -22.84% | +0.67% |
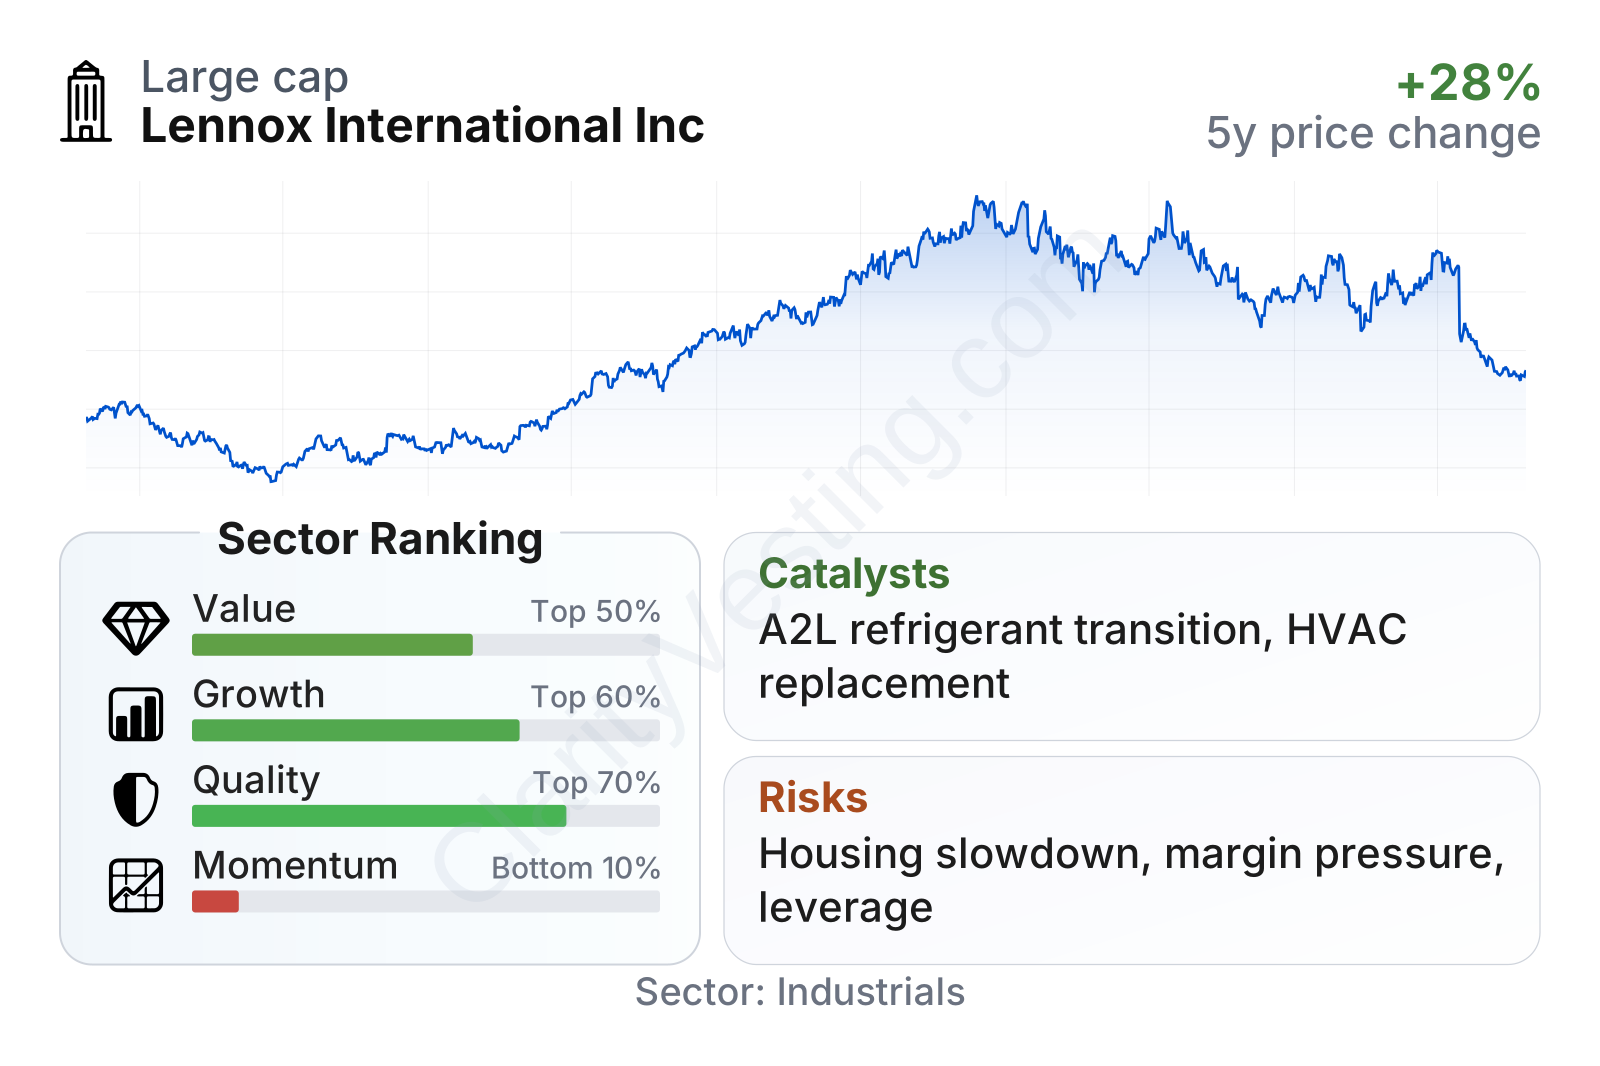
Lennox stands out more for profitability and capital efficiency than for rapid recent growth or stock momentum. Valuation multiples are mixed: the earnings multiple is below the sector median, while the price-to-book ratio is far higher, which often happens with businesses that generate strong returns on capital and carry relatively limited book equity. Profitability metrics are well above many industrial peers, while recent share performance has been weak relative to the broader sector.
Growth
The company operates in a sector with durable long-term demand. Heating and cooling are not optional in most buildings, and regulation is pushing the industry toward higher-efficiency systems. That creates recurring replacement demand as older units are retired and homeowners or businesses upgrade to newer models. Electrification trends, heat pump adoption, stricter efficiency standards, and interest in better indoor air quality all support long-run industry relevance.
Lennox’s strategy broadly fits those trends. The company has emphasized premium residential HVAC, dealer relationships, product innovation, and North American manufacturing and distribution capabilities. In commercial HVAC, replacement demand and efficiency upgrades remain useful drivers. In refrigeration, food retailers are also upgrading equipment to improve energy use and comply with environmental standards.
Recent revenue growth has been positive again after a more uneven stretch. The pattern shows that growth is not perfectly smooth, which is normal for an equipment maker exposed to housing, weather, and distributor inventory adjustments. Still, the latest readings point to renewed expansion rather than a clear deterioration in demand.
Cash generation has improved materially versus earlier periods, even if it has not moved in a straight line every quarter. For a long-term business assessment, that matters because free cash flow is what supports dividends, debt service, acquisitions, factory investment, and share repurchases. Lennox’s five-year free cash flow growth rate is ahead of the sector median, which reinforces the idea that operational execution has been stronger than simple revenue growth alone might suggest.
A meaningful catalyst in the current period is the transition to new refrigerant standards in North America. Industry-wide product refresh cycles can encourage earlier replacement and new equipment demand, especially when distributors and contractors need updated systems. Lennox has also highlighted manufacturing and distribution investments in recent years, which can support service levels and help it defend share in key channels.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


