Stock Analysis · Laboratory Corporation of America Holdings (LH)
Overview
Laboratory Corporation of America Holdings, better known as Labcorp, is one of the largest diagnostic testing and drug-development support companies in the United States. Its business sits at an important point in healthcare: it helps doctors, hospitals, health systems, employers, insurers, pharmaceutical companies, and researchers generate medical information and use it to make treatment or development decisions.
After the 2023 spin-off of its clinical development business, Fortrea, Labcorp became more focused on two main activities. The first is routine and specialized laboratory testing for patients and healthcare providers. The second is laboratory services used by pharmaceutical and biotechnology companies, including central lab work for clinical trials and specialized testing used in drug development.
Based on the company’s recent annual reporting structure, Labcorp’s main revenue sources are approximately:
- Diagnostics Laboratories: about 73% of revenue — routine blood testing, women’s health, oncology testing, genetic and esoteric testing, hospital lab management partnerships, and population health services.
- Biopharma Laboratory Services: about 27% of revenue — central laboratory services for clinical trials, specialized bioanalytical testing, cell and gene therapy support, companion diagnostics, and other lab services used by drug developers.
This mix matters for long-term analysis. The diagnostics business brings scale, recurring testing volumes, and broad payer and provider relationships. The biopharma services business adds exposure to higher-growth areas tied to new drug pipelines and precision medicine.
The long-term financial picture also shows a business that has moved past the extraordinary COVID testing period. Revenue and profit surged during the pandemic, then normalized sharply, and have since been rebuilding on a more conventional healthcare base. More recently, sales have recovered steadily, while margins have improved from the post-COVID low point but remain below the unusually high 2021 level.
The financial flow over the last several years shows a clear reset rather than a broken model: pandemic-era profits faded quickly, but revenue has climbed back and operating earnings have been recovering. The key question for long-term analysis is whether that recovery can continue at a disciplined pace.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $26.26B | |
| Beta ⓘ | 0.85 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 26.78 | 25.42 |
| P/B Ratio ⓘ | 3.15 | 3.08 |
| FCF Yield ⓘ | 4.40% | 3.12% |
| Dividend Yield ⓘ | 0.89% | 1.85% |
| EBIT / EV ⓘ | 4.65% | 0.56% |
| PEG ⓘ | 1.21 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.80% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 5.43% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -18.50% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -0.60% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | -14.05% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | -17.86% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | -27.25% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.17% | 3.17% |
| ROA (Latest) ⓘ | 5.45% | 2.98% |
| ROIC (5Y Median) ⓘ | 7.38% | 4.56% |
| ROA (5Y Median) ⓘ | 4.77% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 4.55 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.93 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 3.08 | 1.00 |
| Net Debt / Assets ⓘ | 35.74% | 5.06% |
| EBITDA / Interest ⓘ | 9.47 | 9.55 |
| Operating Margin (Latest) ⓘ | 10.14% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 9.54% | 7.33% |
| Debt to Equity (Latest) ⓘ | 78.61% | 26.68% |
| Profit Margin (Latest) ⓘ | 6.99% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $1.16B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +72.62% | +51.61% |
| 12M Return (excl. last month) ⓘ | +12.83% | +19.90% |
| 6M Return ⓘ | +21.61% | +10.10% |
| Price vs. 200-Day MA ⓘ | +16.24% | +6.44% |
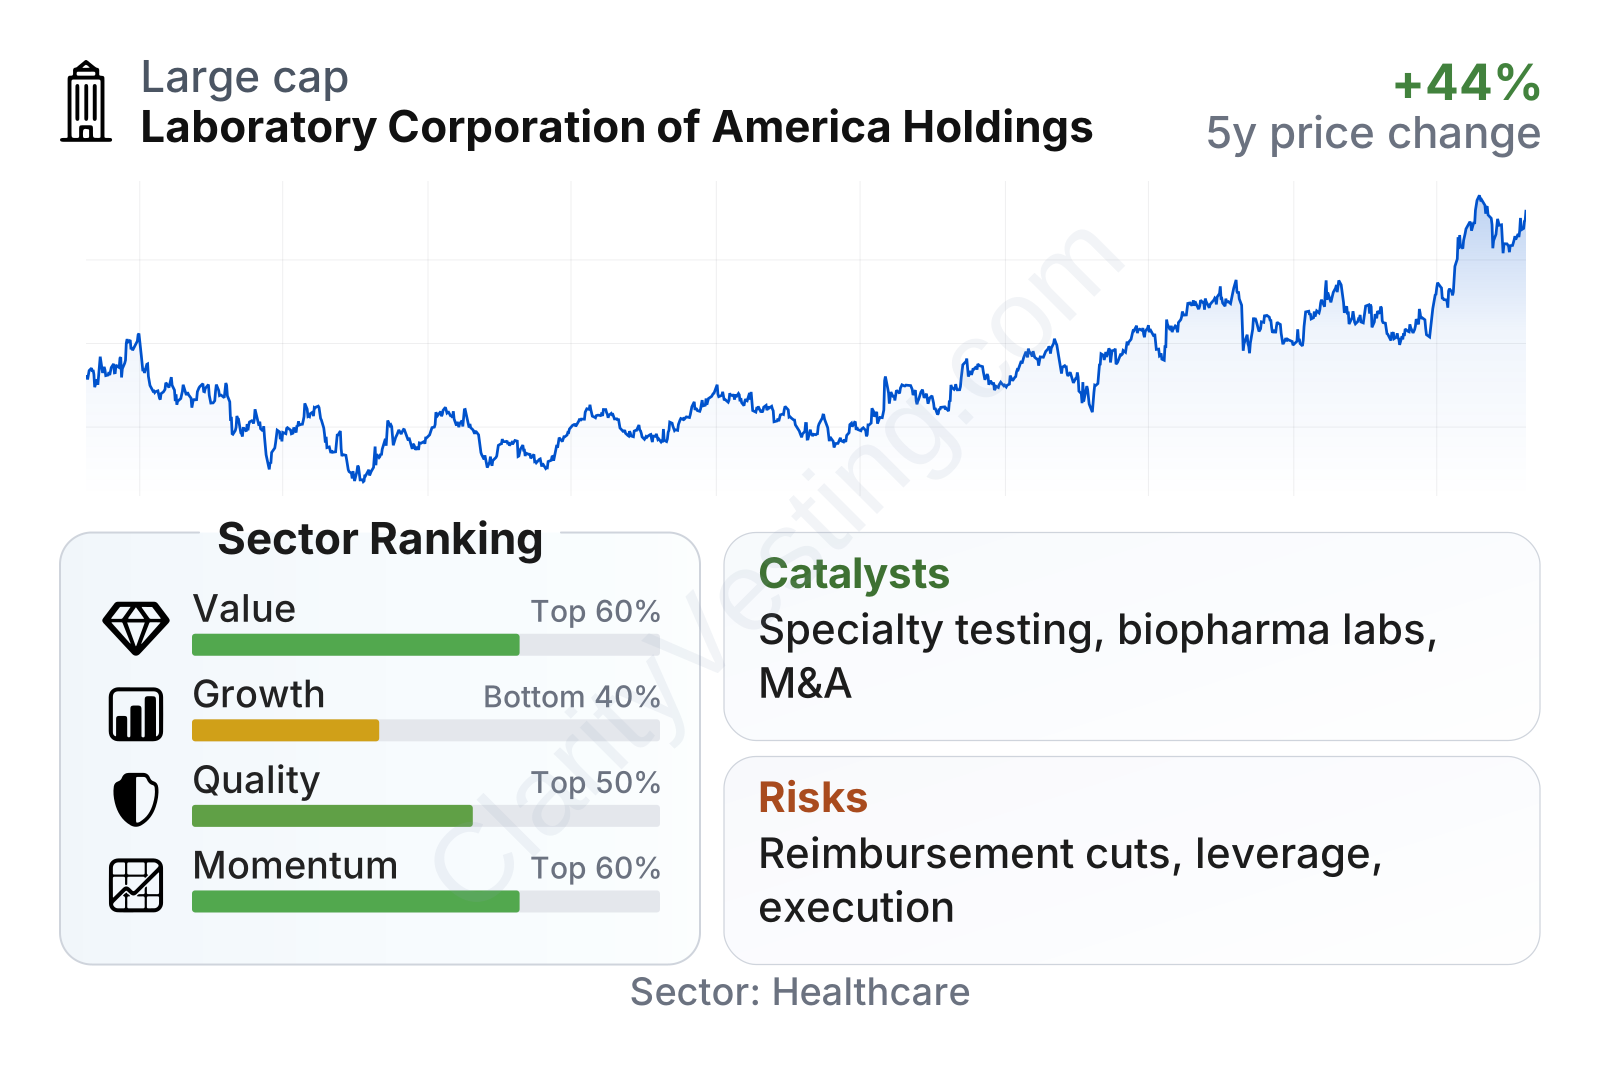
Labcorp is a large healthcare company with relatively low share-price volatility, as reflected by a beta below 1. In the broader healthcare group, its overall profile looks mixed but understandable: valuation measures are around the sector middle, quality metrics are solid, momentum has been favorable, and growth ranks weaker than many peers. Cash generation remains meaningful, with free cash flow above $1 billion on a trailing basis, while profitability and returns on capital are better than typical sector levels.
The main caveat in the current snapshot is leverage. Debt-related measures are notably higher than healthcare medians, which means balance-sheet discipline remains an important part of the investment case.
Growth
Labcorp operates in parts of healthcare that benefit from durable structural demand. An aging population, rising chronic disease prevalence, broader use of personalized medicine, more genetic and oncology testing, and the ongoing need for efficient outpatient care all support long-term demand for diagnostics. On the biopharma side, drug developers continue to need specialized lab partners as trials become more complex and therapies become more targeted.
The company’s strategy is coherent for this environment. Management has been emphasizing higher-value testing, oncology and women’s health, hospital laboratory partnerships, operational efficiency, and expansion in biopharma laboratory services. That approach makes sense because routine testing provides scale and recurring volumes, while specialty testing and drug-development support typically carry better strategic value and stronger barriers to entry.
Recent revenue growth appears more stable than it was during the post-pandemic adjustment. After several quarters of contraction tied largely to the unwind of COVID-related testing, the business returned to positive growth and has recently been expanding at a mid-single-digit pace. That is not especially fast for healthcare, but it does suggest normalization has largely passed and the core business is moving forward again.
Cash generation also deserves attention. Free cash flow fell meaningfully after the pandemic high, then recovered. That pattern supports the view that recent performance is less about one-time demand and more about rebuilding a sustainable earnings base. For a mature healthcare services company, steady cash production is important because it supports debt service, acquisitions, technology investment, and shareholder returns.
A notable catalyst is Labcorp’s positioning in specialty and esoteric testing. Areas such as oncology, companion diagnostics, and advanced diagnostics are becoming more important across healthcare. The company also has room to deepen relationships with hospitals and health systems that want to outsource or optimize lab operations. In biopharma services, a healthier funding environment for biotech and renewed clinical trial activity could provide an additional tailwind.
Recent company communications have also highlighted acquisitions and partnerships aimed at expanding specialty capabilities. These moves are important because they can lift the company beyond being viewed mainly as a high-volume routine testing provider and strengthen its role in more differentiated segments of the market.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


