Stock Analysis · Centrus Energy Corp (LEU)
Overview
Centrus Energy Corp is a U.S.-based nuclear fuel company. Its core business is supplying enriched uranium to nuclear power utilities, while also developing domestic capacity for higher-assay low-enriched uranium, usually called HALEU. That material is important because many next-generation reactors are designed to use it, and the United States has been trying to reduce dependence on Russian nuclear fuel services.
The company operates through two main activities. The larger and more established one is the sale of low-enriched uranium and related uranium supply services to commercial nuclear reactors. The second is technical and manufacturing work tied to advanced enrichment, especially HALEU, much of it supported by U.S. government contracts.
Based on recent company disclosures, Centrus revenue is still primarily tied to its commercial fuel supply segment, with a smaller but strategically important contribution from technical solutions and government-backed enrichment work.
- Low-Enriched Uranium segment: approximately 80% to 90% of revenue in recent periods. This includes enriched uranium product sales, separative work units, and delivery arrangements for utility customers.
- Technical Solutions segment: approximately 10% to 20% of revenue in recent periods. This includes engineering, manufacturing, and contract work for the U.S. government and advanced nuclear fuel initiatives, including HALEU-related activity.
That mix matters because the current business pays the bills, while the smaller activity could become much more meaningful if advanced reactors move from pilot projects to commercial deployment.
The broader revenue picture also shows a business with expanding scale. Annual revenue rose from about $298 million in 2021 to roughly $449 million in 2025. Gross profit stayed relatively stable in a band around $110 million to $118 million, which suggests that growth has come with a heavier cost base rather than a straight-line increase in profitability.
The flow of revenue and costs points to a company that has grown its top line materially over the last several years, but not in a perfectly smooth way. Sales increased sharply in 2024 and 2025, while profit conversion became less impressive than in earlier periods. That pattern fits a company balancing an established trading-and-supply business with a more capital-intensive strategic buildout.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Uranium | |
| Market Cap ⓘ | $2.75B | |
| Beta ⓘ | 1.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 62.75 | 15.44 |
| P/B Ratio ⓘ | 3.11 | 1.73 |
| FCF Yield ⓘ | -5.96% | 8.20% |
| Dividend Yield ⓘ | N/A | 3.59% |
| EBIT / EV ⓘ | 2.49% | 7.46% |
| PEG ⓘ | 2.87 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 14.00% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 1.17% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | -15.22% | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 6.07% |
| Margin Growth (5Y Trend) ⓘ | -23.33% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | -10.51% | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.69% | 11.40% |
| ROA (Latest) ⓘ | 2.03% | 6.06% |
| ROIC (5Y Median) ⓘ | 33.10% | 10.30% |
| ROA (5Y Median) ⓘ | 8.17% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | -10.95 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.46 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | -9.50 | 1.08 |
| Net Debt / Assets ⓘ | -27.30% | 17.29% |
| EBITDA / Interest ⓘ | 4.63 | 9.64 |
| Operating Margin (Latest) ⓘ | 13.32% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 22.26% | 20.39% |
| Debt to Equity (Latest) ⓘ | 139.28% | 54.76% |
| Profit Margin (Latest) ⓘ | 10.23% | 8.82% |
| Free Cash Flow (Latest) ⓘ | -$163.80M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +127.09% | +67.38% |
| 12M Return (excl. last month) ⓘ | -34.16% | +49.19% |
| 6M Return ⓘ | -37.89% | +7.07% |
| Price vs. 200-Day MA ⓘ | -38.85% | +9.56% |
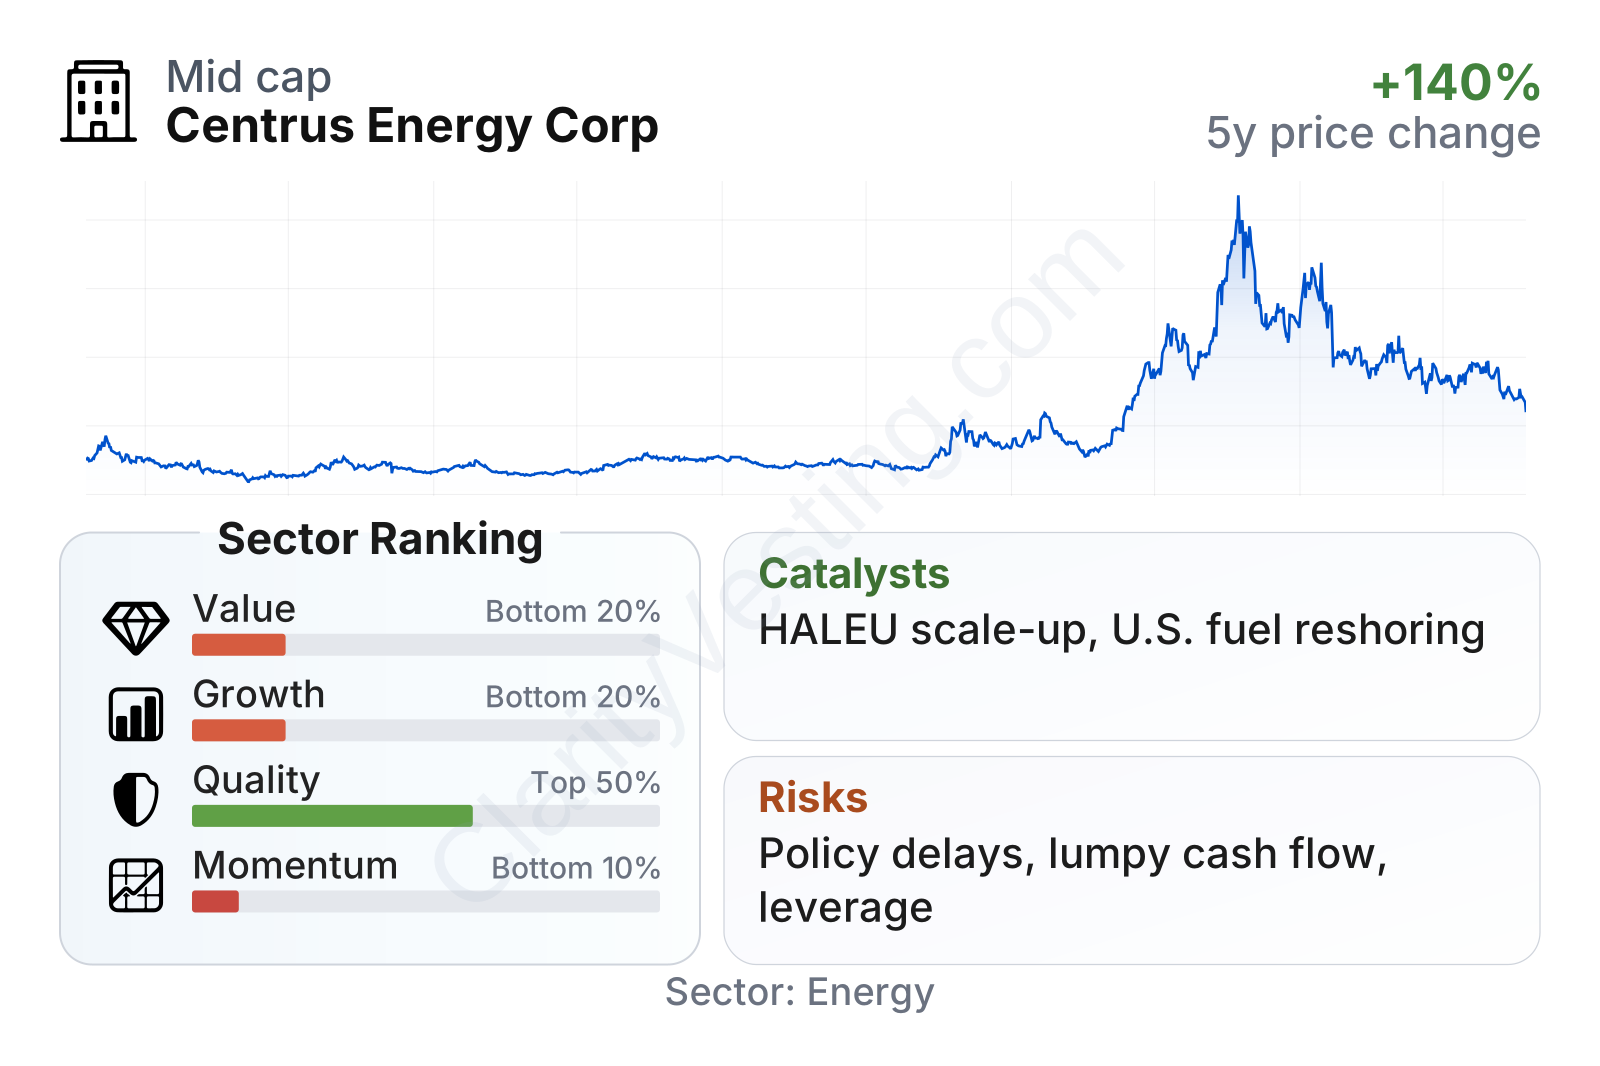
Centrus is a mid-sized company by market value, and its shares have been exceptionally volatile. The stock climbed dramatically during 2025 before pulling back hard in 2026, which shows that market expectations have moved faster than the company’s near-term fundamentals. On the factor table, valuation ranks near the bottom of the sector, growth also sits in the lower tier, quality is more mixed, and recent price momentum is weak despite the strong multiyear share-price run.
The balance sheet has an unusual profile. Net debt metrics remain favorable because the company still holds substantial cash relative to some debt measures, yet debt-to-equity is high at roughly 139%, which means the capital structure deserves close attention. Profit margin is still around 10%, slightly above the sector median, but free cash flow has turned negative, which reduces room for error if expansion spending remains elevated.
Growth
Centrus sits in a part of the energy market with long-term relevance. Nuclear power has regained strategic importance in many countries because it provides constant electricity with very low carbon emissions at the point of generation. In the United States, policy support for domestic nuclear fuel infrastructure has also strengthened because utilities and policymakers want alternatives to Russian conversion and enrichment services.
That industry backdrop is important because Centrus is not just another uranium-linked name. Its main strategic angle is enrichment and advanced fuel supply, especially HALEU. The company has already demonstrated HALEU production at its Piketon, Ohio facility under U.S. Department of Energy programs, which gives it a real operational foothold in a market that currently has very limited Western supply.
Its strategy makes industrial sense. The legacy low-enriched uranium business provides customer relationships and commercial know-how, while the advanced fuel business positions the company for a potentially large future market tied to small modular reactors and other next-generation reactor designs. If those reactor programs progress, a domestic HALEU supplier could have an unusually strong position.
Revenue growth has been positive recently, including a mid-teens year-over-year increase in the latest period, but the pattern has been uneven. Quarterly growth has swung sharply between strong gains and declines, reflecting contract timing and the lumpy nature of this business. That makes headline growth less dependable than at a typical industrial company with recurring volume.
Free cash flow is the main near-term weak point in the growth profile. After being positive in earlier periods, it moved clearly negative over the trailing twelve months. That does not automatically undermine the long-term thesis, because strategic capacity buildout can pressure cash generation before future revenue arrives, but it does mean growth is currently consuming capital rather than producing it.
The most important catalyst is the U.S. push to rebuild domestic nuclear fuel capability. Public announcements from the company and federal agencies have highlighted additional contract awards and funding support connected to HALEU production and enrichment capacity. Another meaningful opportunity is the growing list of advanced reactor developers that will need dependable fuel sources if their projects move ahead. In short, Centrus has exposure to a niche that could become much more important over the next decade if policy support turns into sustained commercial demand.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


