Stock Analysis · Laureate Education Inc (LAUR)
Overview
Laureate Education is a higher-education company focused on degree-granting universities in Latin America. After years of selling non-core assets, the group is now much more concentrated, with its business centered mainly on Mexico and Peru. It serves students through campus-based and blended learning models, offering undergraduate and graduate programs in fields such as health sciences, engineering, business, law, and education.
The company’s revenue mainly comes from tuition and education-related fees paid by students. Based on recent annual disclosures, the business is highly concentrated in two operating segments.
- Peru operations: approximately 55% to 60% of revenue. This includes Universidad Peruana de Ciencias Aplicadas, Universidad Privada del Norte, Cibertec, and other education brands focused on university and technical education.
- Mexico operations: approximately 40% to 45% of revenue. This is primarily Universidad del Valle de México and Universidad Tecnológica de México, which offer undergraduate and graduate programs across multiple campuses and formats.
- Other revenue: a small share from items such as ancillary academic services and other education-related fees, with no major third segment currently matching the scale of Peru or Mexico.
That revenue mix matters because it makes Laureate easier to understand than it was several years ago: this is now a focused Latin American education operator, not a sprawling global network. The business model is relatively straightforward. Students enroll, pay tuition over multi-year programs, and the company uses its physical campuses, faculty, and brand recognition to generate recurring academic revenue. Over the last several years, revenue has expanded while operating profitability has improved materially, suggesting that the simplified structure has translated into better execution.
The long-term pattern shows a healthier earnings structure than in 2021. Revenue has risen steadily, gross profit has expanded, and operating income moved from a loss to a strong positive level. Selling and administrative costs also look more controlled relative to revenue, which helps explain why net income has improved faster than sales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 04, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Education & Training Services | |
| Market Cap ⓘ | $5.32B | |
| Beta ⓘ | 0.44 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.48 | 18.17 |
| P/B Ratio ⓘ | 4.79 | 1.27 |
| FCF Yield ⓘ | 5.39% | 12.39% |
| Dividend Yield ⓘ | N/A | 2.83% |
| EBIT / EV ⓘ | 8.09% | 6.38% |
| PEG ⓘ | 1.02 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 17.50% | 3.80% |
| RPS Growth (5Y CAGR) ⓘ | 18.89% | 6.20% |
| EPS Growth (5Y CAGR) ⓘ | 19.94% | -14.56% |
| BVPS Growth (5Y CAGR) ⓘ | 7.34% | 3.26% |
| Margin Growth (5Y Trend) ⓘ | 32.59% | -0.25% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.65% |
| DPS Growth (5Y CAGR) ⓘ | -85.67% | 6.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.62% | 12.58% |
| ROA (Latest) ⓘ | 14.17% | 6.32% |
| ROIC (5Y Median) ⓘ | 11.92% | 10.36% |
| ROA (5Y Median) ⓘ | 5.36% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.26 | 1.91 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.34 | 2.32 |
| Net Debt / EBITDA (Latest) ⓘ | 0.99 | 1.36 |
| Net Debt / Assets ⓘ | 23.62% | 21.25% |
| EBITDA / Interest ⓘ | 46.45 | 9.61 |
| Operating Margin (Latest) ⓘ | 24.89% | 8.91% |
| Operating Margin (5Y Median) ⓘ | 21.11% | 9.53% |
| Debt to Equity (Latest) ⓘ | 64.31% | 71.66% |
| Profit Margin (Latest) ⓘ | 17.57% | 5.39% |
| Free Cash Flow (Latest) ⓘ | $286.75M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +194.10% | +15.25% |
| 12M Return (excl. last month) ⓘ | +29.37% | +2.49% |
| 6M Return ⓘ | +15.08% | +2.26% |
| Price vs. 200-Day MA ⓘ | +9.87% | +0.43% |
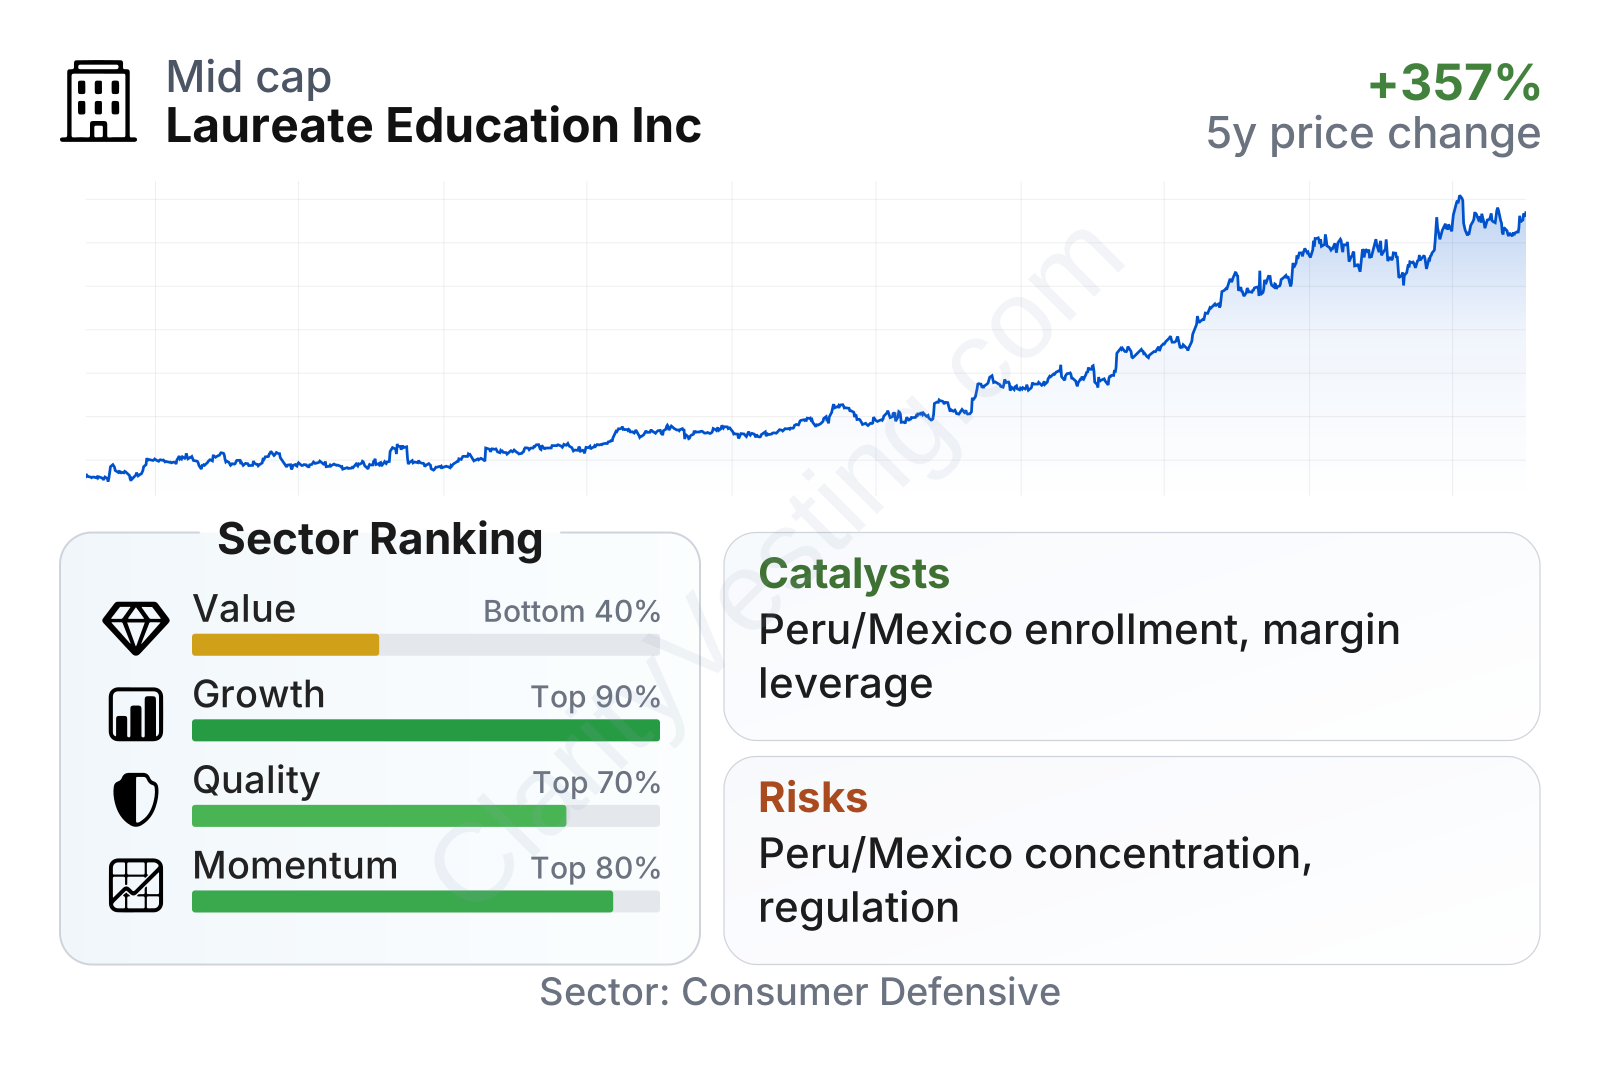
Laureate is now a mid-sized company with relatively low share-price volatility, as reflected by a beta well below 1. In the factor breakdown, growth stands out the most, with revenue, earnings per share, and margin trends all ranking well above the sector median. Quality is also solid: returns on capital and assets are strong, leverage is manageable, and interest coverage is exceptionally high. Valuation looks more mixed. The earnings multiple is close to the sector median, but the price-to-book ratio is elevated and free cash flow yield is below the sector median, which suggests the market is already recognizing much of the operational improvement.
Growth
Higher education in Latin America remains a structurally attractive area over the long run. Demand is supported by population growth in key age groups, low university attainment in many markets compared with developed economies, and employer demand for formal credentials in healthcare, engineering, business, and technology-related fields. Private education providers can benefit when public systems are overcrowded or underfunded, especially if they offer recognizable brands, broad campus coverage, and flexible schedules for working adults.
Laureate’s current strategy appears aligned with those industry dynamics. The company has become more focused on institutions where it already has scale, strong brand awareness, and local operating experience. That matters in education because campus utilization, student retention, pricing discipline, and academic reputation can all improve when management concentrates resources on fewer platforms instead of spreading capital across many countries.
Revenue growth has not been perfectly smooth, but the broader picture is favorable. After a strong run in 2022 and 2023, growth slowed in parts of 2024, briefly turned negative in early 2025, and then reaccelerated sharply. Most recently, year-over-year revenue growth has been running in the mid-to-high teens, far above the sector median, which suggests demand and pricing have remained healthy.
Cash generation has also improved meaningfully. Free cash flow moved from negative territory in 2022 to a solid positive level and has kept climbing, reaching more than $250 million on a trailing basis. For a school operator, this is important because accounting earnings can look strong while cash conversion lags; here, the trend points to real underlying financial progress.
A major catalyst for future expansion is operating leverage. Education businesses often carry a meaningful fixed-cost base, so additional students and tuition increases can lift profitability faster than revenue once campuses are well utilized. Laureate’s margin trend over the last five years supports that idea. Another potential catalyst is continued enrollment growth in Peru and Mexico, where the company already has strong institutional positions and established brands. New program launches in high-demand disciplines and broader digital or hybrid offerings could also widen the addressable market without requiring the same level of physical expansion as a purely campus-driven model.
Recent company communications have also emphasized enrollment momentum, tuition discipline, and shareholder returns, signaling confidence in the underlying business. While capital returns do not create operating growth on their own, they can indicate that the company sees its cash generation as durable rather than temporary.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


