Stock Analysis · Kenvue Inc (KVUE)
Overview
Kenvue is a consumer health company focused on everyday products that people use repeatedly rather than occasionally. It was separated from Johnson & Johnson in 2023 and owns a portfolio of widely known brands across pain relief, skin care, baby care, oral care, and smoking cessation. Its business is built around products that tend to be purchased in both strong and weak economic environments, which gives the company a relatively defensive profile compared with more cyclical sectors.
Kenvue reports revenue through three main segments.
- Self Care: about 37% of 2025 sales. This segment includes over-the-counter medicines and health products such as Tylenol, Motrin, Zyrtec, Benadryl, Nicorette, and digestive health brands.
- Skin Health and Beauty: about 31% of 2025 sales. This includes brands such as Neutrogena, Aveeno, Dr.Ci:Labo, and Lubriderm.
- Essential Health: about 32% of 2025 sales. This covers products used daily, including Listerine, Johnson’s baby products, Band-Aid, and women’s health lines.
The revenue mix is fairly balanced, which reduces dependence on any single category. Geographically, Kenvue is also diversified, with a meaningful presence in North America, Europe, Asia-Pacific, Latin America, and other international markets. That broad footprint matters because it allows the company to offset weakness in one region with steadier demand in others.
At a high level, Kenvue’s business model converts a large portion of sales into gross profit, but operating costs remain substantial because consumer health products require heavy spending on advertising, distribution, and retailer support. Over the last several years, sales have stayed around the same broad range, while profitability has been more volatile due to separation costs, brand investment, and legal and restructuring expenses.
The operating picture shows a business with stable revenue and strong gross profit generation, but one where selling and administrative expenses absorb a large share of that advantage. Net income has been less steady than revenue, which helps explain why the market has treated Kenvue more as a stability business than a growth company.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Household & Personal Products | |
| Market Cap ⓘ | $34.34B | |
| Beta ⓘ | 0.43 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 21.04 | 18.16 |
| P/B Ratio ⓘ | 3.26 | 1.27 |
| FCF Yield ⓘ | 6.16% | 12.39% |
| Dividend Yield ⓘ | 4.66% | 2.83% |
| EBIT / EV ⓘ | 6.27% | 6.45% |
| PEG ⓘ | 1.40 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.00% | 3.80% |
| RPS Growth (5Y CAGR) ⓘ | -0.34% | 6.20% |
| EPS Growth (5Y CAGR) ⓘ | -15.39% | -14.64% |
| BVPS Growth (5Y CAGR) ⓘ | -15.16% | 3.26% |
| Margin Growth (5Y Trend) ⓘ | -3.71% | -0.25% |
| FCF Growth (5Y CAGR) ⓘ | 157.78% | 4.65% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 10.07% | 12.58% |
| ROA (Latest) ⓘ | 6.14% | 6.35% |
| ROIC (5Y Median) ⓘ | 9.37% | 10.36% |
| ROA (5Y Median) ⓘ | 6.03% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 2.84 | 1.91 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.96 | 2.32 |
| Net Debt / EBITDA (Latest) ⓘ | 2.33 | 1.36 |
| Net Debt / Assets ⓘ | 27.57% | 21.25% |
| EBITDA / Interest ⓘ | 8.42 | 9.61 |
| Operating Margin (Latest) ⓘ | 16.87% | 8.96% |
| Operating Margin (5Y Median) ⓘ | 16.50% | 9.53% |
| Debt to Equity (Latest) ⓘ | 80.36% | 71.66% |
| Profit Margin (Latest) ⓘ | 10.76% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $2.12B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +2.23% | +15.25% |
| 12M Return (excl. last month) ⓘ | -2.99% | +2.63% |
| 6M Return ⓘ | +7.58% | +2.43% |
| Price vs. 200-Day MA ⓘ | +2.23% | +0.43% |
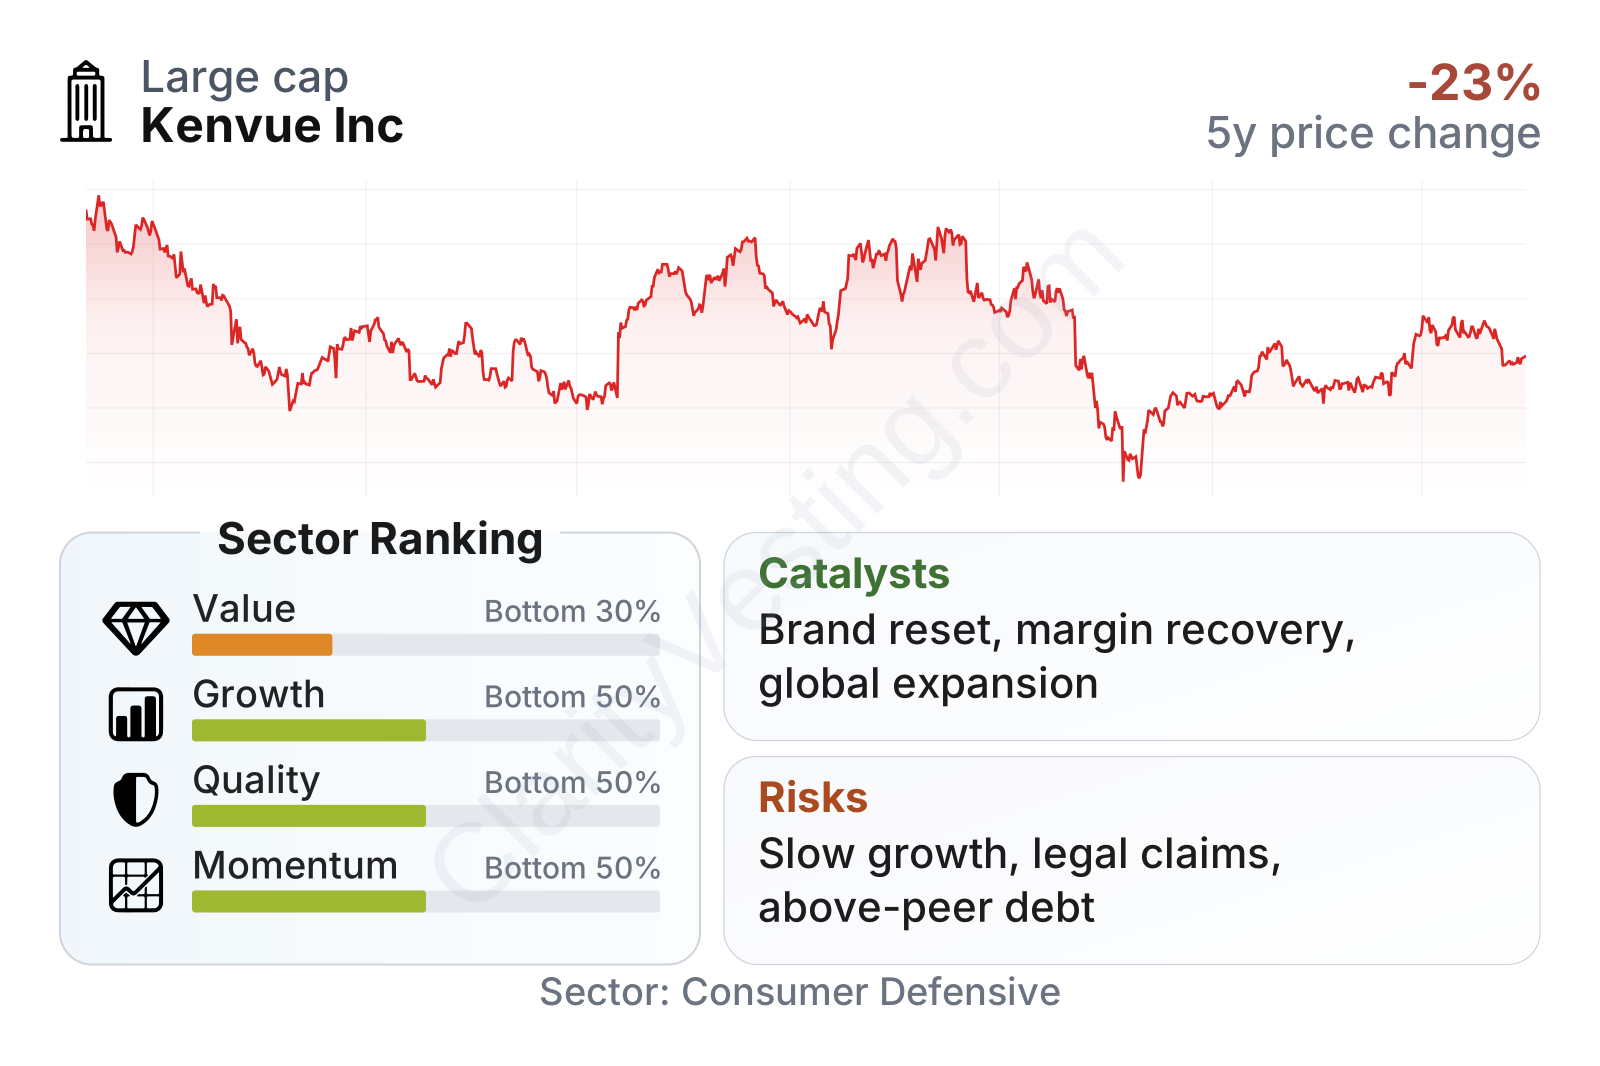
Kenvue currently stands out more for stability than for cheapness or rapid expansion. It is a large company with a low beta, which suggests lower share-price sensitivity than the broader market. Profitability remains solid, with margins above many sector peers, but the overall factor profile is less impressive in growth, momentum, and balance-sheet strength. The dividend yield is noticeably above the sector median, while valuation measures such as price-to-earnings and price-to-book sit above typical consumer defensive peers.
Growth
Kenvue operates in consumer health, a sector that benefits from long-term support factors including aging populations, rising interest in self-care, brand loyalty in health-related categories, and the global shift toward treating minor conditions at home. These are attractive characteristics for durability, although they do not automatically translate into fast revenue growth. The sector is growing, but it is usually a moderate-growth market rather than a high-growth one.
The company’s strategy is centered on a few sensible priorities: strengthening major brands, improving execution with retailers, expanding internationally, and using product innovation to defend shelf space and pricing. For a business like Kenvue, future progress depends less on breakthrough technology and more on consistent brand management, better product mix, and operational discipline. That approach fits the type of categories it serves.
Recent revenue trends suggest the company has moved out of a softer period. Growth turned negative through much of 2025, then returned to low-single-digit positive territory in late 2025 and remained positive into 2026. That does not point to acceleration on a dramatic scale, but it does suggest that the business has regained some footing after a weaker stretch.
Cash generation remains an important part of the Kenvue case. Free cash flow declined meaningfully from 2023 to 2025 before showing recovery in 2026. Even after that dip, the business still produces substantial cash, which supports dividends, debt service, and brand investment. For a mature consumer health company, that cash profile is one of the main practical growth enablers because it provides room to fund marketing and product refreshes without depending heavily on outside financing.
One of the more significant recent developments is the company’s multi-year brand and portfolio reset under a newer leadership structure, including efforts to improve execution in Skin Health and Beauty, where several brands have underperformed relative to their potential. If Kenvue can stabilize that segment while maintaining resilience in Self Care and Essential Health, the company has a visible path to better organic growth than what the recent multi-year record suggests.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


