Stock Analysis · K92 Mining Inc (KNTNF)
Overview
K92 Mining is a gold producer focused on the Kainantu mine in Papua New Guinea. The company explores, develops, and operates underground deposits at Kainantu, where it produces a concentrate containing gold, copper, and silver. In simple terms, K92 earns money by mining ore, processing it on site, and selling the resulting concentrate to buyers that pay based on the contained metals.
The business is highly concentrated around one operating complex, which makes it easier to understand than many larger miners. That simplicity also means performance depends heavily on how well Kainantu operates and expands. Recent company reporting and technical updates have centered on increasing throughput, lifting annual production, and extending mine life through continued drilling around the Kora, Judd, and Arakompa areas.
Revenue mainly comes from payable metals in concentrate sales. Exact splits can move from quarter to quarter with grade, recovery, and metal prices, but gold is clearly the dominant source, followed by copper and then silver.
- Gold: approximately 75% to 85% of revenue. This is the core economic driver and reflects both production volumes and the high value of gold per ounce.
- Copper: approximately 10% to 20% of revenue. Copper is an important by-product credit and helps lower effective cash costs per gold ounce.
- Silver: generally less than 5% of revenue. Silver adds extra payable value but is not a main driver of the business.
The financial flow has improved sharply in the last two years. Revenue has scaled much faster than operating costs, interest expense is very low, and a much larger share of sales is now reaching operating profit and net income. That operating leverage is one of the most important features of the company at this stage.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $4.72B | |
| Beta ⓘ | 1.30 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.06 | 16.92 |
| P/B Ratio ⓘ | 4.82 | 1.66 |
| FCF Yield ⓘ | 3.83% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | 11.03% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 113.00% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 37.23% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 33.06% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 34.01% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 32.01% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 47.96% | 9.59% |
| ROA (Latest) ⓘ | 36.24% | 4.92% |
| ROIC (5Y Median) ⓘ | 14.28% | 7.91% |
| ROA (5Y Median) ⓘ | 11.15% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.93 |
| Net Debt / Assets ⓘ | N/A | 13.69% |
| EBITDA / Interest ⓘ | 166.60 | 12.38 |
| Operating Margin (Latest) ⓘ | 66.60% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 34.12% | 11.82% |
| Debt to Equity (Latest) ⓘ | N/A | 40.30% |
| Profit Margin (Latest) ⓘ | 45.48% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $180.68M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +344.32% | +73.47% |
| 12M Return (excl. last month) ⓘ | +79.51% | +27.59% |
| 6M Return ⓘ | +1.16% | -4.02% |
| Price vs. 200-Day MA ⓘ | +2.07% | -0.65% |
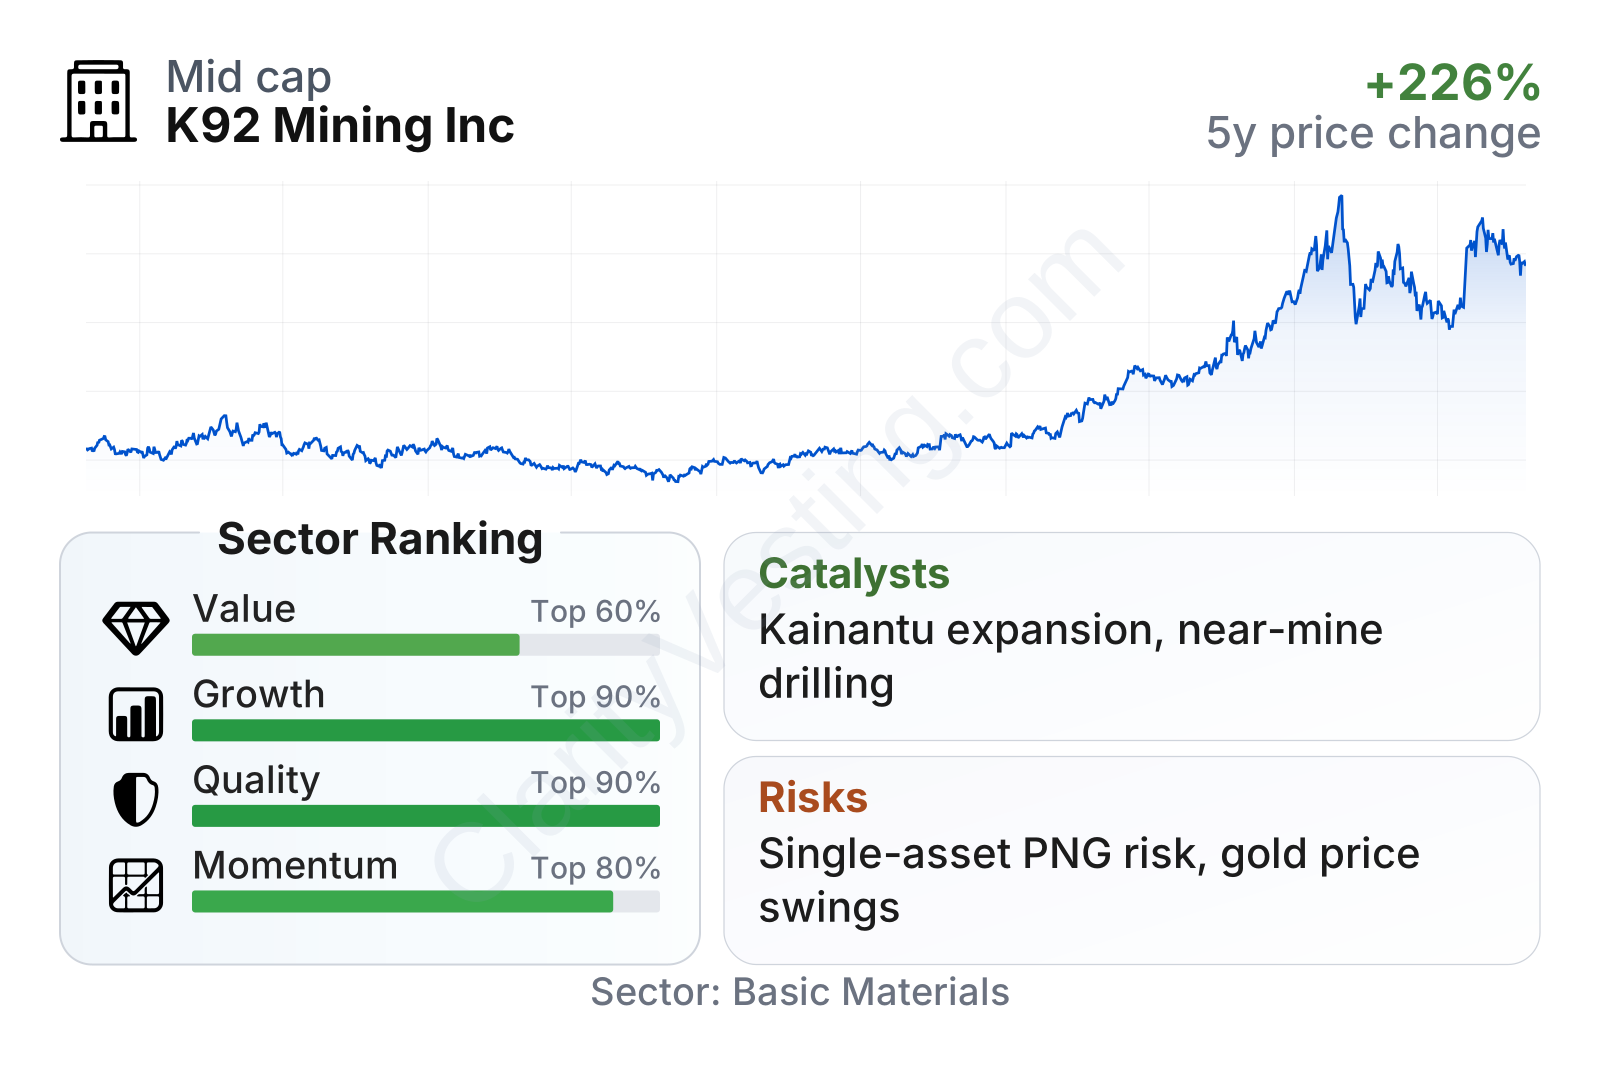
K92 Mining sits in the mid-sized range by market value within the gold space, with a share price that has been strong over the last three years but still shows meaningful volatility. On the fundamental side, the profile stands out more for quality and growth than for traditional asset cheapness. Profitability metrics are far above the sector median, growth ranks near the top of the peer group, and balance sheet pressure appears limited. Valuation looks mixed: the earnings multiple is below the sector median, but the price-to-book ratio is much higher, which suggests the market is paying up for the quality of the asset base and recent execution.
Growth
Gold mining remains a relevant long-term sector, but it is not a growth industry in the same way as software or semiconductors. What matters more is whether an individual miner can increase output, control costs, and grow reserves faster than peers. K92 Mining has done exactly that in recent years. The company operates in gold, which benefits from demand tied to jewelry, central bank purchases, investment demand, and a role as a store of value during periods of inflation or geopolitical stress. The added copper exposure also gives it some leverage to electrification and power infrastructure trends.
K92’s strategy is straightforward and sensible: expand a high-grade underground operation that is already generating strong margins. Instead of relying on multiple scattered assets, the company is trying to build scale at Kainantu through phased plant expansion, underground development, and exploration near existing infrastructure. That approach can be attractive because successful growth at an existing mine is often less risky and less capital intensive than building an entirely new operation from scratch.
The recent growth record has been unusually strong for a miner. Revenue growth has been volatile from quarter to quarter, which is normal in mining, but the broader direction is clearly upward. The latest year-over-year increase is far ahead of the sector median, and longer-term growth in revenue per share and book value per share also ranks among the strongest in its peer group. That suggests the company is not only benefiting from metal prices, but also from real operational expansion.
Cash generation has also improved meaningfully. Free cash flow was negative during the heavier investment phase, then turned strongly positive as expanded production and margins started to outweigh capital spending. That transition matters because it gives the company more internal funding capacity for development, exploration, and balance sheet flexibility.
A key catalyst is the Kainantu expansion pathway. Company disclosures have pointed to increasing processing capacity and lifting annual production over time, with further upside if exploration continues to convert nearby targets into mineable resources. High-grade discoveries around the existing operation are especially important because they can support longer mine life and stronger economics without requiring a completely new district buildout. Strong gold prices have also amplified the benefit of this growth by widening margins.
Recent public updates have continued to support the idea of a larger Kainantu over time, with progress on expansion work and ongoing drilling success across multiple targets near the mine. For a long-term reader, the main opportunity is easy to frame: if K92 can continue growing tonnage while maintaining relatively strong grades and recoveries, the earnings base could scale faster than many peers.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


