Stock Analysis · Kingspan Group PLC (KGSPY)
Overview
Kingspan Group PLC is an Ireland-based building products company focused on energy efficiency, insulation, and building envelope solutions. In simple terms, it makes products that help buildings use less energy, control temperature better, and meet stricter environmental standards. Its products are used in industrial buildings, warehouses, data centers, commercial properties, and increasingly in renovation projects where owners want to improve older buildings.
The business is organized into several divisions, and the largest source of revenue comes from insulated panels, which are factory-made building panels used for walls and roofs. These products are central to Kingspan’s position because they combine insulation, weather protection, and speed of installation. Based on recent annual reporting, the revenue mix is approximately:
- Insulated Panels: about 65% — insulated wall and roof panels for industrial, logistics, commercial, and specialized buildings.
- Insulation: about 17% — rigid insulation boards and related products used in walls, floors, roofs, and renovation work.
- Light + Air: about 10% — daylighting, smoke management, and ventilation systems.
- Water + Energy: about 5% — water storage, wastewater, and energy-related solutions.
- Data + Flooring and other activities: about 3% — raised access floors and data-center-related solutions, plus smaller operations.
Geographically, Kingspan is broadly international, with Europe remaining the core market and North America also an important contributor. That geographic spread helps reduce dependence on one single construction market, although the company is still tied to the broader building cycle.
A notable financial pattern over the past several years is that revenue has expanded from roughly $6.5 billion in 2021 to about $9.2 billion in 2025, while gross profit has also moved higher. Net income has grown more slowly than sales, which suggests that volume growth, acquisitions, and product mix have supported expansion, but margin gains have been less dramatic than topline growth.
The long-term picture is one of steady scaling: sales and gross profit have both increased meaningfully since 2021, even though operating costs have also risen. That points to a company that has grown successfully, but one that still needs to protect margins as it gets larger.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $19.07B | |
| Beta ⓘ | 1.27 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.18 | 22.29 |
| P/B Ratio ⓘ | 4.33 | 1.98 |
| FCF Yield ⓘ | 5.42% | 6.26% |
| Dividend Yield ⓘ | 0.61% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | 1.47 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 9.12% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -3.60% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 10.00% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -1.73% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 29.68% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 6.82% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 22.45% | 10.75% |
| ROA (Latest) ⓘ | 13.14% | 5.41% |
| ROIC (5Y Median) ⓘ | 12.53% | 9.37% |
| ROA (5Y Median) ⓘ | 8.17% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.12 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.11 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.84 | 1.39 |
| Net Debt / Assets ⓘ | 19.16% | 19.27% |
| EBITDA / Interest ⓘ | 21.42 | 9.58 |
| Operating Margin (Latest) ⓘ | 10.08% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 10.45% | 10.30% |
| Debt to Equity (Latest) ⓘ | 56.41% | 64.82% |
| Profit Margin (Latest) ⓘ | 7.16% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $1.03B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +67.28% | +67.77% |
| 12M Return (excl. last month) ⓘ | +47.27% | +12.05% |
| 6M Return ⓘ | +14.76% | 0.00% |
| Price vs. 200-Day MA ⓘ | +11.17% | +0.67% |
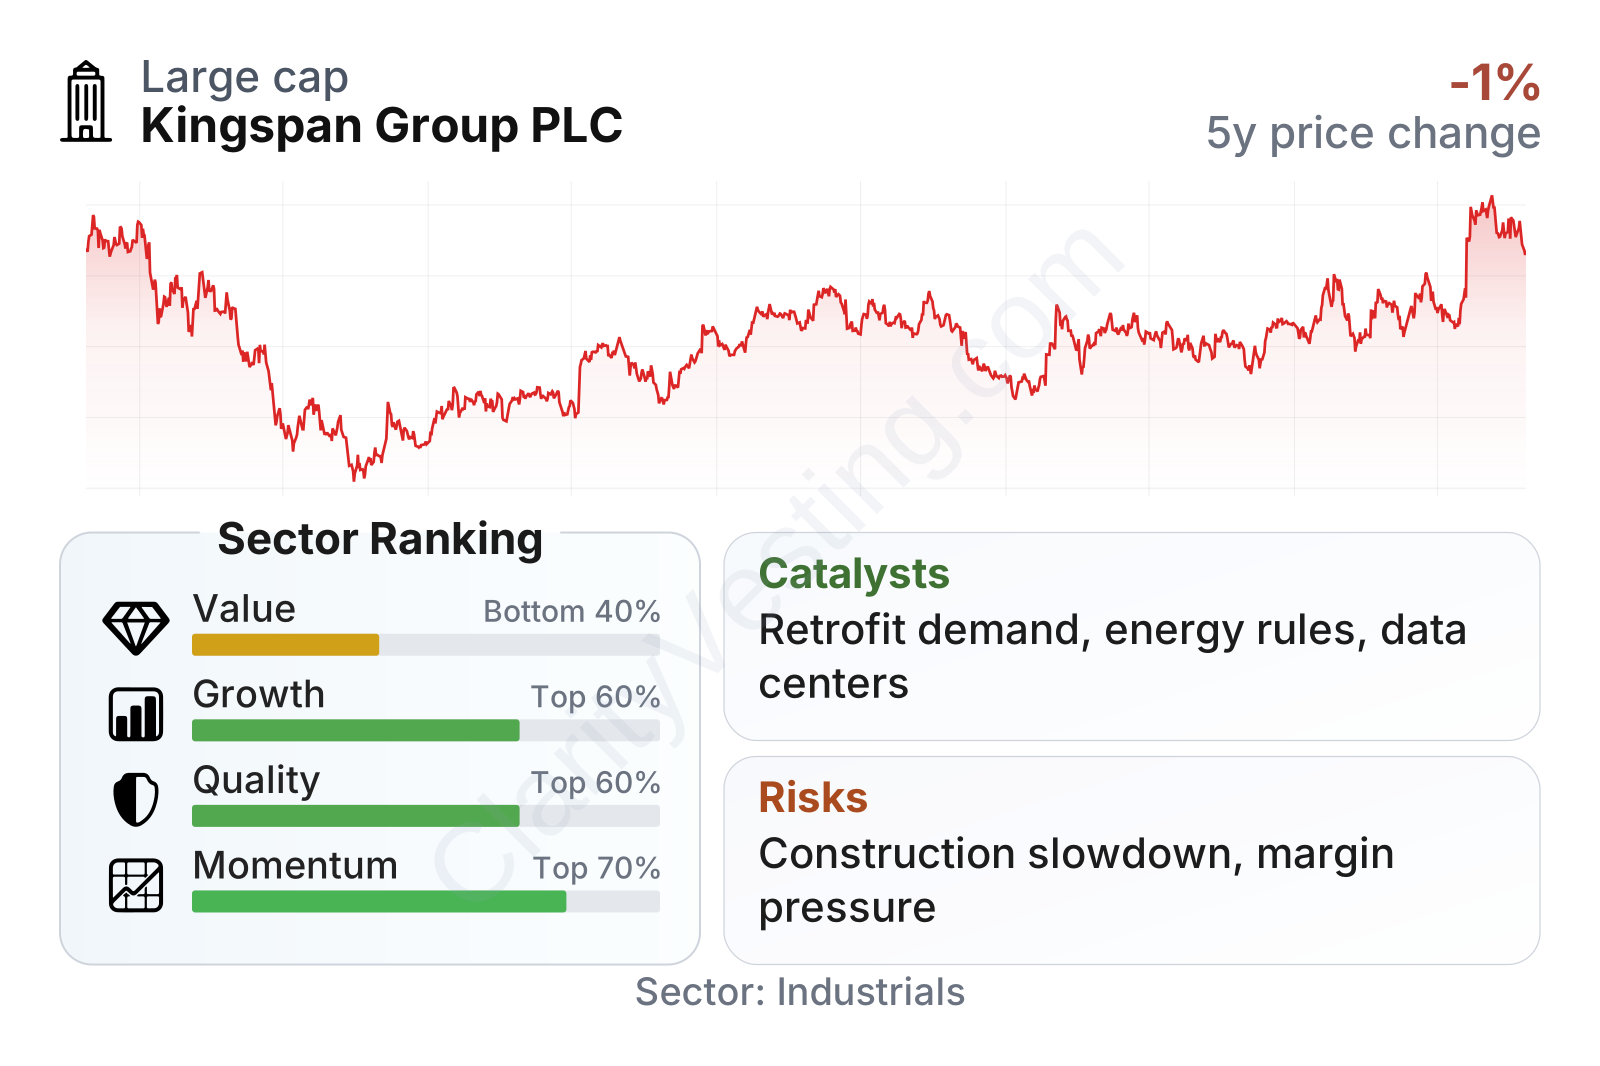
Kingspan is a large building-products company with a market value around $20 billion, so it is well beyond small-cap territory. The table shows a mixed but generally solid profile. Quality metrics stand out: returns on capital and assets are clearly above sector medians, leverage is moderate, and interest coverage is strong. Growth is respectable rather than exceptional in the latest year, but longer-term free cash flow and book value growth look stronger than many industry peers. The weaker area is valuation, where the shares trade above typical sector multiples while offering a relatively low dividend yield.
The stock-price history also shows that Kingspan is not a low-volatility name. It dropped sharply in 2022, then recovered strongly and has recently traded with better momentum than much of the sector. That recovery signals renewed confidence in the business, but it also means part of the market is already assigning a premium to its quality and growth profile.
Growth
Kingspan operates in a part of the construction market that has durable structural support. Energy efficiency rules are getting stricter, building owners are under pressure to reduce heating and cooling costs, and renovation of older buildings remains a major opportunity in Europe and other developed markets. These trends matter because Kingspan’s products are often not optional upgrades; they can be tied directly to compliance, operating savings, and sustainability targets.
The strategy also makes sense for future expansion. Kingspan has spent years building scale in insulated panels and high-performance insulation, while also broadening into adjacent systems such as ventilation, daylighting, water management, and data-center-related solutions. That gives it more ways to grow than a basic commodity building-material supplier. It is also active in manufacturing expansion and bolt-on acquisitions, which can increase local market reach and product breadth.
Recent financial trends support the idea of continued growth, though not in a straight line. Revenue growth has been positive, and over a five-year period revenue per share has compounded ahead of the sector median. Free cash flow growth has been particularly strong over that same period, which is important because it suggests the business is converting expansion into real cash generation rather than relying only on accounting profits.
A meaningful catalyst is the global push toward better-insulated industrial and commercial buildings, including logistics facilities, advanced manufacturing plants, and data centers. These building types often prioritize speed of construction, thermal performance, and lifecycle efficiency, which aligns well with Kingspan’s product offering. Another potential tailwind is retrofit demand: older building stock across Europe offers a long runway for insulation upgrades as governments and property owners pursue decarbonization goals.
Recent company updates have also highlighted continued investment in capacity, technology, and product development, especially around lower-carbon building materials and higher-performance envelope systems. That does not guarantee faster growth every year, but it supports the case that Kingspan is positioned where regulation and customer demand are moving.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


