Stock Analysis · Kingspan Group plc (KGSPF)
Overview
Kingspan Group plc is an Ireland-based building products company focused on insulation, energy efficiency, and building envelope solutions. In simple terms, it makes products that help buildings use less energy, manage water better, and meet stricter construction standards. Its offerings are used in industrial buildings, warehouses, data centers, commercial sites, and increasingly in more specialized applications where thermal performance and speed of construction matter.
The business is organized into several operating segments, with insulated panels and insulation products forming the core of the company. Based on recent annual reporting, revenue is mainly generated from the following activities:
- Insulated Panels: approximately 45% to 50% of revenue. These are factory-made roof and wall systems used in industrial, logistics, commercial, and increasingly technology-related facilities.
- Insulation: approximately 20% to 25% of revenue. This includes rigid insulation boards and related thermal products used in walls, floors, roofs, and building retrofits.
- Light + Air: approximately 10% to 15% of revenue. This division provides daylighting, ventilation, smoke management, and related systems for commercial and industrial buildings.
- Water + Energy: approximately 10% to 15% of revenue. This unit includes water storage, wastewater, rainwater harvesting, and some energy-related solutions.
- Data + Flooring and other activities: a smaller share, generally in the low single-digit to high single-digit range depending on the period. These activities include data center flooring and specialist building solutions.
Kingspan’s business mix matters because the company is tied to long-term construction themes rather than only to short-cycle building materials demand. Tightening energy-efficiency rules, lower-carbon building design, and renovation of older buildings all support demand for products that improve insulation and operational performance.
Over the last several years, revenue has expanded from about $6.5 billion in 2021 to just over $9.1 billion in 2025, while operating income and net income have also moved higher. Gross profit has grown faster than revenue over that span, suggesting the business has preserved pricing power and mix quality reasonably well even while operating expenses and interest costs increased.
The long-term picture is one of a business that has become larger and more diversified, with earnings still converting into solid profitability despite cost inflation, acquisition activity, and cyclical construction conditions.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Building Products & Equipment | |
| Market Cap ⓘ | $20.05B | |
| Beta ⓘ | 1.27 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.43 | 22.29 |
| P/B Ratio ⓘ | 4.51 | 1.98 |
| FCF Yield ⓘ | 5.16% | 6.26% |
| Dividend Yield ⓘ | 0.51% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | 1.50 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 9.11% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -24.14% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 10.01% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -1.34% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 30.98% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 7.89% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 22.38% | 10.75% |
| ROA (Latest) ⓘ | 13.11% | 5.41% |
| ROIC (5Y Median) ⓘ | 12.53% | 9.37% |
| ROA (5Y Median) ⓘ | 8.17% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.12 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.11 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.84 | 1.39 |
| Net Debt / Assets ⓘ | 19.16% | 19.27% |
| EBITDA / Interest ⓘ | 21.51 | 9.58 |
| Operating Margin (Latest) ⓘ | 10.08% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 10.45% | 10.30% |
| Debt to Equity (Latest) ⓘ | 56.41% | 64.82% |
| Profit Margin (Latest) ⓘ | 7.16% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $1.03B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +51.76% | +67.77% |
| 12M Return (excl. last month) ⓘ | +49.36% | +12.05% |
| 6M Return ⓘ | +16.13% | 0.00% |
| Price vs. 200-Day MA ⓘ | +24.45% | +0.67% |
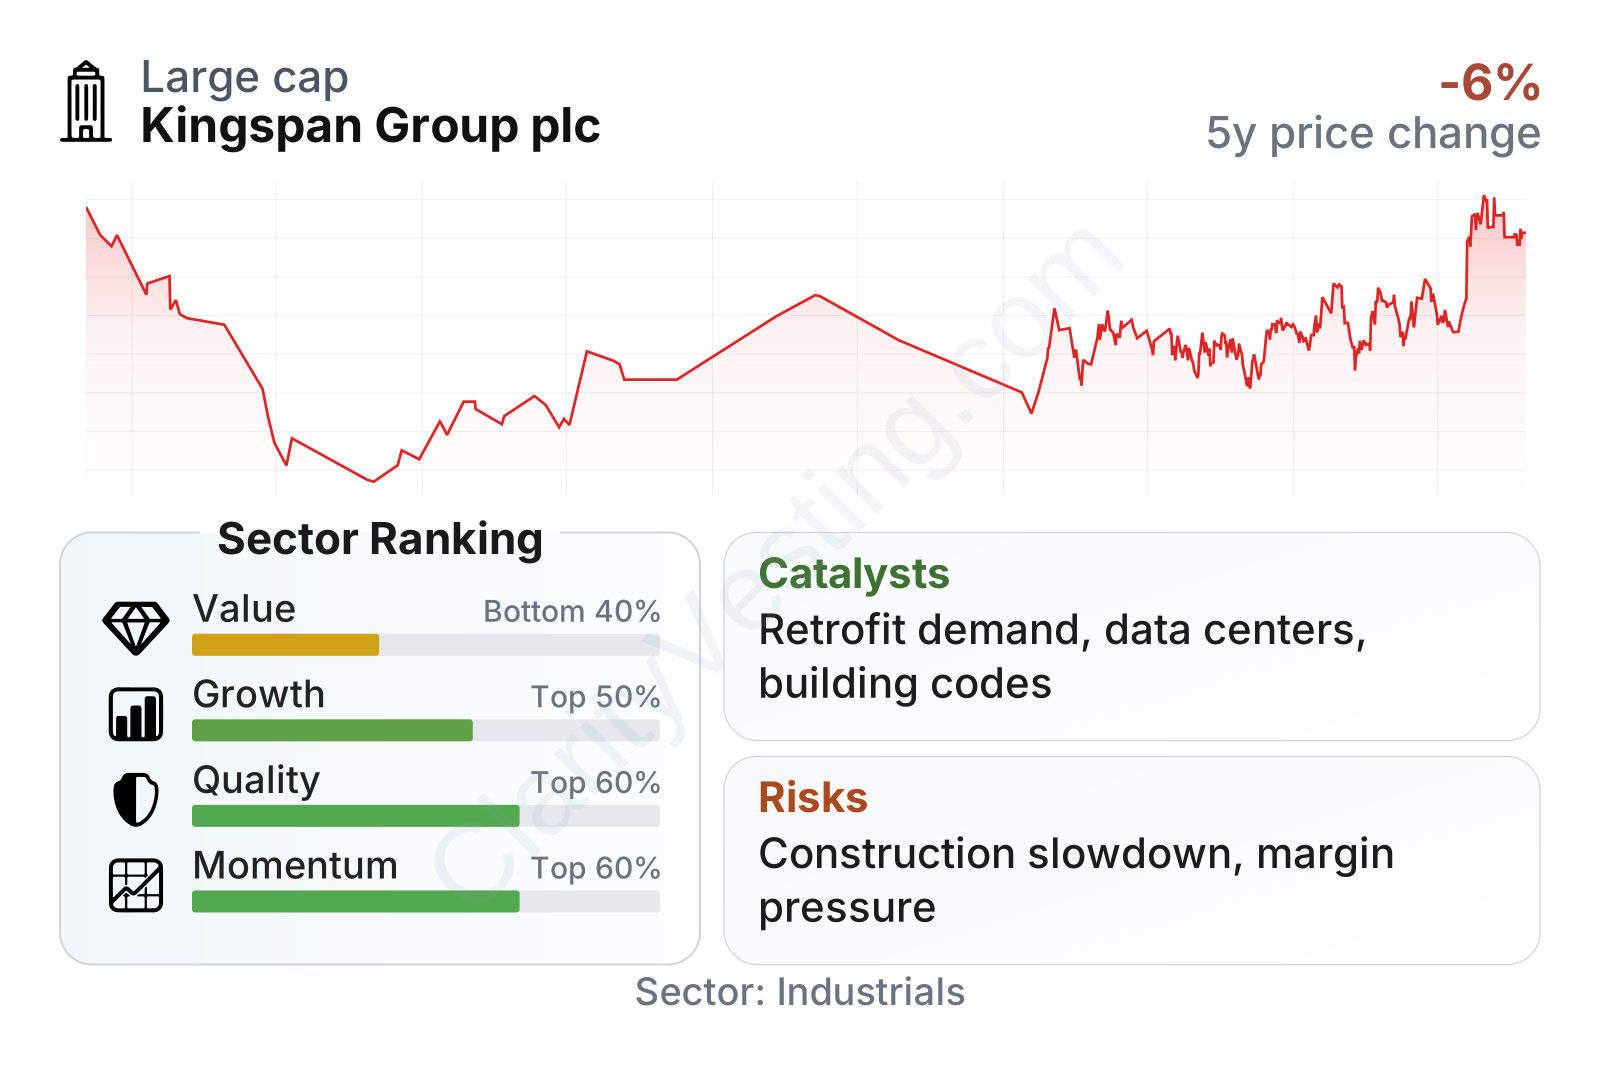
Kingspan is a large building-products company with a market value around the upper end of the mid-cap to large-cap range for its industry. The quality profile is one of the strongest parts of the case: returns on capital and assets are comfortably above sector medians, leverage is moderate, and interest coverage is strong. Free cash flow is also substantial in absolute terms.
The weaker area is valuation. The shares trade above the sector median on earnings and at a much higher multiple of book value, while the dividend yield is modest. Growth indicators are mixed: long-term revenue per share, book value per share, and free cash flow have advanced well, but earnings per share and operating margin trends have been less consistent. Recent stock performance has been strong, with returns over the last 6 to 12 months running well ahead of the broader sector.
Growth
Kingspan operates in parts of the construction market that are supported by structural demand rather than only by general building volumes. Energy-efficient buildings, stricter insulation standards, industrial and logistics construction, and retrofit activity all create a favorable backdrop. In Europe and many other regions, regulation increasingly pushes developers and owners toward better thermal performance and lower operating emissions. That directly aligns with Kingspan’s main product categories.
The company’s strategy also makes industrial sense. It combines premium insulation products with prefabricated building envelope systems, which can save time on-site and improve performance over the life of a building. That is an attractive combination in markets where labor is expensive, building codes are tightening, and customers increasingly look at total building efficiency rather than only upfront cost.
Kingspan has also used acquisitions to broaden its product range and geographic reach. That approach can strengthen distribution, deepen its presence in specialist niches, and reduce dependence on any single end market. The risk, of course, is execution, but historically this has been an important part of the company’s expansion model.
Recent financial progression supports the view that the company is still expanding, though not in a straight line. Revenue has climbed meaningfully since 2021, with a brief pause in 2023 before resuming growth in 2024 and 2025. Over five years, revenue per share growth has outpaced the sector median, and free cash flow growth has been particularly strong. That combination suggests Kingspan is not only getting bigger, but also preserving a healthy ability to generate cash.
A notable catalyst is exposure to data centers and other technical buildings that need high-performance envelope and insulation solutions. Another is the long renovation cycle ahead in older building stock, especially in Europe, where upgrading insulation is one of the most direct ways to reduce energy consumption. If building regulation continues to tighten and energy efficiency remains a priority for property owners, Kingspan’s addressable market can keep expanding even if broader construction activity is uneven.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


