Stock Analysis · Korn Ferry (KFY)
Overview
Korn Ferry is a global organizational consulting firm that helps companies hire leaders, design compensation, shape corporate structures, and develop employees. In simple terms, it sits at the intersection of recruiting, human resources consulting, leadership assessment, and professional talent solutions. Its clients are typically medium and large organizations that need help finding executives, improving workforce performance, or managing change.
The business has become more diversified than a traditional executive search firm. Based on the company’s latest annual filing for the fiscal year ended April 30, 2026, revenue is spread across several service lines rather than relying on one activity alone. Approximate revenue sources are:
- Professional Search & Interim: about 36% of revenue. This includes permanent placement for professionals below the top executive level and interim talent solutions.
- Consulting: about 27% of revenue. This covers organizational strategy, assessment, succession, leadership development, and compensation advisory.
- Digital: about 16% of revenue. This includes subscription and platform-based products tied to talent assessment, pay, and workforce intelligence.
- Executive Search: about 14% of revenue. This is the classic board and senior leadership recruiting business.
- Recruitment Process Outsourcing: about 7% of revenue. This involves managing parts of a client’s recruiting function at scale.
That mix matters because it gives Korn Ferry exposure to both cyclical hiring activity and more recurring advisory or digital work. It also helps explain why the company is often compared not only with staffing firms, but also with management consulting and HR technology providers.
Looking at the operating profile, the company’s cost structure has historically been driven much more by personnel and overhead than by direct production costs, which is typical for a knowledge-based services business. Recent results also show a recovery in operating income and net income after a softer period in 2023 and 2024.
The business model remains asset-light, with most of the value created through relationships, brand, intellectual property, and consultant productivity rather than heavy capital spending.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Staffing & Employment Services | |
| Market Cap ⓘ | $4.02B | |
| Beta ⓘ | 1.26 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.59 | 22.10 |
| P/B Ratio ⓘ | 1.83 | 1.97 |
| FCF Yield ⓘ | 7.92% | 6.38% |
| Dividend Yield ⓘ | 2.90% | 1.94% |
| EBIT / EV ⓘ | 10.58% | 4.79% |
| PEG ⓘ | 1.20 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 3.11% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -31.73% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 6.76% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -3.43% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | -7.98% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 41.18% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.64% | 10.84% |
| ROA (Latest) ⓘ | 7.42% | 5.41% |
| ROIC (5Y Median) ⓘ | 12.10% | 9.38% |
| ROA (5Y Median) ⓘ | 6.53% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -0.50 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.20 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -0.41 | 1.39 |
| Net Debt / Assets ⓘ | -5.44% | 19.28% |
| EBITDA / Interest ⓘ | 24.61 | 9.58 |
| Operating Margin (Latest) ⓘ | 13.86% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 13.23% | 10.29% |
| Debt to Equity (Latest) ⓘ | 29.74% | 65.48% |
| Profit Margin (Latest) ⓘ | 9.47% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $318.71M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +56.90% | +61.68% |
| 12M Return (excl. last month) ⓘ | +11.78% | +12.58% |
| 6M Return ⓘ | +13.74% | 0.00% |
| Price vs. 200-Day MA ⓘ | +1.78% | +0.02% |
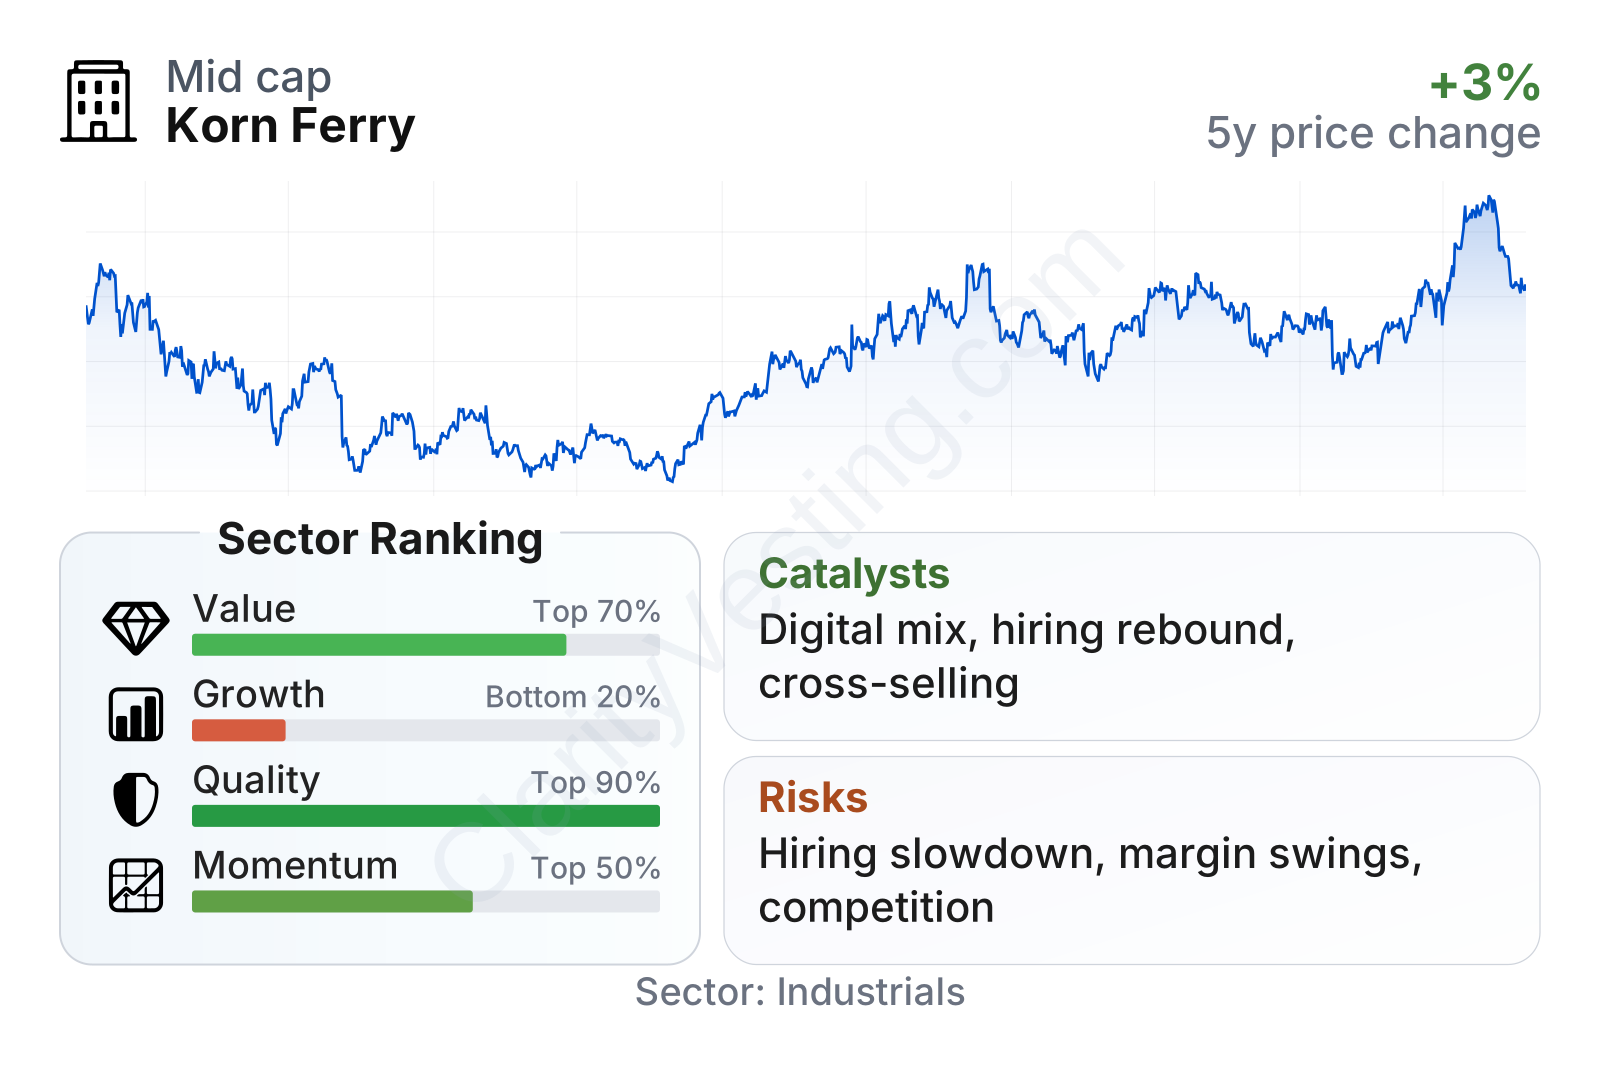
Korn Ferry stands out more for quality and balance-sheet strength than for fast growth. Profitability is above the sector median, returns on capital are healthy, and leverage is conservative, with debt-to-equity close to 30%, well below the sector median near 62%. The company also carries a net cash position on several debt-to-earnings measures, which adds resilience. On valuation measures, the stock trades at a lower earnings multiple than the sector while also offering a free cash flow yield and dividend yield above typical peers. The weaker area is growth: revenue has returned to modest expansion, but longer-term earnings and free cash flow trends remain less impressive than much of the sector.
Growth
Korn Ferry operates in a sector that should remain relevant over the long run. Companies continue to spend on leadership hiring, workforce redesign, pay benchmarking, employee assessment, and outsourced recruiting. Those needs are tied to lasting themes such as labor shortages in specialized roles, succession planning, global talent competition, and the increasing use of data in HR decisions. This is not a high-growth industry in every year, but it benefits from structural demand as organizations continuously adapt their workforces.
The company’s strategy also makes sense for future expansion because it is built around cross-selling. A client that first uses Korn Ferry for executive recruiting can later buy compensation advice, leadership assessment, digital tools, or broader consulting work. That approach can deepen relationships and smooth some of the volatility that comes from pure recruiting cycles.
Recent revenue trends suggest the downturn seen in 2024 has eased. Year-over-year revenue growth moved back into positive territory and has recently been running in the high-single-digit range. That is not exceptional versus the sector, but it does indicate renewed momentum after a weak patch. In an industry where confidence and hiring activity can swing quickly, a return to steady positive growth is an important signal.
Cash generation remains another constructive point. Free cash flow has fluctuated over the last several years, falling during the slowdown and then recovering, but it has stayed solid in absolute terms for a company of this size. That supports acquisitions, dividends, and share repurchases without requiring aggressive borrowing.
A meaningful catalyst is Korn Ferry’s push to combine consulting expertise with digital products. The company has been emphasizing platform-based offerings, including compensation data and talent assessment tools, which can potentially scale better than labor-intensive search assignments. Another catalyst is any broad improvement in corporate hiring confidence: executive search, professional search, and outsourcing activity typically improve when clients become more willing to invest in expansion and leadership changes.
Recent company communications have also highlighted stronger fee trends in search and continued demand for consulting and digital offerings. That matters because it suggests growth is not resting on one narrow business line.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


