Stock Analysis · Ivanhoe Mines Ltd (IVPAF)
Overview
Ivanhoe Mines Ltd is a mining company focused on discovering, developing, and operating large metal deposits, mainly in Africa. Its main focus is copper, but it also has meaningful exposure to zinc, platinum-group metals, nickel, and germanium through a mix of producing assets and development projects. The company is best known for its interest in the Kamoa-Kakula copper complex in the Democratic Republic of the Congo, one of the most important new copper districts brought into production in recent years.
Today, the business is still shaped by a transition: it is moving from being mainly a project developer to becoming a larger-scale producer with several mines and smelter-related assets contributing over time. That helps explain why accounting earnings can look strong while cash generation remains under pressure, as large expansion spending continues.
The main sources of economic value and operating contribution are concentrated in a small number of assets.
- Kamoa-Kakula copper complex: the dominant source of revenue and earnings, representing the large majority of current business activity. Based on recent company disclosures, copper is the company’s core driver and likely accounts for well above 80% of operating value. This includes mined and processed copper concentrate from a rapidly expanding, high-grade deposit.
- Kipushi mine: a smaller but important source tied mainly to zinc. Commercial ramp-up adds a second producing asset and diversifies the company beyond copper, but it is still far smaller than Kamoa-Kakula at this stage.
- Platreef project: currently a development-stage asset rather than a major revenue source. Over time it is designed to produce platinum, palladium, rhodium, nickel, copper, and gold, which could materially broaden the company’s revenue mix once production begins.
Financially, the company’s profile has changed sharply over the last few years. Revenue has moved from almost no meaningful operating sales to several hundred million dollars as production assets matured, while operating income turned positive. The next step is converting that operating progress into steadier free cash flow.
The financial flow has shifted from a pre-revenue development model to a producing miner with meaningful sales and operating profit. At the same time, expenses remain elevated because Ivanhoe is still funding major expansion projects, which is why profit and cash flow do not yet tell the same story.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $12.04B | |
| Beta ⓘ | 1.86 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 93.78 | 17.61 |
| P/B Ratio ⓘ | 1.90 | 1.77 |
| FCF Yield ⓘ | -3.49% | 5.87% |
| Dividend Yield ⓘ | N/A | 2.06% |
| EBIT / EV ⓘ | 0.93% | 6.43% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 57.70% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | -42.75% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 21.42% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 1.35% | 9.31% |
| ROA (Latest) ⓘ | 2.04% | 4.94% |
| ROIC (5Y Median) ⓘ | 2.94% | 7.91% |
| ROA (5Y Median) ⓘ | 4.25% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 5.55 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.36 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 3.41 | 0.91 |
| Net Debt / Assets ⓘ | 8.61% | 13.69% |
| EBITDA / Interest ⓘ | 4.04 | 11.93 |
| Operating Margin (Latest) ⓘ | 21.86% | 13.07% |
| Operating Margin (5Y Median) ⓘ | N/A | 11.86% |
| Debt to Equity (Latest) ⓘ | N/A | 40.43% |
| Profit Margin (Latest) ⓘ | 23.47% | 6.57% |
| Free Cash Flow (Latest) ⓘ | -$420.29M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -5.31% | +65.06% |
| 12M Return (excl. last month) ⓘ | -1.46% | +36.05% |
| 6M Return ⓘ | -3.75% | +1.89% |
| Price vs. 200-Day MA ⓘ | -11.60% | +1.03% |
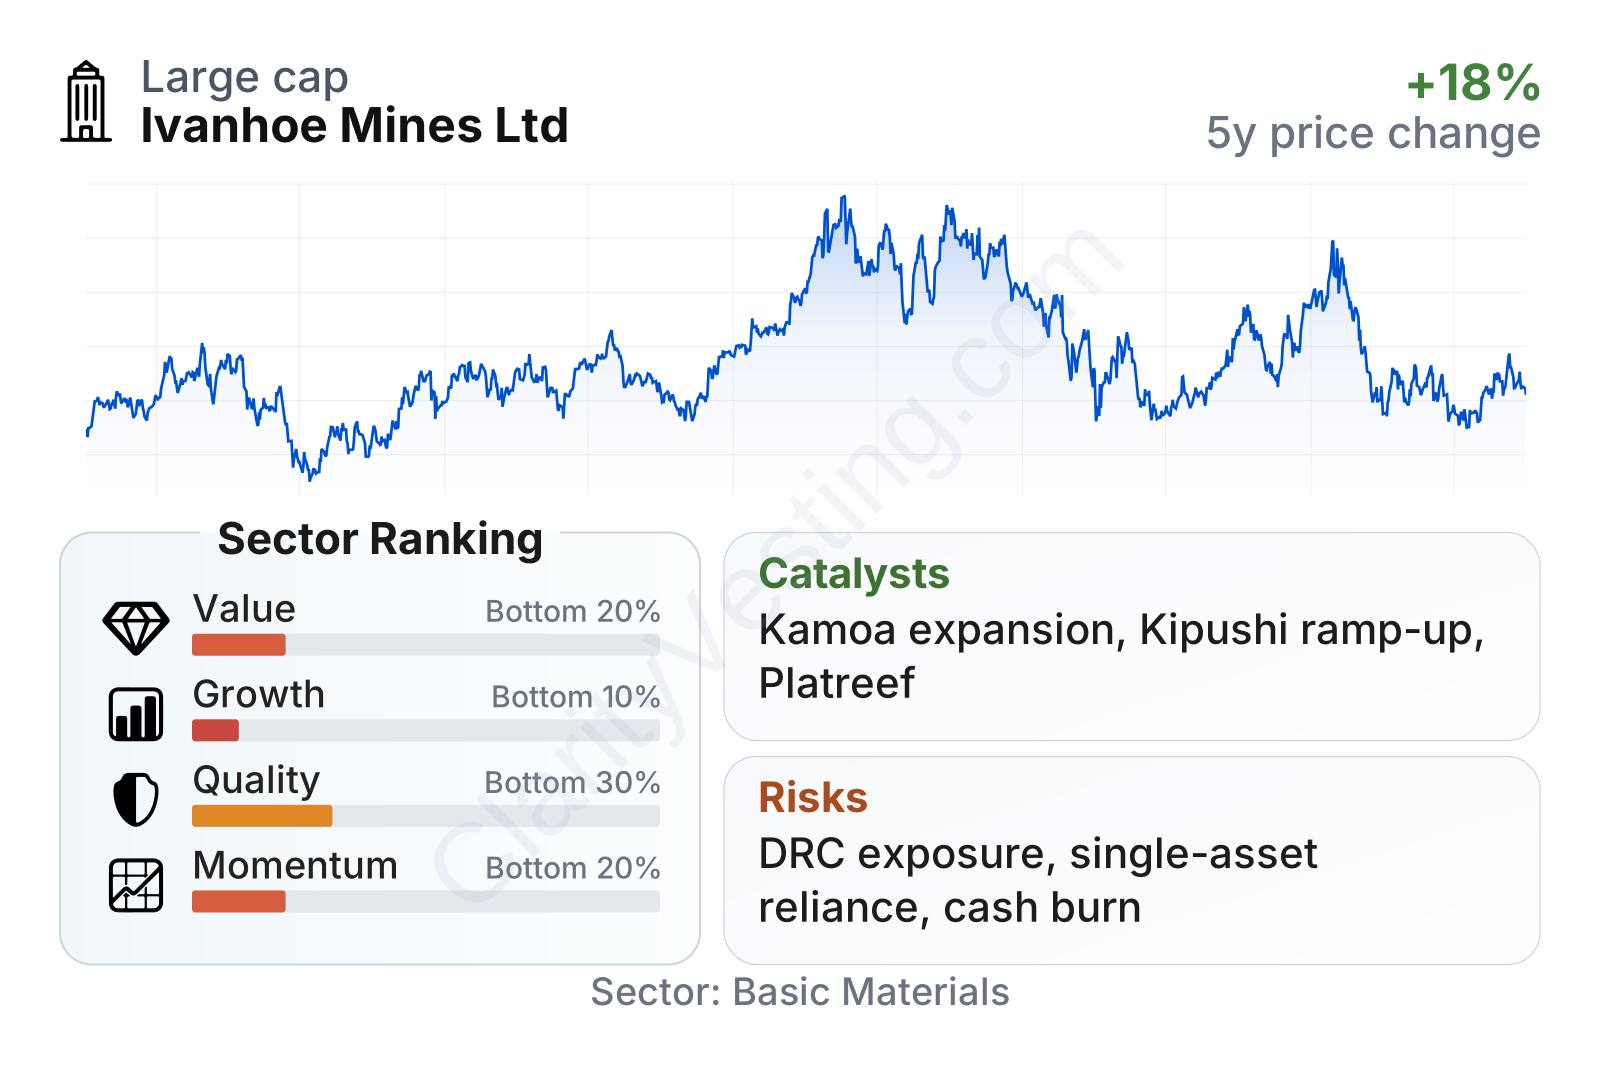
Ivanhoe Mines is a large mining company by market value, but the current financial profile is uneven. Growth in revenue has been far stronger than the sector median, while profitability on an accounting basis is also solid. However, valuation multiples are elevated, free cash flow remains negative, leverage relative to earnings is higher than typical peers, and recent share-price performance has lagged much of the sector. In short, the market is still valuing future mine expansion more than current cash returns.
Growth
Ivanhoe operates in a part of the mining industry with strong long-term demand support. Copper is central to power grids, electric vehicles, renewable energy systems, industrial equipment, and general electrification. High-grade new copper discoveries are rare, and large projects are increasingly difficult to permit and build. That gives strategic importance to companies that already control major copper resources and are able to expand them.
Its strategy is coherent for long-term growth. The company already has one world-class copper operation in Kamoa-Kakula, is ramping Kipushi, and is advancing Platreef. This creates a pipeline where one asset is producing at scale, another is entering production, and a third could become a large multi-metal operation later. That kind of staged buildout can create growth over many years rather than relying on a single mine.
Revenue growth has been exceptionally strong, although the pace is naturally moderating from very high levels as the business gets larger. Even after that slowdown, growth remains well ahead of the sector, showing that expansion projects are still feeding through into sales.
A major catalyst is the continued expansion of Kamoa-Kakula, including mine and processing growth as well as the on-site smelter strategy. If the complex keeps increasing output and captures more value through local processing, margins and logistics efficiency could improve over time. Kipushi is another important catalyst because a successful ramp-up would add a second operating base and reduce dependence on a single asset.
Recent company updates also matter because they point to future production capacity rather than only short-term earnings. In mining, the market often reacts to commissioning milestones, recovery rates, grade performance, and project timelines. For Ivanhoe, those operational milestones are especially important because a large part of the long-term case depends on proving that its asset base can scale efficiently.
Free cash flow remains deeply negative, which is common during heavy mine construction and expansion. The key issue is not simply that cash flow is negative today, but whether current spending is building durable future production at attractive economics. Ivanhoe appears to be in that investment-heavy phase, so growth is visible in operations before it is visible in cash generation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


