Stock Analysis · Intuitive Surgical Inc (ISRG)
Overview
Intuitive Surgical is a medical technology company best known for its robotic-assisted surgery platforms, especially the da Vinci system. Its products are used by hospitals and surgeons to perform minimally invasive procedures in areas such as urology, gynecology, general surgery, thoracic surgery, and other specialties. The business model is important to understand because it does not depend only on selling robots. Once a hospital installs a system, Intuitive Surgical can continue generating revenue from instruments, accessories, service contracts, and training tied to ongoing procedure volume.
That recurring element makes the company structurally different from a typical device maker. Over time, the installed base of systems has expanded, and that creates a larger stream of repeat purchases every time procedures are performed. The company also operates the Ion platform for minimally invasive lung biopsy and the SP system for single-port surgery, which broadens its opportunity beyond the original multi-port da Vinci business.
Based on recent company reporting, the main revenue sources are approximately:
- Instruments and accessories: about 60% of revenue. This includes disposable or limited-use tools and other items used during procedures on da Vinci and other platforms.
- Systems: about 22% of revenue. This is the sale or lease of robotic surgical systems, including da Vinci, Ion, and SP platforms.
- Services: about 18% of revenue. This includes service contracts, maintenance, and support for installed systems.
This mix matters because the largest piece comes from procedure-driven recurring revenue rather than one-time capital equipment sales. It helps explain why the company can keep growing even when hospital purchasing cycles are uneven.
The long-term financial profile also shows a business converting a growing revenue base into rising gross profit and net income, while continuing to spend heavily on research, development, and commercial support. Revenue has climbed from about $5.7 billion in 2021 to more than $10.0 billion in 2025, while profitability has also improved, showing that scale has not come at the expense of margins.
The operating picture points to a company with strong gross economics and room to reinvest. Research and development spending has risen steadily, but so have operating income and net income, which suggests Intuitive Surgical has been able to expand while defending its economics.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $145.69B | |
| Beta ⓘ | 1.47 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 47.17 | 24.06 |
| P/B Ratio ⓘ | 7.97 | 3.08 |
| FCF Yield ⓘ | 2.21% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 2.72% | 0.63% |
| PEG ⓘ | 1.87 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 18.50% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 15.47% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | 3.32% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 10.68% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 1.01% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 9.45% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.59% | 3.29% |
| ROA (Latest) ⓘ | 15.60% | 3.02% |
| ROIC (5Y Median) ⓘ | 15.39% | 4.75% |
| ROA (5Y Median) ⓘ | 13.55% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | -0.74 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.93 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | -0.61 | 0.99 |
| Net Debt / Assets ⓘ | -13.22% | 5.33% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | 33.76% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 31.89% | 7.80% |
| Debt to Equity (Latest) ⓘ | N/A | 28.99% |
| Profit Margin (Latest) ⓘ | 28.45% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $3.22B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +36.02% | +37.48% |
| 12M Return (excl. last month) ⓘ | -21.98% | +20.85% |
| 6M Return ⓘ | -13.61% | +9.73% |
| Price vs. 200-Day MA ⓘ | -10.45% | +4.69% |
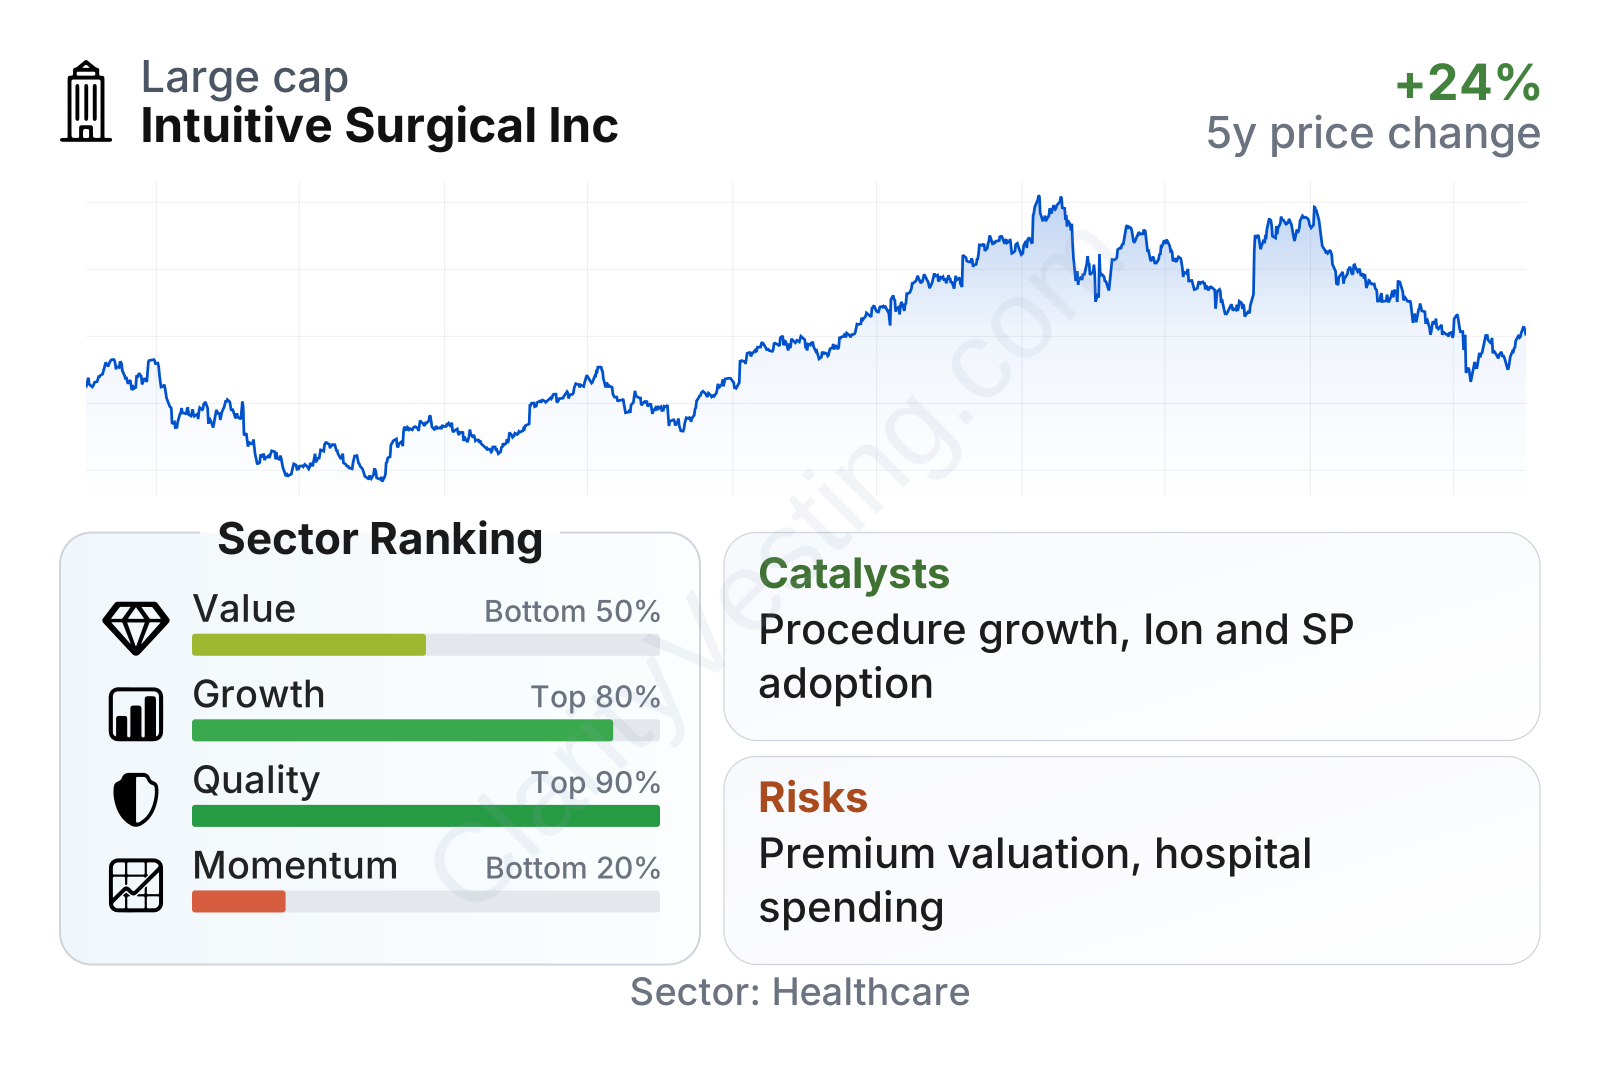
Intuitive Surgical stands out on business quality and growth, while appearing less attractive on traditional valuation measures. Profitability is far above typical healthcare equipment peers, and growth rates in revenue, free cash flow, and returns on capital are also stronger than most companies in the sector. The weaker area is valuation, with earnings and book multiples well above sector norms. Recent share-price momentum has also been softer than the broader healthcare group, which shows the stock has cooled even as the underlying business has remained strong.
In size, Intuitive Surgical is one of the larger names in medical technology. Its beta above 1 also suggests the stock can move more sharply than the broader market, which is worth remembering for readers looking at long-term volatility as well as long-term business quality.
Growth
Intuitive Surgical operates in a sector with durable structural growth drivers. Healthcare systems continue to face pressure to improve outcomes, shorten recovery times, and make surgical workflows more efficient. Robotic-assisted surgery fits into that trend because it can support minimally invasive procedures, improve visualization and control for surgeons, and build standardized operating room processes. Procedure growth is therefore more important than simple hospital equipment budgets.
The company’s strategy for future expansion is coherent. First, it keeps increasing the installed base of robotic systems. Second, it benefits when more surgeons and hospitals use those systems more often. Third, it expands into new indications, geographies, and newer platforms such as Ion and SP. This layered model matters because it creates multiple growth engines rather than relying on a single product cycle.
Recent revenue growth has remained strong, generally running in the mid-teens to low-twenties range year over year, which is clearly above the sector median. That suggests demand is not only intact but still expanding at a healthy pace. Over a five-year view, revenue per share growth has also been solid, showing that the business has compounded rather than simply rebounded from one unusual period.
Cash generation has also strengthened meaningfully. Free cash flow moved from well under $1 billion at its lower point in this series to nearly $3 billion more recently. That gives the company unusual flexibility: it can keep investing in product development, manufacturing, training, and global expansion without relying on financial leverage.
One important catalyst is the continued rise in procedure volume. Every additional procedure supports instruments and accessories revenue, which is the company’s largest segment. Another is broader adoption of Ion in lung biopsy and SP in procedures suited to single-port access, since these platforms can deepen Intuitive Surgical’s role beyond its traditional franchise. The company has also continued to introduce system upgrades and software enhancements, which can improve customer retention and usage.
Recent company updates have pointed to ongoing procedure growth, expansion of the installed base, and continued progress in newer platforms. For a long-term business view, that combination is significant because it indicates Intuitive Surgical is still early enough in its penetration curve to grow, yet established enough to produce substantial cash and earnings today.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


