Stock Analysis · IQVIA Holdings Inc (IQV)
Overview
IQVIA Holdings Inc is a healthcare services and technology company that sits at the intersection of pharmaceuticals, biotechnology, medical research, and health data. In simple terms, it helps drugmakers and healthcare organizations design clinical trials, run those trials, analyze results, understand treatment patterns, and use software tools to improve commercial decisions. The company was formed through the combination of Quintiles, a major contract research organization, and IMS Health, a leader in healthcare information and analytics. That combination still shapes the business today: IQVIA earns money both from hands-on research services and from data-driven technology offerings.
Its revenue is mainly split across three operating segments. Based on recent annual reporting, the mix is approximately:
- Technology & Analytics Solutions: about 39% of revenue. This segment includes healthcare data, analytics, consulting, and software used by life sciences companies to study markets, patients, prescribing trends, and commercial performance.
- Research & Development Solutions: about 34% of revenue. This is the clinical research arm, where IQVIA helps customers plan and run clinical trials, manage study sites, recruit patients, and support laboratory and regulatory work.
- Contract Sales & Medical Solutions: about 27% of revenue. This business provides outsourced sales teams, patient engagement services, nurse educators, and other support aimed at commercialization and field execution.
This structure matters because it gives IQVIA exposure to both recurring information services and the longer-cycle clinical development market. Over the last several years, revenue has continued to rise overall, while operating income expanded faster than sales through 2024, showing that the business has had some operating leverage even in a demanding research environment.
The financial flow over recent years shows a business that has grown revenue steadily from the low-$13 billion range to above $16 billion, while operating profit also increased. One point to watch is that interest expense remains sizable, which reflects the company’s leveraged balance sheet and reduces the portion of operating profit that ultimately becomes net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $45.90B | |
| Beta ⓘ | 1.17 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 34.64 | 25.42 |
| P/B Ratio ⓘ | 7.77 | 3.08 |
| FCF Yield ⓘ | 5.69% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 4.03% | 0.56% |
| PEG ⓘ | 0.97 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.70% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 7.21% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -14.51% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 4.36% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 3.26% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | -2.85% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | -68.86% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 8.98% | 3.17% |
| ROA (Latest) ⓘ | 4.69% | 2.98% |
| ROIC (5Y Median) ⓘ | 9.17% | 4.56% |
| ROA (5Y Median) ⓘ | 4.79% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 6.11 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 6.18 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 4.06 | 1.00 |
| Net Debt / Assets ⓘ | 47.96% | 5.06% |
| EBITDA / Interest ⓘ | 4.58 | 9.55 |
| Operating Margin (Latest) ⓘ | 13.81% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 14.09% | 7.33% |
| Debt to Equity (Latest) ⓘ | 263.18% | 26.68% |
| Profit Margin (Latest) ⓘ | 8.10% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $2.61B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +51.50% | +51.61% |
| 12M Return (excl. last month) ⓘ | +43.79% | +19.90% |
| 6M Return ⓘ | +58.85% | +10.10% |
| Price vs. 200-Day MA ⓘ | +33.45% | +6.44% |
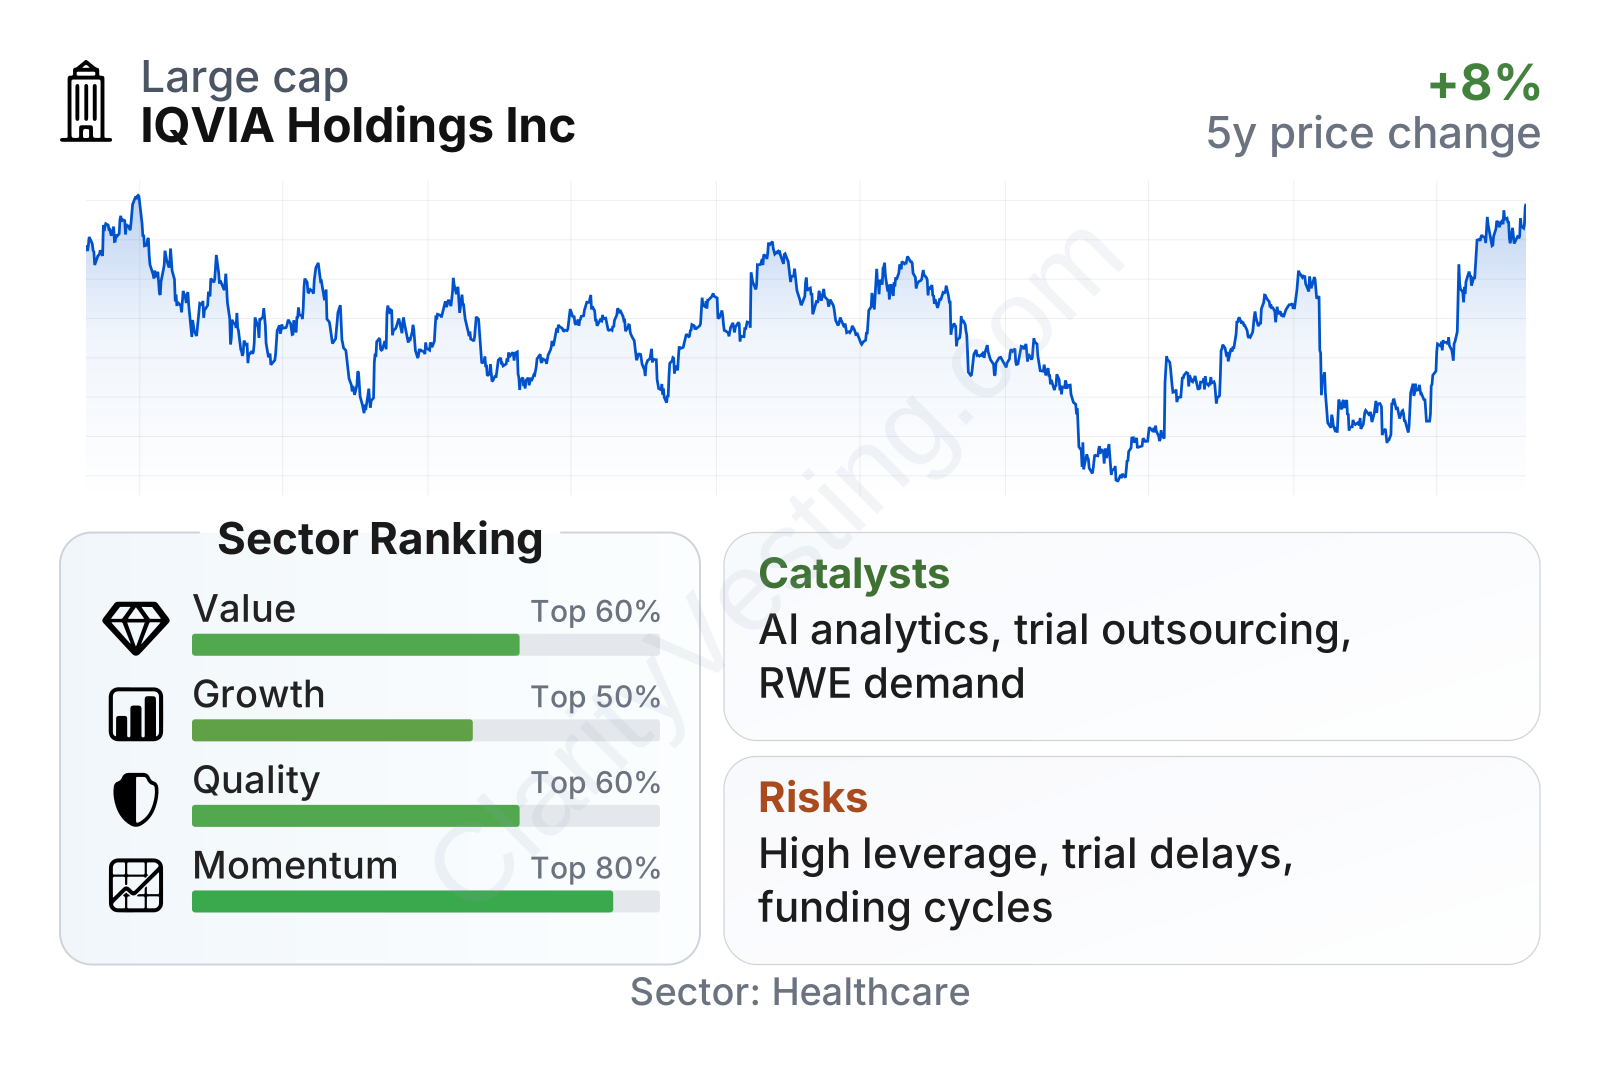
IQVIA stands out as a large healthcare services company with above-sector profitability and returns on capital, but also clearly above-sector leverage. The overall factor profile suggests a business with solid quality and growth characteristics, while valuation looks more mixed: earnings and book-based multiples are not low, yet cash generation compares favorably with many peers. Recent price performance has also been strong relative to much of the healthcare sector.
Growth
IQVIA operates in markets with durable long-term demand. Drug development has become more complex, regulators increasingly expect better evidence, and pharmaceutical companies continue to outsource work to specialized partners to control costs and speed timelines. At the same time, healthcare companies are relying more on real-world evidence, patient-level information, and software tools to guide commercial strategy. Those trends support IQVIA’s combination of trial execution, analytics, and technology.
A key part of the company’s growth logic is that its businesses reinforce each other. A drug developer can use IQVIA to design a study, recruit and manage sites, analyze healthcare data, support regulatory needs, and later prepare for launch with commercial analytics and field support. That end-to-end model can make the platform more attractive than using separate vendors for each step, especially for large global customers.
Revenue growth has not been explosive, but it has been consistent. Growth slowed after the stronger post-pandemic rebound period, then improved again into the latest periods, reaching high-single-digit year-over-year expansion. That pattern suggests the company is still growing even while parts of biotech funding and research demand have been uneven.
Cash generation is another positive point. Free cash flow has recovered from a softer period and moved meaningfully higher, recently reaching well above $2.5 billion on a trailing basis. For a long-term analysis, that matters because strong cash flow gives the company room to invest in technology, pursue acquisitions, repurchase shares, and manage debt.
Recent company updates have also emphasized demand for more efficient clinical trial models, broader use of artificial intelligence in healthcare analytics, and continued interest in real-world evidence. These are important opportunities because IQVIA already owns large healthcare information assets and has long relationships with major pharmaceutical companies. If those trends keep accelerating, the company is positioned to benefit not only from more trial activity, but also from higher-value data and software services.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


