Stock Analysis · Ipsos SA (IPSOF)
Overview
Ipsos SA is a global market research and consulting group. In simple terms, it helps companies, governments, and institutions understand what people think, want, and do. Its work includes opinion polls, brand tracking, advertising testing, customer experience studies, innovation research, media audience measurement, and public affairs surveys. The company operates in many countries and sells both customized studies and recurring research programs, which gives it exposure to a wide range of clients and industries.
The business model is mainly service-based: Ipsos is paid to design research, collect data, analyze results, and deliver recommendations. Compared with many consulting businesses, one important feature is that Ipsos combines human expertise with large-scale survey panels, technology platforms, and long-term client relationships. That makes the company less dependent on any single contract than a project-only advisory firm.
Based on the company’s reporting structure, revenue is primarily organized by service line rather than by product in a traditional manufacturing sense. The main sources of revenue are approximately the following:
- Brand, advertising, and media research: about 35% to 45% of revenue. This includes testing ad campaigns, measuring brand perception, and helping clients understand media audiences and marketing effectiveness.
- Customer experience and relationship management: about 15% to 25%. This covers satisfaction surveys, loyalty measurement, and service quality analysis.
- Innovation, product development, and market understanding: about 15% to 25%. This includes research on new products, pricing, packaging, and consumer demand.
- Public affairs, social research, and opinion polling: about 10% to 20%. This area serves governments, public institutions, and organizations needing social and political insights.
- Healthcare and other specialized research: about 5% to 15%. This includes pharmaceutical, medical, and sector-specific studies.
Geographically, Ipsos is broadly diversified across Europe, the Americas, and Asia-Pacific, which reduces dependence on one national economy. That said, Europe remains an important profit center because the company is headquartered in France and has long-standing positions in several mature European markets.
The broader revenue and profit flow shows a business with fairly steady sales, high gross margins typical of research services, and operating income that has stayed resilient despite some year-to-year fluctuations. Revenue moved from roughly €2.1 billion in 2021 to more than €2.5 billion in 2025, while net income remained positive throughout the period.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Consulting Services | |
| Market Cap ⓘ | $1.62B | |
| Beta ⓘ | 0.65 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.35 | 22.10 |
| P/B Ratio ⓘ | 1.07 | 1.97 |
| FCF Yield ⓘ | N/A | 6.38% |
| Dividend Yield ⓘ | 5.13% | 1.94% |
| EBIT / EV ⓘ | 15.33% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.30% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 4.58% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -33.31% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 4.39% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -1.39% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | -7.76% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 19.50% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | N/A | 5.41% |
| ROIC (5Y Median) ⓘ | 10.86% | 9.38% |
| ROA (5Y Median) ⓘ | 7.06% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.50 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.39 |
| Net Debt / Assets ⓘ | 7.05% | 19.28% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | N/A | 10.50% |
| Operating Margin (5Y Median) ⓘ | 12.41% | 10.29% |
| Debt to Equity (Latest) ⓘ | N/A | 65.48% |
| Profit Margin (Latest) ⓘ | 6.86% | 6.67% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -22.34% | +61.68% |
| 12M Return (excl. last month) ⓘ | +7.97% | +12.58% |
| 6M Return ⓘ | +0.74% | 0.00% |
| Price vs. 200-Day MA ⓘ | -0.45% | +0.02% |
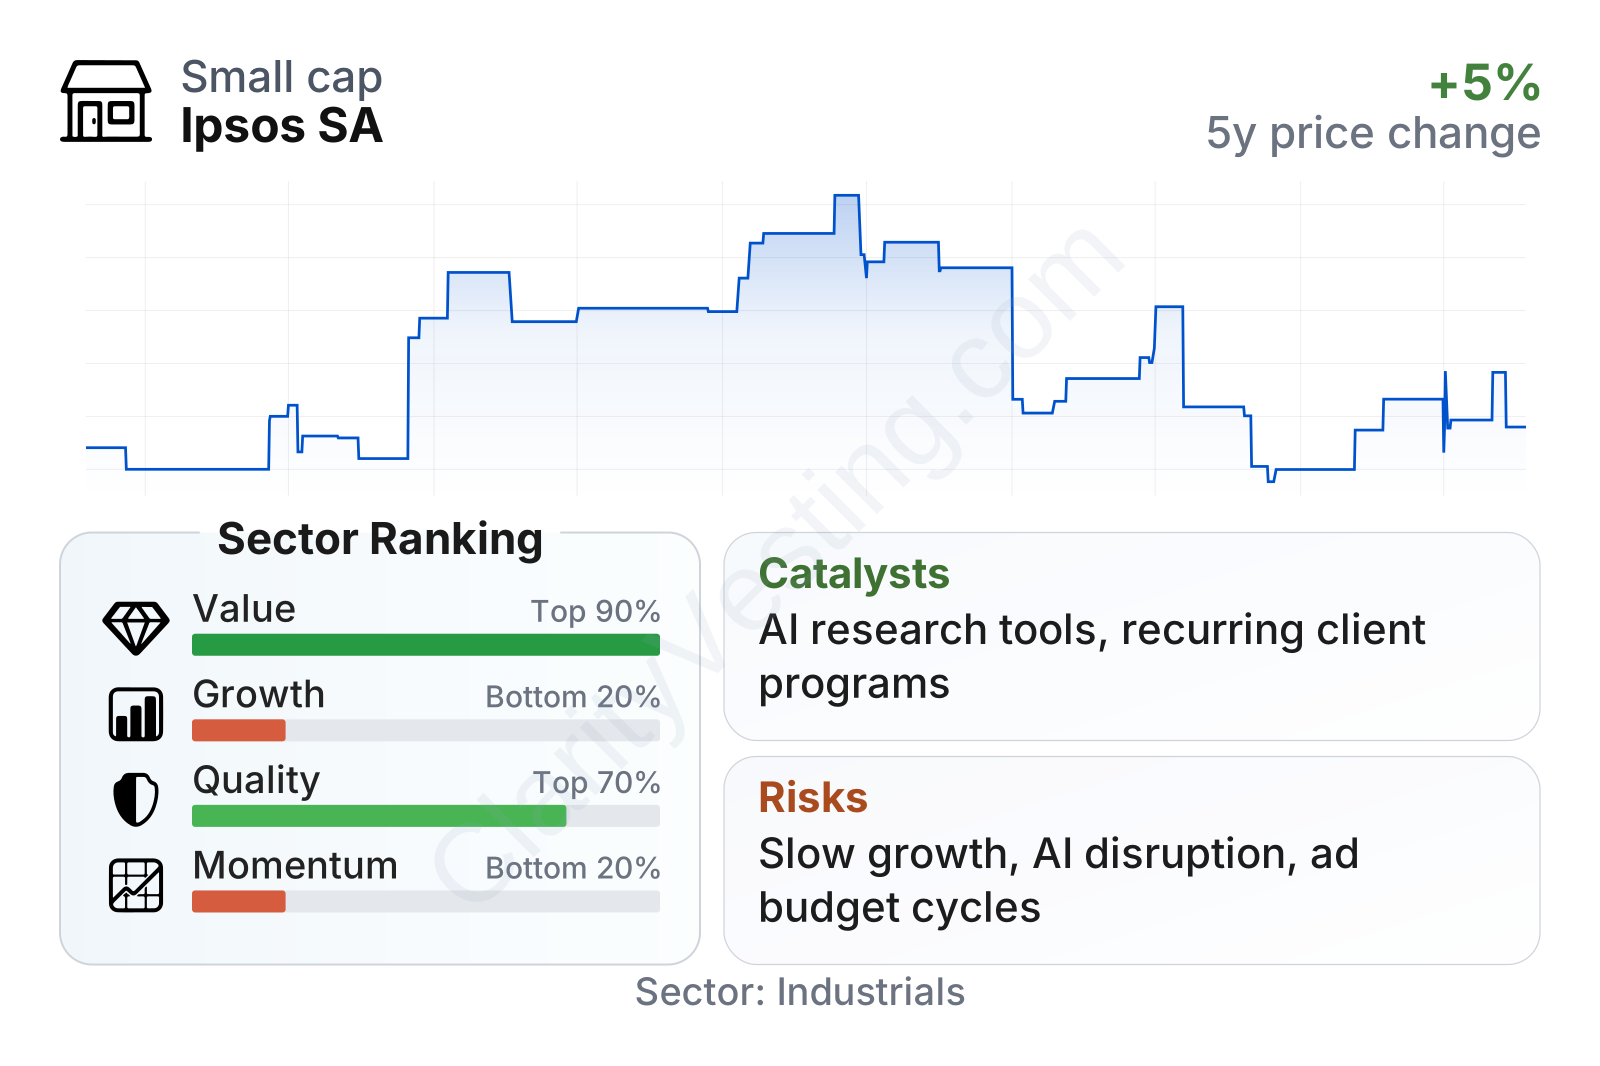
The market profile looks unusual in a constructive way. Ipsos trades at valuation multiples that are well below the sector median, while profitability and balance-sheet quality appear better than many peers. The main weakness is not financial strength but growth: recent revenue expansion has been modest, margins have not shown a clear multi-year upward trend, and share-price performance has lagged much of the sector over the last one to three years. The dividend yield is also notably above the sector median, which suggests the market is pricing the company more as a mature cash-generating business than as a high-growth name.
The share-price history reflects that mixed picture. After a strong run into 2023 and part of 2024, the stock gave back a meaningful portion of those gains in 2025 and has only partly stabilized in 2026. In other words, the market has become more cautious even though the company remains profitable and financially solid.
Growth
Ipsos operates in a sector that still has long-term relevance, even if it is no longer viewed as a fast-growth niche. Companies increasingly need consumer insight, campaign measurement, customer analytics, and fast feedback loops. Those needs support demand for research services, especially as product cycles shorten and marketing spending becomes more performance-driven. Public sector polling and social research also remain structurally important in many countries.
The strategic question is whether Ipsos can grow faster than the traditional research industry. Its path forward is based on combining classic survey expertise with technology, data analytics, and AI-enabled research tools. That strategy makes sense. Clients want quicker, cheaper, and more continuous insight, and providers that can automate parts of questionnaire design, respondent targeting, analysis, and reporting should be better placed than firms relying only on labor-intensive legacy methods.
Another positive point is scale. Ipsos is one of the largest global research groups, which matters because multinational clients often want one provider able to deliver comparable work across countries. That scale can support recurring contracts, cross-selling across service lines, and better use of research panels and platforms.
A practical catalyst is the ongoing shift from one-off studies toward platform-based and recurring insight programs. If Ipsos continues improving its digital tools and AI-assisted offerings, it may strengthen client retention and defend margins. Acquisitions can also add growth in specialized segments or attractive geographies, as the company has historically used bolt-on deals to broaden capabilities.
Recent company communications have also highlighted resilience in demand and continued investment in technology and innovation. That does not point to explosive expansion, but it does support the idea that Ipsos is adapting rather than standing still in a changing industry.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


