Stock Analysis · Industrias Penoles Sab De CV (IPOAF)
Overview
Industrias Peñoles is one of Mexico’s largest mining groups and a major producer of precious metals. Through its mining operations, metallurgical facilities, and chemical businesses, the company extracts, processes, and sells metals used in jewelry, electronics, construction, renewable energy, and industrial applications. Its best-known exposure is to silver, but the business is broader than that: it also produces gold, zinc, lead, and copper, and it has an important chemicals segment tied mainly to sodium sulfate and related products.
The company operates through two main business platforms. The first is mining, centered on underground mines and metal processing. The second is chemical production, which gives the group some diversification away from pure metal prices. Peñoles also has a controlling stake in Fresnillo plc, one of the world’s largest primary silver producers, which is a major element in understanding the group’s economics and market profile.
Based on recent annual disclosures, Peñoles’ revenue mix is dominated by metals, with chemicals representing a smaller but still meaningful contribution. Approximate revenue sources can be summarized as follows:
- Silver: roughly 30% to 35% of revenue. This is the company’s single most important value driver and includes refined silver sold into industrial and commercial markets.
- Gold: roughly 20% to 25%. Gold supports profitability and cash generation, especially during stronger precious-metals cycles.
- Zinc: roughly 15% to 20%. This includes zinc in concentrate and refined products used mainly in galvanizing steel.
- Lead: roughly 8% to 12%. Lead contributes through concentrates and refined metal, with demand tied to batteries and industrial use.
- Copper: roughly 5% to 10%. Copper adds exposure to electrification and infrastructure demand.
- Chemicals and other products: roughly 5% to 10%. This mainly includes sodium sulfate and other chemical derivatives, plus smaller by-product streams.
The business has become much stronger operationally after a weak 2022–2024 stretch. Revenue expanded sharply in the latest period, while operating income improved much faster than sales, which suggests that better metal prices and stronger plant utilization are flowing through the income statement. Costs still absorb the largest share of revenue, as expected in mining, but recent results indicate materially better conversion from sales into operating profit and cash flow than the company showed a few years ago.
The recent profile points to a cyclical business that has regained earnings power quickly: sales have risen to a much higher level, and profitability has recovered far more dramatically than revenue alone would suggest.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $18.67B | |
| Beta ⓘ | 1.09 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.78 | 16.92 |
| P/B Ratio ⓘ | 3.67 | 1.66 |
| FCF Yield ⓘ | 12.75% | 5.83% |
| Dividend Yield ⓘ | 0.82% | 2.07% |
| EBIT / EV ⓘ | 21.49% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 38.90% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 11.30% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 75.52% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 0.95% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 12.98% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 51.85% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 54.74% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 17.12% | 4.92% |
| ROIC (5Y Median) ⓘ | 8.55% | 7.91% |
| ROA (5Y Median) ⓘ | 1.85% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.17 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.45 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.15 | 0.93 |
| Net Debt / Assets ⓘ | -5.33% | 13.69% |
| EBITDA / Interest ⓘ | 25.66 | 12.38 |
| Operating Margin (Latest) ⓘ | 39.10% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 16.13% | 11.82% |
| Debt to Equity (Latest) ⓘ | 38.68% | 40.30% |
| Profit Margin (Latest) ⓘ | 19.46% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $2.38B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +292.44% | +73.47% |
| 12M Return (excl. last month) ⓘ | +25.00% | +27.59% |
| 6M Return ⓘ | -15.35% | -4.02% |
| Price vs. 200-Day MA ⓘ | -9.85% | -0.65% |
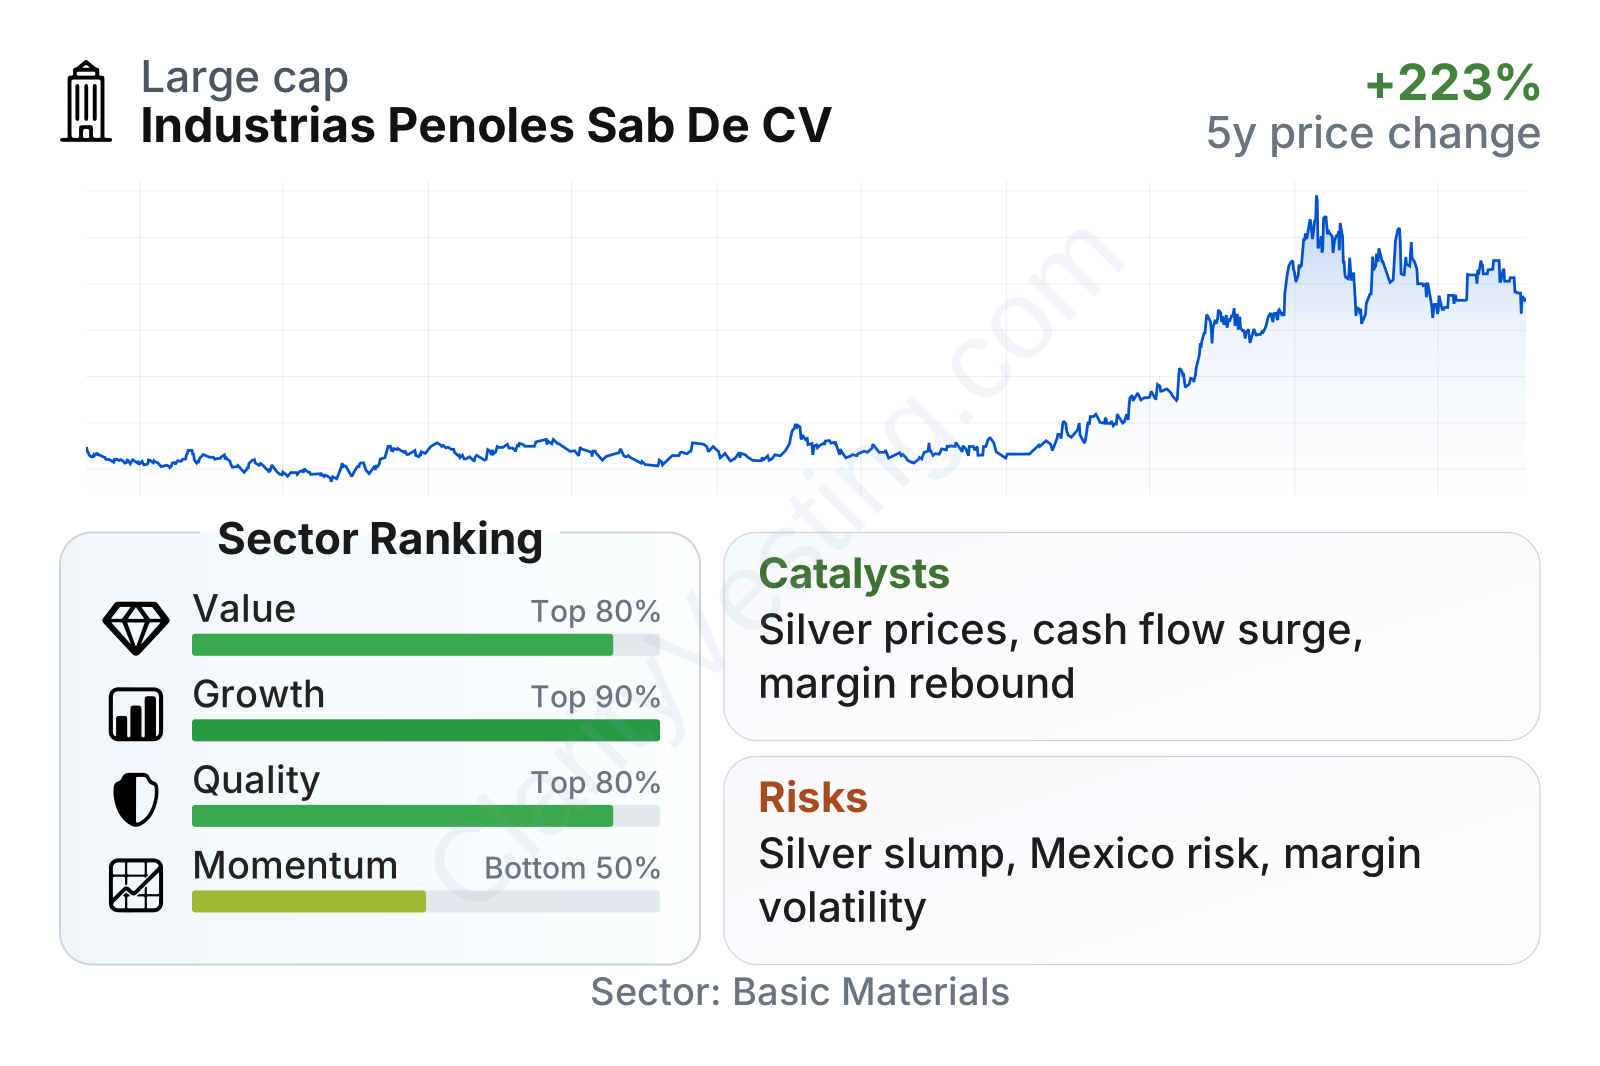
Peñoles is a large mining company by market value, with share-price volatility close to the broader materials space. The overall factor profile is strong in value, growth, and quality relative to much of the sector. The most notable points are a low earnings multiple versus the sector median, unusually high free-cash-flow yield, and very strong operating profitability. Dividend yield is modest, so the current profile is driven more by earnings and cash generation than by income distribution.
The stock’s long-term share performance has been powerful, especially since 2024, although the recent pullback from highs shows that the market still treats the company as a cyclical metals name rather than a steady compounder. Momentum remains better than the sector over multi-year and one-year periods, even after that cooling phase.
Growth
Peñoles operates in markets with credible long-term demand support, but not all of that demand is equal. Silver and gold remain the core earnings engines. Silver has an especially attractive long-term backdrop because it serves both as a precious metal and as an industrial input, including for solar panels, electronics, and electrical systems. Zinc and copper also benefit from infrastructure, grid investment, and electrification trends. That does not mean a straight line upward, but it does mean the company is exposed to several markets with structural demand drivers beyond traditional jewelry and bullion consumption.
The company’s strategy also makes industrial sense. A diversified mix of precious and base metals reduces dependence on one single commodity, while integrated smelting and refining capacity can improve value capture across the chain. The chemical business adds another layer of diversification, although it is clearly smaller than mining. In addition, the company’s exposure to Fresnillo gives it meaningful scale in silver and precious metals without Peñoles needing to replicate all of that production footprint directly inside the parent company.
Recent growth has been much stronger than the industry norm. Revenue was weak to mixed through parts of 2022 and 2023, then turned decisively upward, accelerating into 2025 and remaining strong in 2026. That matters because the rebound is not just statistical noise from a depressed base anymore; it now reflects a business operating in a much more favorable pricing and production environment.
Cash generation has also improved sharply. Free cash flow moved from negative territory in 2023 to a very strong positive level more recently, reaching above $2 billion on a trailing basis. For a mining company, that is an important signal because accounting profits can swing with prices, taxes, and non-cash items, while free cash flow gives a clearer view of operating strength after capital spending.
A key catalyst is the company’s direct leverage to precious-metal prices, especially silver and gold, combined with already improved operating margins. When a miner moves from low profitability to high profitability, each additional improvement in realized prices can have an outsized effect on earnings. Another favorable element is balance-sheet improvement, which gives management more flexibility for expansion, dividends, or debt reduction if the strong market backdrop continues.
Recent company reporting also points to stronger production and profitability conditions rather than a turnaround based only on cost cuts. For long-term analysis, that is more durable than a short-lived accounting recovery because it suggests the business is benefiting from both internal execution and external market support.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


