Stock Analysis · IPE Universal Inc (IPEU)
Overview
IPE Universal Inc is a small software company in the application software segment. Based on its public filings and company materials, the business is centered on enterprise software and digital platform services, with operations tied to technology solutions rather than hardware manufacturing. The company’s recent financial profile shows a very sharp expansion in reported revenue and earnings, which makes it stand out from many micro- and small-cap software names that remain unprofitable for long periods.
One important limitation for a simple revenue breakdown is that the company’s recent public materials do not appear to provide a detailed segment split in the same way larger software groups usually do. As a result, the revenue mix can be described only at a high level from the available filings.
- Software and application-related revenue: appears to represent the vast majority of total revenue, generated from the company’s core digital products and services.
- Other revenue streams: public disclosures do not provide enough precision to assign a reliable percentage split across smaller categories such as service, licensing, or related support activities.
The most striking operating trend is scale: annual revenue rose from a very low base a few years ago to more than $7 million in the latest fiscal year shown, while net income also increased materially. Gross profit remains high in absolute terms, which is typical of software businesses, but operating expenses also climbed sharply as the company expanded.
The financial flow over the past few years points to a business that moved from negligible scale to meaningful profitability very quickly. Revenue, gross profit, and net income all improved substantially, although the latest period also shows a sizable increase in cost of revenue and operating expenses, suggesting that the next question is not only growth, but how durable that growth is.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Application | |
| Market Cap ⓘ | $3.64B | |
| Beta ⓘ | 0.93 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 0.92 | 29.95 |
| FCF Yield ⓘ | N/A | 4.22% |
| Dividend Yield ⓘ | N/A | 1.30% |
| EBIT / EV ⓘ | N/A | 2.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.40% | 15.80% |
| RPS Growth (5Y CAGR) ⓘ | 301.30% | 8.55% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -11.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.39% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.72% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 7.73% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.36% |
| ROIC (5Y Median) ⓘ | N/A | 8.32% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.46 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.28 |
| Net Debt / Assets ⓘ | N/A | 3.44% |
| EBITDA / Interest ⓘ | N/A | 12.67 |
| Operating Margin (Latest) ⓘ | N/A | 9.81% |
| Operating Margin (5Y Median) ⓘ | N/A | 8.50% |
| Debt to Equity (Latest) ⓘ | N/A | 33.33% |
| Profit Margin (Latest) ⓘ | 5.86% | 7.15% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +900.00% | +49.46% |
| 12M Return (excl. last month) ⓘ | +133.33% | +16.51% |
| 6M Return ⓘ | -9.68% | +24.29% |
| Price vs. 200-Day MA ⓘ | -1.06% | +4.74% |
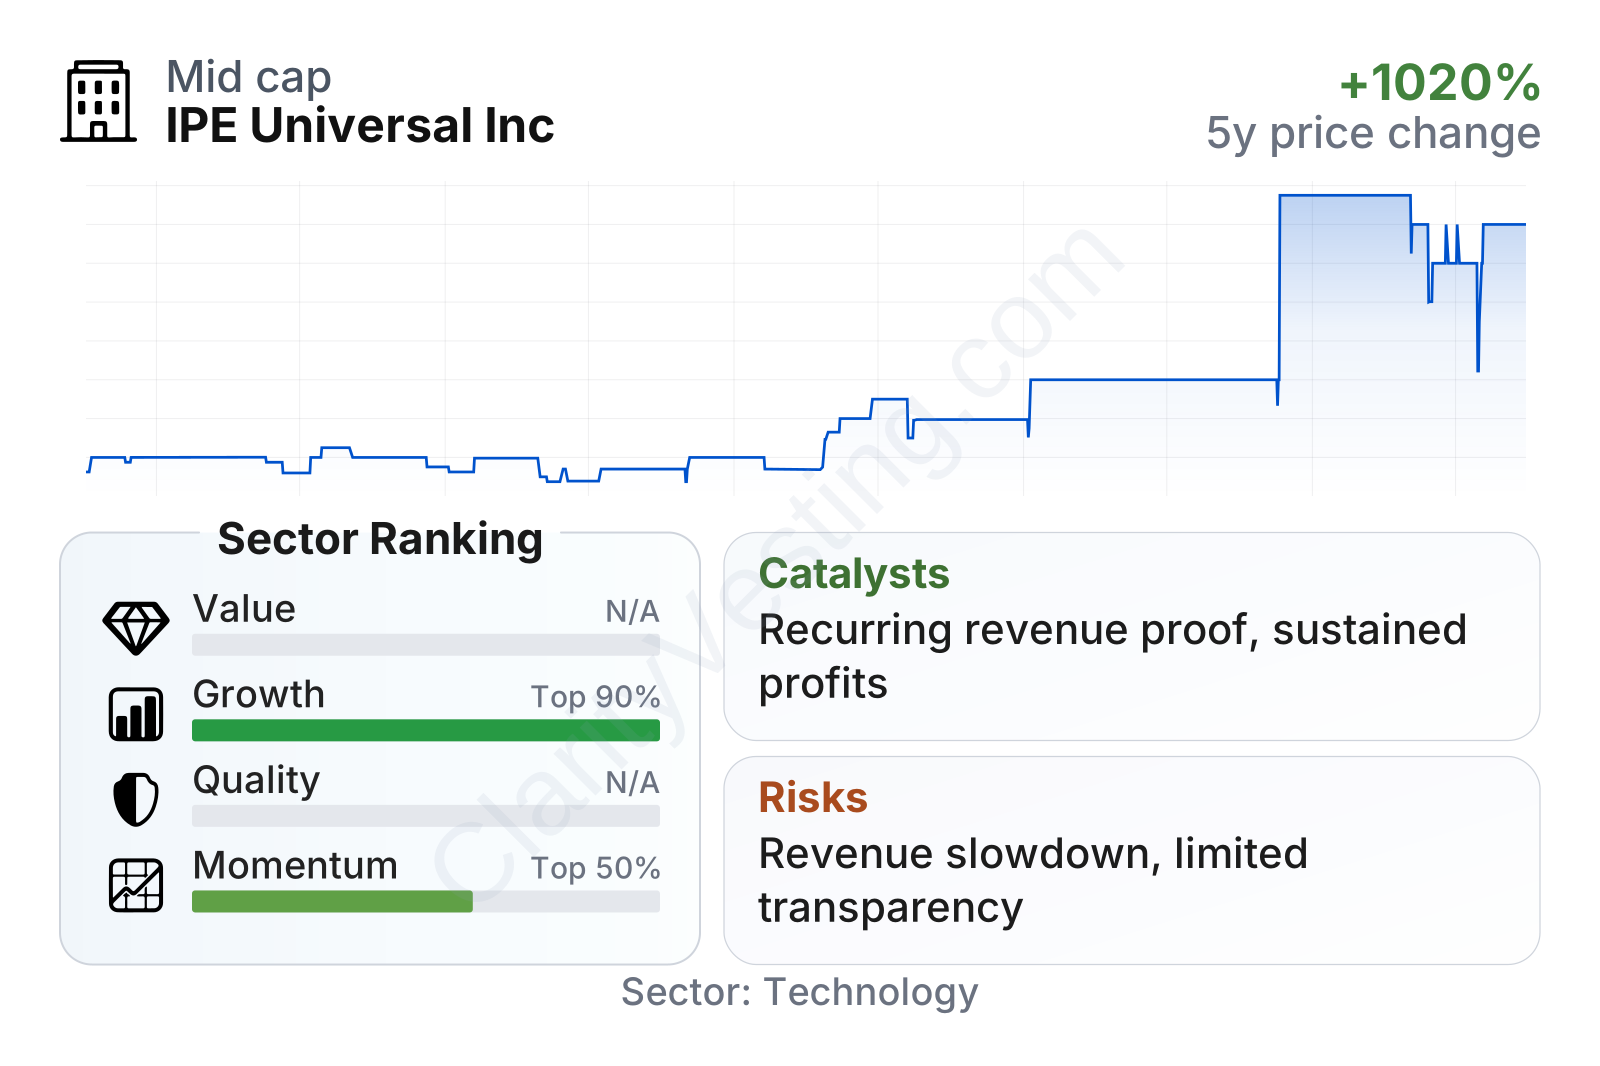
IPE Universal is still a relatively small public company by market standards, but no longer at the earliest development stage. The share price history has been highly volatile, with long periods of low trading levels followed by very sharp reratings. That kind of pattern usually signals that expectations can shift quickly as the market reacts to new revenue, profit, or corporate developments.
The latest factor profile is unusual. Growth ranks very well versus the broader software group, largely because longer-term revenue expansion has been exceptionally strong from a low starting point. Momentum is around the middle of the sector: the stock has delivered a very large multi-year return, but the shorter-term trend has cooled and the shares are trading close to their long-term average. Profitability is positive, yet the latest net margin is below the sector median on a trailing basis, which indicates that recent headline earnings strength should be judged alongside execution consistency.
Growth
Application software remains a structurally attractive market because companies across industries continue shifting more of their operations, customer interaction, and internal workflows onto digital platforms. That broad direction supports demand for specialized software vendors, especially if they can serve targeted niches or deploy products with limited incremental delivery cost.
For IPE Universal, the main positive element is simple: it has already shown that it can grow fast. Over the last several years, annual revenue moved from a very small base to a level that is now visible at public-market scale, and recent five-year revenue-per-share growth is far above the sector median. That suggests the company has not only expanded, but has done so fast enough to stand out even in a sector where high growth is common.
The more nuanced point is that recent year-over-year revenue growth has become far less steady. Earlier periods showed explosive gains, including several quarters with triple-digit expansion, but the latest quarter in the chart shows a sharp contraction. For long-term analysis, that matters more than the earlier surge because it raises the question of whether prior growth came from repeatable operating momentum, one-off contracts, changes in business mix, or timing effects.
The company’s strategy can still make sense for future growth if management is building a scalable software platform rather than a project-based service business. Software firms can grow efficiently when customer acquisition leads to recurring revenue, add-on sales, and high gross margins. If IPE Universal can prove that recent scale is durable and not temporary, the gap between its current size and much larger software peers leaves room for further expansion.
A strong catalyst would be evidence that the business is establishing repeatable revenue streams, larger customer relationships, or broader product adoption. Another meaningful catalyst would be continued profitability while revenue grows, because many smaller software firms can achieve one or the other, but not both at the same time. Recent company disclosures and filings should therefore be watched mainly for signs of revenue quality, customer concentration changes, and whether the latest slowdown was temporary or the start of normalization.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


