Stock Analysis · Innospec Inc (IOSP)
Overview
Innospec Inc is a specialty chemicals company that formulates performance-critical ingredients used in fuels, personal care products, home care products, and industrial applications. Rather than selling commodity chemicals, the company focuses on smaller-volume, higher-value products that help customers improve performance, meet regulatory standards, or solve formulation problems. Its business is spread across several end markets, which helps reduce reliance on any single customer industry.
Based on the company’s recent annual reporting structure, revenue mainly comes from three operating segments.
- Performance Chemicals: approximately 42% of revenue. This is the largest segment and includes ingredients used in personal care, home care, agrochemical, mining, construction, and industrial markets.
- Fuel Specialties: approximately 40% of revenue. This business sells fuel additives used to improve engine performance, fuel stability, and emissions characteristics in diesel, marine, and other fuel applications.
- Oilfield Services: approximately 18% of revenue. This segment provides specialty chemicals and related services for drilling, completion, and production activities in the energy industry.
That mix matters because it gives Innospec a balance between consumer-linked chemical demand, transportation-related additives, and energy exposure. It is not a pure-play on one industry cycle, although each segment still has its own swings in demand, pricing, and raw material costs.
The business model also shows a clear pattern: large revenue passes through significant input costs, but the company has historically preserved a meaningful gross profit pool through formulation know-how, technical support, and niche positioning. Revenue peaked in 2022, then eased in 2023 through 2025, while profitability remained positive overall despite a sharp earnings dip in 2024.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $2.38B | |
| Beta ⓘ | 0.92 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 19.94 | 17.61 |
| P/B Ratio ⓘ | 1.76 | 1.77 |
| FCF Yield ⓘ | 2.72% | 5.87% |
| Dividend Yield ⓘ | 1.83% | 2.06% |
| EBIT / EV ⓘ | 6.44% | 6.43% |
| PEG ⓘ | 0.66 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.80% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 4.49% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | -22.56% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 6.19% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -1.02% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | 12.93% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | 10.00% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.00% | 9.31% |
| ROA (Latest) ⓘ | 6.67% | 4.94% |
| ROIC (5Y Median) ⓘ | 12.73% | 7.91% |
| ROA (5Y Median) ⓘ | 6.54% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | -1.45 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.91 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -1.18 | 0.91 |
| Net Debt / Assets ⓘ | -10.96% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 11.93 |
| Operating Margin (Latest) ⓘ | 7.57% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 8.95% | 11.86% |
| Debt to Equity (Latest) ⓘ | 3.57% | 40.43% |
| Profit Margin (Latest) ⓘ | 6.60% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $64.90M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -1.71% | +65.06% |
| 12M Return (excl. last month) ⓘ | +9.74% | +36.05% |
| 6M Return ⓘ | +32.08% | +1.89% |
| Price vs. 200-Day MA ⓘ | +16.61% | +1.03% |
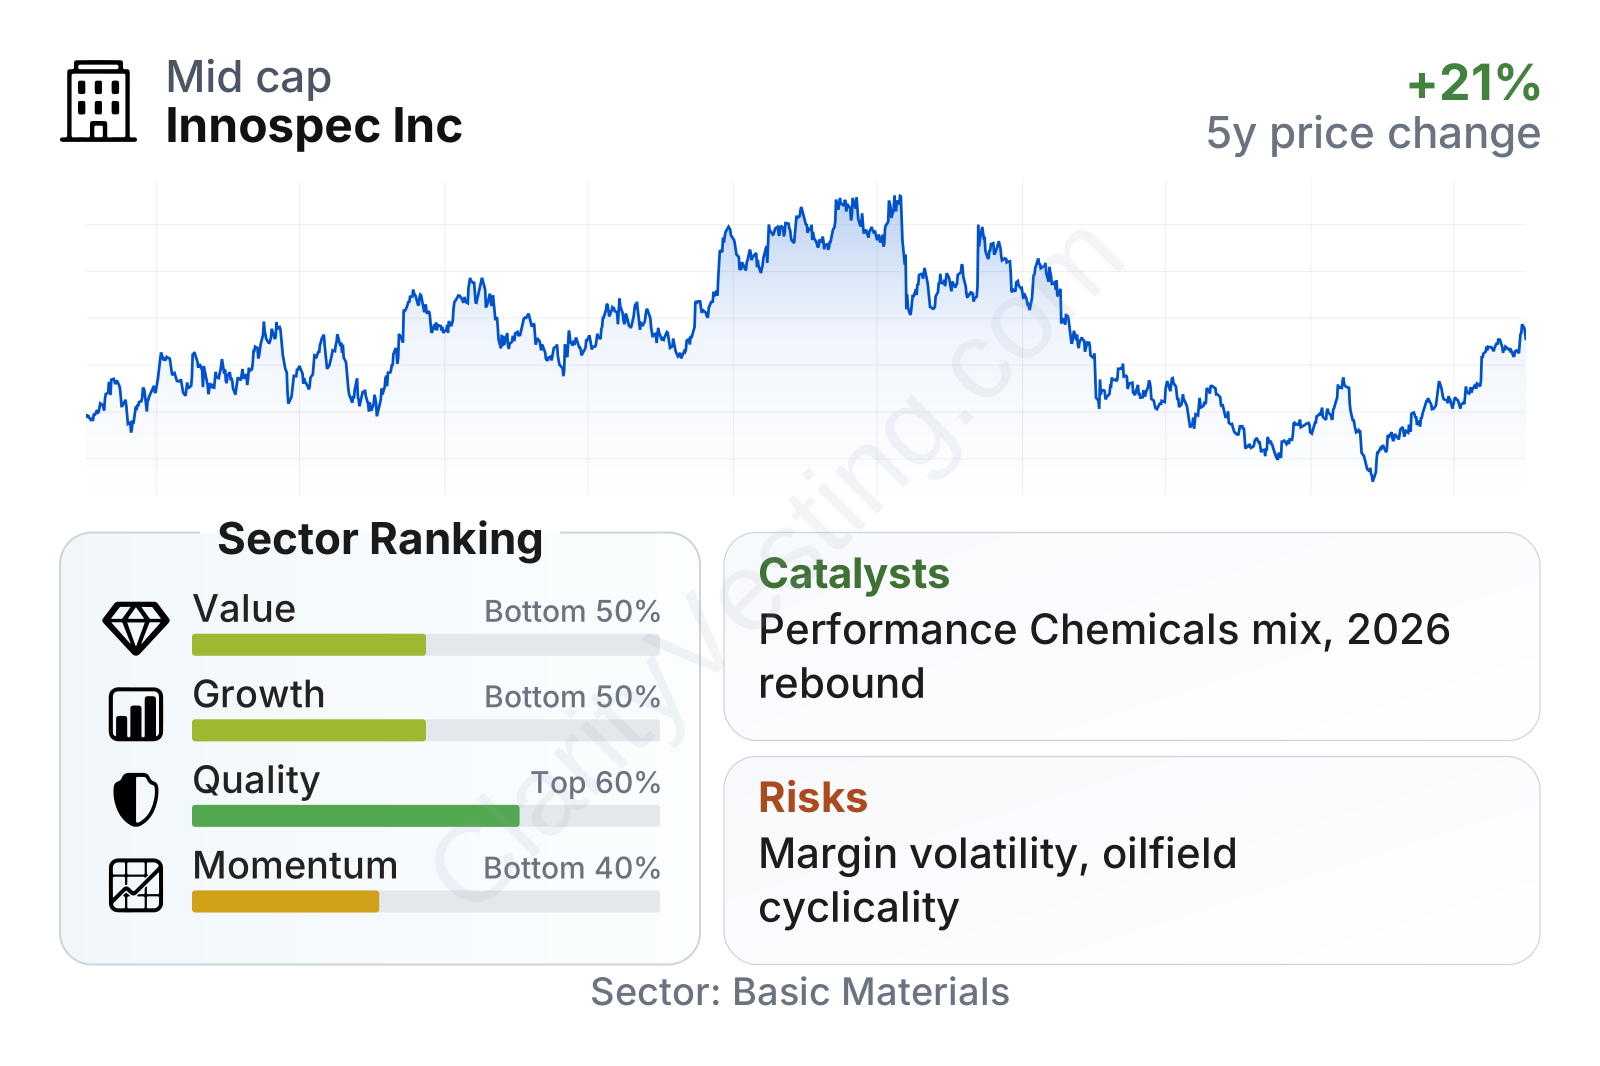
Innospec sits in the mid-cap range, with a share price history that has been uneven over the last several years. The stock rose strongly into 2024, then corrected sharply before partly recovering in 2026. That pattern fits a company whose end markets are solid but not immune to industrial slowdowns and earnings volatility.
The overall metrics profile is mixed. Quality indicators are generally better than much of the sector, supported by strong returns on assets and invested capital over time, plus an unusually conservative balance sheet. Growth measures are less convincing because earnings per share have been volatile even though revenue per share and free cash flow have grown over a longer period. Valuation is not stretched on conventional earnings multiples, but it also does not screen as obviously cheap relative to the broader chemicals space.
Growth
Innospec operates in parts of the chemicals industry that benefit from durable long-term demand. Personal care and home care ingredients tend to grow with population, product innovation, and premium formulations. Fuel additives are supported by tightening efficiency and emissions requirements, even in mature fuel markets. Oilfield Services is the most cyclical area, but it can still benefit when customers require more specialized chemistry to improve well productivity or operational efficiency.
The company’s strategy makes sense for long-term expansion because it is centered on specialized formulations rather than bulk chemical capacity. That usually means closer customer relationships, more technical selling, and somewhat better protection from pure price competition. Management has also emphasized innovation and targeted investments in higher-value applications, especially in Performance Chemicals, which appears to be the clearest engine for steady compounding if execution remains solid.
Recent sales trends show why the growth case is not straightforward. Revenue growth was exceptionally strong in 2022, then turned negative through much of 2023 to 2025 before improving again in early 2026. The latest year-over-year reading has moved back into positive territory and is slightly ahead of the sector median, which suggests the downturn may be easing. Even so, the broader pattern still looks cyclical rather than consistently high growth.
Cash generation is another important point. Free cash flow expanded sharply from 2022 levels and, despite cooling from its 2024 peak, remains well above where it stood several years ago. That is encouraging because it suggests the company can still convert earnings into cash across a full cycle. The latest trailing free cash flow is modest relative to the company’s market value, but the five-year growth rate is clearly stronger than the sector median.
A practical catalyst for future growth is the company’s exposure to regulation-driven product demand. Fuel additives and specialty ingredients often become more valuable when customers need to comply with evolving environmental and performance standards. Another catalyst is product mix: if Performance Chemicals continues to grow faster than the rest of the portfolio, overall revenue quality could improve even without dramatic top-line acceleration.
Recent company updates have also pointed to improving conditions after a softer period, particularly with better year-over-year revenue momentum in 2026. That does not change the cyclical nature of the business, but it does indicate that the company may be moving out of a down phase rather than deeper into one.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


