Stock Analysis · Inspire Medical Systems Inc (INSP)
Overview
Inspire Medical Systems develops and sells an implantable device used to treat obstructive sleep apnea, a condition in which breathing repeatedly stops during sleep because the airway becomes blocked. Its flagship therapy, marketed as Inspire, is designed for patients who cannot tolerate or do not benefit from traditional CPAP machines. The system includes a small implanted pulse generator, sensing and stimulation leads, and a handheld remote used by the patient to activate therapy during sleep.
The company’s business model is relatively simple compared with many diversified medical device companies. Revenue is driven primarily by sales of the Inspire system and by the procedures and care pathway surrounding that therapy. Based on company filings, the revenue mix is overwhelmingly concentrated in one platform.
- Inspire system sales in the United States: approximately 90% to 95% of total revenue. This includes the implantable generator, leads, and other components used in the procedure. The U.S. remains the core market because physician adoption, reimbursement coverage, and patient awareness are much more developed there.
- International sales: approximately 5% to 10% of total revenue. This comes from sales outside the U.S., mainly in selected European and other international markets where the company is still expanding its commercial footprint.
- Other revenue: currently minimal. Inspire is not meaningfully diversified into large adjacent product lines, which makes operating performance highly tied to one therapy category.
That concentration cuts both ways. It gives the company a clear identity in a large underpenetrated medical need, but it also means execution around one product, one treatment pathway, and one reimbursement environment matters a great deal. Over the last several years, revenue scaled rapidly while gross profit also expanded strongly, showing that the company has been able to translate adoption into a more profitable operating model.
The business has moved from losses to profitability as revenue rose from roughly the low-$200 million range in 2021 to more than $900 million in 2025. Gross profit has remained strong, while selling and administrative spending is still the largest operating cost, which is typical for a company still building physician networks and patient awareness.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.97B | |
| Beta ⓘ | 0.73 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 14.99 | 24.79 |
| P/B Ratio ⓘ | 2.46 | 3.08 |
| FCF Yield ⓘ | 5.95% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 3.86% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -7.60% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 37.55% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 32.95% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.62% | 3.24% |
| ROA (Latest) ⓘ | 15.58% | 3.01% |
| ROIC (5Y Median) ⓘ | -5.88% | 4.60% |
| ROA (5Y Median) ⓘ | -3.41% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | -1.50 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | -1.19 | 1.00 |
| Net Debt / Assets ⓘ | -10.66% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | 7.33% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -6.45% | 7.38% |
| Debt to Equity (Latest) ⓘ | 3.52% | 28.58% |
| Profit Margin (Latest) ⓘ | 15.03% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $117.09M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -53.55% | +42.80% |
| 12M Return (excl. last month) ⓘ | -7.60% | +18.50% |
| 6M Return ⓘ | +23.80% | +7.57% |
| Price vs. 200-Day MA ⓘ | +17.05% | +5.12% |
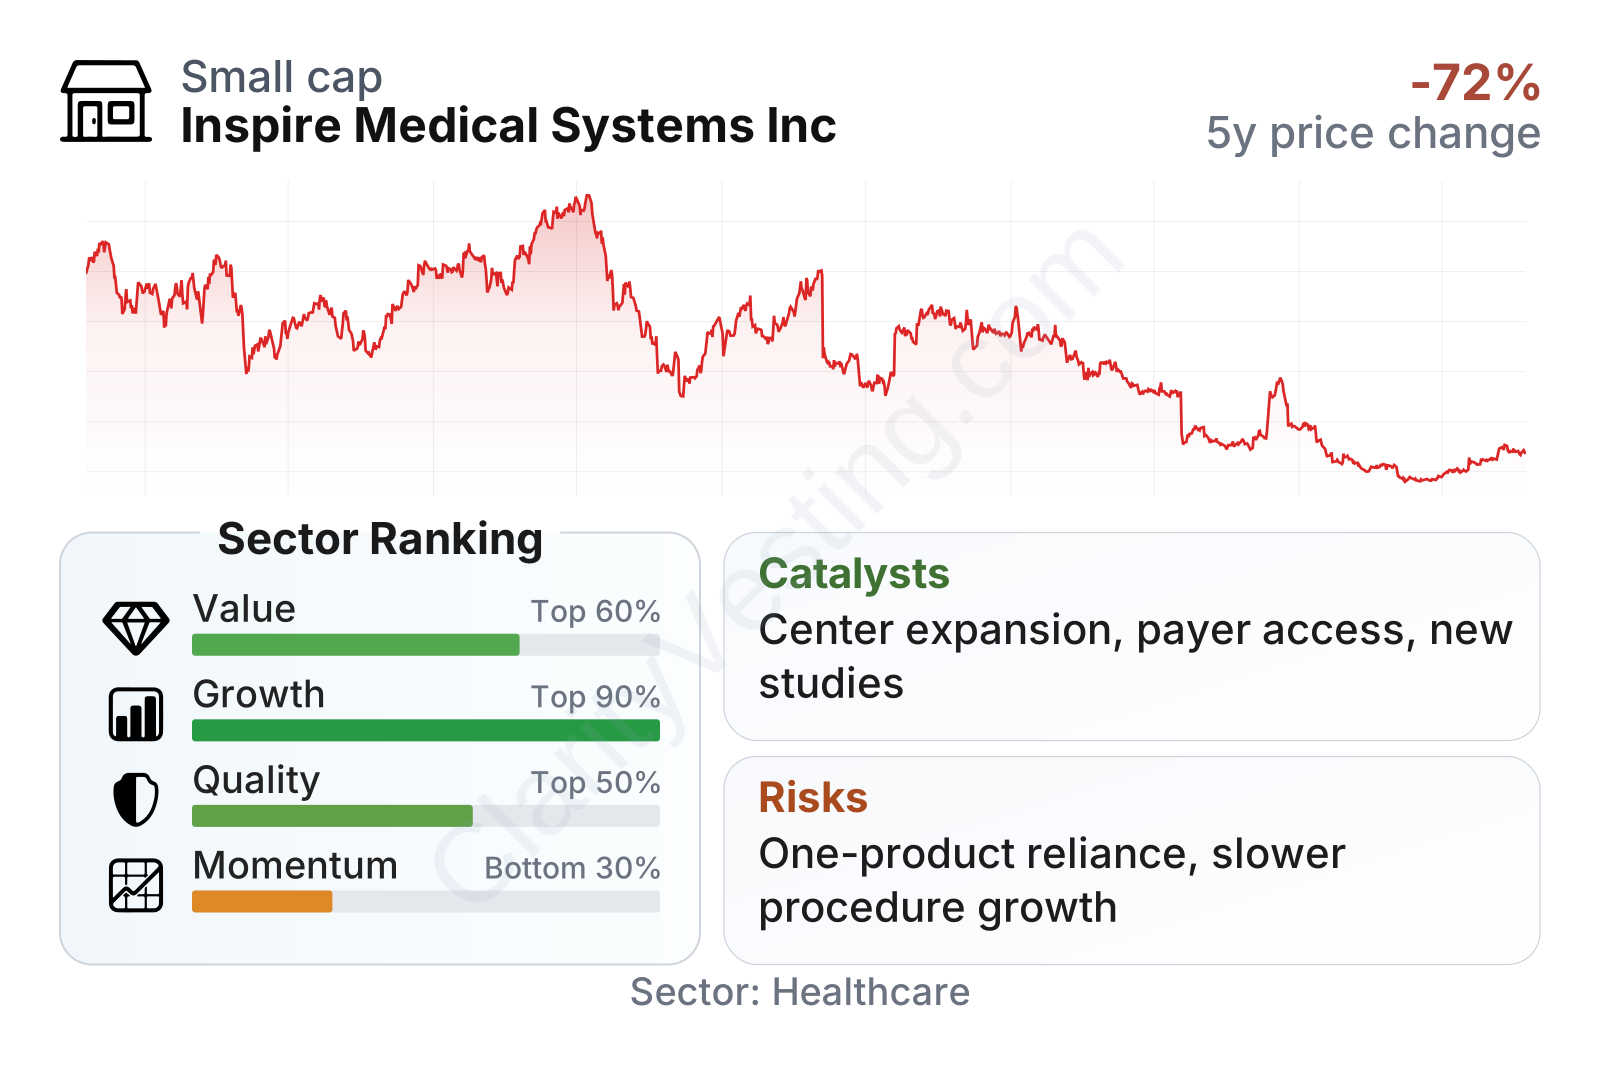
Inspire stands out for strong long-term growth and a balance sheet that is much cleaner than the sector median. Profitability and returns on capital have improved sharply, and free cash flow generation is now meaningfully positive. The weaker area is recent momentum in the underlying business, with short-term revenue growth turning negative even though the share price has partially rebounded from very depressed levels.
The stock’s trading history shows how sentiment has shifted. After reaching much higher levels in earlier years, the share price fell steeply through 2025 and into 2026. That decline came even as the company became profitable, which suggests the market has become much more cautious about future growth than about current earnings quality alone.
Growth
Inspire operates in a healthcare niche with a large structural opportunity. Obstructive sleep apnea is common, diagnosis rates are still incomplete, and many patients struggle with CPAP adherence. That creates room for alternative treatments with better real-world acceptance. The company’s therapy sits in a category that benefits from several favorable long-term trends: aging populations, rising obesity rates, improving diagnosis of sleep disorders, and greater physician willingness to use device-based solutions for chronic conditions.
The company’s strategy for future growth is easy to understand. It is trying to expand the number of implanting centers, increase the number of trained physicians, improve patient identification, and broaden insurance reimbursement. In a business like this, growth does not depend only on product demand. It also depends on whether hospitals, sleep specialists, ENT surgeons, and payers all support the treatment pathway. Inspire has spent heavily to build that infrastructure, which helps explain the large selling and administrative expense base.
The long-term trend has been impressive, with annual revenue compounding rapidly over the last five years. However, the pace has clearly slowed. Earlier periods showed growth rates well above 20% and, at times, far above that level, while the most recent year-over-year reading turned slightly negative. For a company previously valued as a high-growth medical device name, that deceleration is a major issue because expectations were built around sustained fast expansion.
One encouraging point is cash generation. Free cash flow has turned decisively positive and improved materially over the last few years. That matters because it shows the business is no longer relying on growth alone to justify its profile. It is beginning to demonstrate that scale can produce real cash, not just revenue growth.
A meaningful catalyst is the company’s continued effort to widen patient eligibility and make the therapy easier to access through additional clinical evidence, center expansion, and physician adoption. Another important opportunity is international expansion, although this is still much smaller than the U.S. business today. If Inspire can deepen penetration in its existing market while also adding new geographies, the addressable revenue base could continue to expand for many years.
Recent company communications have also highlighted ongoing work around next-generation products, clinical studies, and commercial expansion. For a medical device company, these are important because they can support better physician confidence, stronger payer acceptance, and a broader candidate pool over time. The opportunity remains significant, but the key question has shifted from whether the therapy works commercially to how fast adoption can continue from here.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


