Stock Analysis · InnovAge Holding Corp (INNV)
Overview
InnovAge Holding Corp is a healthcare company focused on caring for older adults through the PACE model, which stands for Program of All-Inclusive Care for the Elderly. PACE is designed for people who are typically age 55 or older, qualify for nursing-home-level care, and want to remain living at home rather than move into an institution. InnovAge coordinates medical care, prescription drugs, rehabilitation, home care, transportation, and social support through local care centers and interdisciplinary teams.
That makes InnovAge less like a traditional hospital operator and more like a specialized senior-care platform built around managing complex, high-cost patients under a capitated payment model. In simple terms, the company generally receives a fixed monthly payment per participant from government programs and then manages the participant’s care within that budget.
Based on company filings, revenue is overwhelmingly concentrated in one operating model rather than many separate business lines. The main sources are:
- PACE service revenue: approximately 99%+ of total revenue. This includes capitated payments tied mainly to Medicare and Medicaid coverage for enrolled participants, along with the full range of care coordination and clinical services provided under the program.
- Other revenue: less than 1% of total revenue. This is a small category and is not a meaningful driver of the business compared with PACE operations.
Within that revenue stream, the real economic drivers are participant enrollment growth, the reimbursement rates set by Medicare and Medicaid, and the company’s ability to control medical costs while maintaining quality and regulatory compliance.
The broad financial pattern has been improving. Revenue has risen meaningfully over the last few years, and operating performance appears to have strengthened sharply in the most recent period. At the same time, the business still carries a very thin bottom line, showing that growth alone is not enough; execution on cost control remains central.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Care Facilities | |
| Market Cap ⓘ | $1.24B | |
| Beta ⓘ | 0.15 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 6.08 | 3.08 |
| FCF Yield ⓘ | 4.07% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 0.86% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 18.30% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 9.06% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -11.69% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.26% | 3.24% |
| ROA (Latest) ⓘ | -0.48% | 3.01% |
| ROIC (5Y Median) ⓘ | -4.00% | 4.60% |
| ROA (5Y Median) ⓘ | -3.79% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | -1.08 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | -0.35 | 1.00 |
| Net Debt / Assets ⓘ | -1.96% | 5.45% |
| EBITDA / Interest ⓘ | 7.34 | 9.64 |
| Operating Margin (Latest) ⓘ | 1.02% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -1.89% | 7.38% |
| Debt to Equity (Latest) ⓘ | 36.91% | 28.58% |
| Profit Margin (Latest) ⓘ | -0.26% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $50.48M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +51.18% | +42.80% |
| 12M Return (excl. last month) ⓘ | +119.28% | +18.50% |
| 6M Return ⓘ | +10.18% | +7.57% |
| Price vs. 200-Day MA ⓘ | +1.39% | +5.12% |
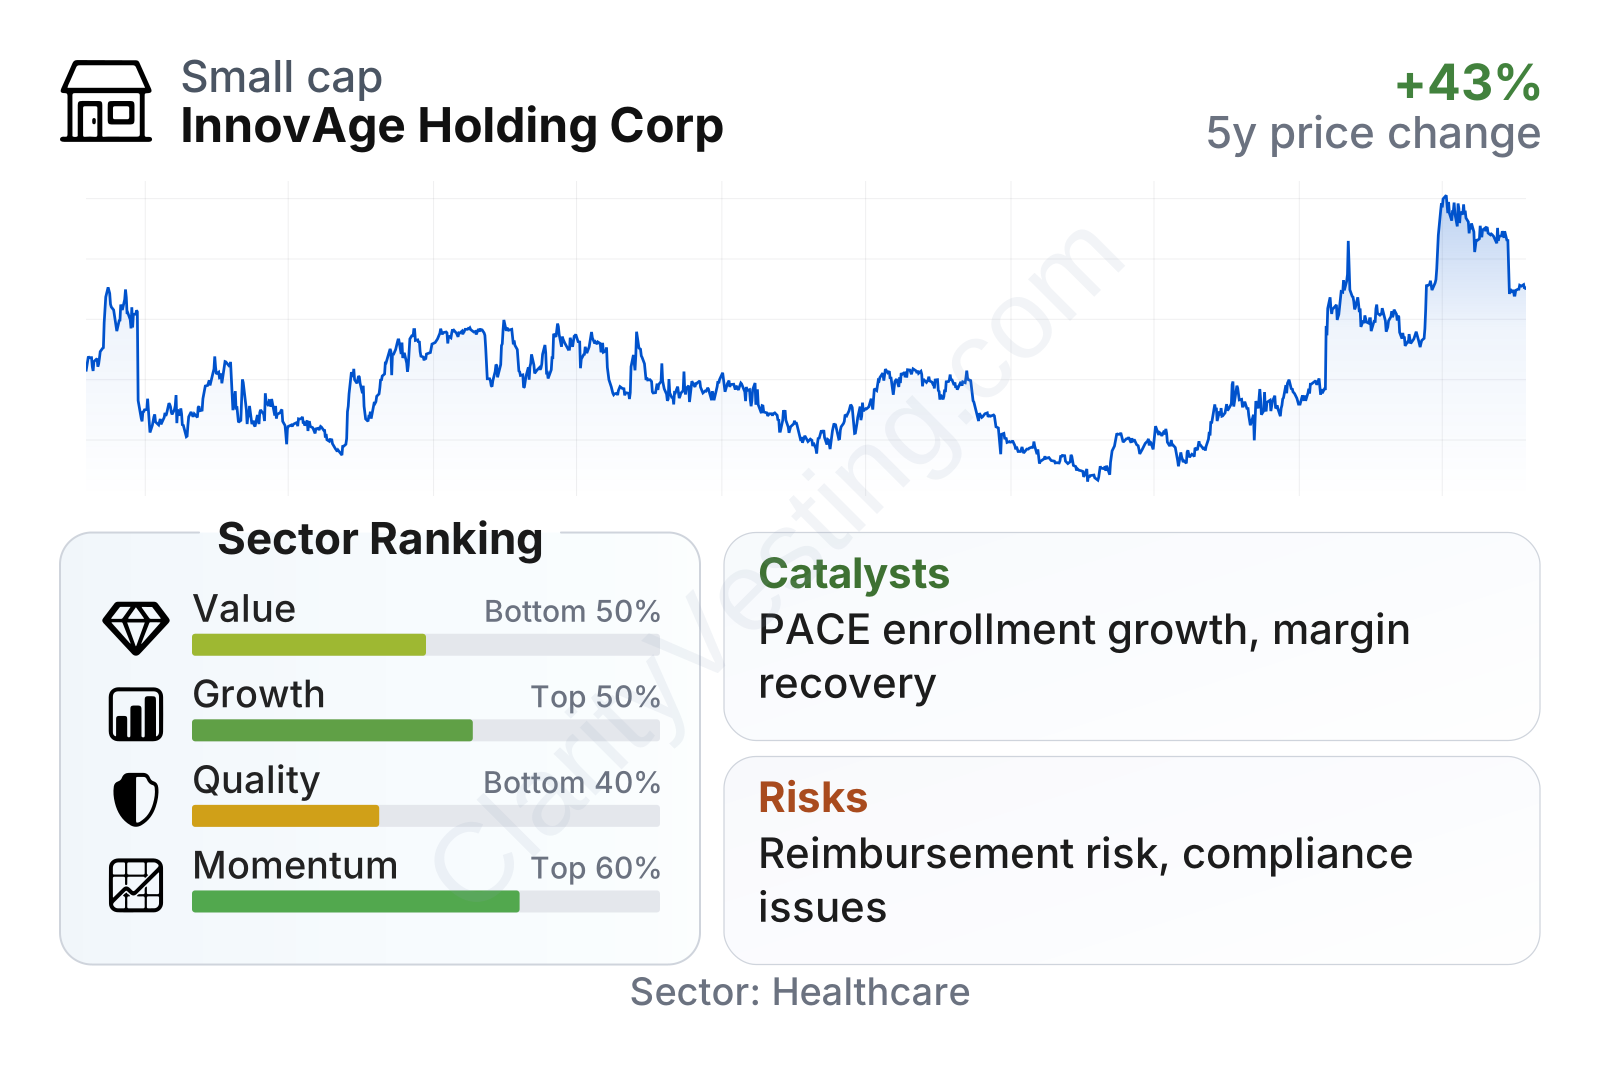
InnovAge is a mid-sized healthcare company with unusually low share-price volatility for a small-cap name, as shown by a beta well below 1. In the factor view, growth and momentum rank in the upper half of the healthcare sector, while value and quality sit in the lower half. That combination usually points to a company where the market is recognizing improving business trends, but where profitability and long-term consistency are still not fully established.
The table also suggests a mixed profile under the surface. Revenue growth is clearly ahead of the sector median, and free cash flow generation has improved. However, profitability metrics remain weak compared with many healthcare peers, and the stock does not screen as obviously cheap on balance-sheet multiples.
Growth
InnovAge operates in a part of healthcare with strong long-term demand support. The United States continues to age, and policymakers have clear reasons to favor models that keep frail seniors at home when possible rather than in more expensive institutional settings. That gives PACE a structural tailwind: it addresses both a social need and a cost-management need.
The company’s strategy also makes sense in that context. Instead of building a broad healthcare empire, InnovAge is staying focused on a single model where scale, local relationships, clinical coordination, and regulatory know-how matter. If it can add new centers, expand enrollment in existing markets, and improve care efficiency, growth can come from both a larger participant base and better unit economics.
Recent revenue growth has been notably stronger than the sector median, and the trend has become more consistent after a weaker period in 2022 and early 2023. By mid-2026, year-over-year revenue growth was running around 20%, which is strong for a care-delivery company that depends on operational buildout rather than one-time product launches. That is a sign that enrollment and reimbursement momentum have likely been moving in the right direction.
Cash generation has also improved materially. Free cash flow was negative in 2023 and 2024, but it turned positive and expanded into 2025 and 2026. That matters because healthcare service businesses can report accounting improvements before cash economics truly strengthen. Positive free cash flow suggests InnovAge is moving beyond simple top-line recovery and showing more practical financial progress.
A notable catalyst is the operating turnaround visible in the most recent annual figures. Revenue approached $1.0 billion for fiscal 2026, and operating income turned positive after several years of operating losses. For a company that had been rebuilding after regulatory and execution issues, that shift is important. It suggests the platform may now be benefiting from scale again rather than being weighed down by fixed costs and compliance remediation.
Another potential opportunity comes from the fact that PACE remains a relatively underpenetrated care model in the U.S. compared with the size of the eligible senior population. If federal and state agencies continue supporting home-based, integrated elder care, the addressable market could expand over time without requiring InnovAge to move beyond its core specialization.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


