Stock Analysis · Indivior PLC (INDV)
Overview
Indivior PLC is a specialty pharmaceutical company focused on treatments for substance use disorders and serious mental health conditions. Its best-known business is medication for opioid use disorder, an area where it has built deep clinical experience, commercial relationships, and brand recognition. The company operates globally, but the United States is the core market and the main driver of results.
Revenue is concentrated in a small number of products, with SUBLOCADE clearly dominating the mix. Based on the company’s latest annual reporting and recent quarterly updates, the business can be summarized as follows:
- SUBLOCADE: approximately 70% to 75% of total revenue. This is a once-monthly injectable treatment for moderate to severe opioid use disorder and is the company’s main growth engine.
- PERSERIS: approximately 8% to 10% of revenue. This is a monthly injectable treatment for schizophrenia, giving Indivior exposure beyond addiction medicine.
- SUBOXONE film and related opioid use disorder products: approximately 10% to 15% of revenue. This legacy business remains meaningful, although it is no longer the main source of expansion.
- Other products and markets: approximately 5% to 10% of revenue. This includes smaller products and international sales.
The business mix has been improving from a long-term perspective. The company has become less dependent on older sublingual opioid dependence products and more dependent on long-acting branded medicines, especially SUBLOCADE. That shift matters because injectable treatments tend to have stronger pricing power, better differentiation, and lower direct generic pressure than older oral or film-based products.
The multi-year financial picture also shows a business that has rebuilt profitability after a difficult stretch. Revenue has risen from under $800 million in 2021 to above $1.2 billion in 2025, while operating income recovered sharply after losses in 2022 and 2023. Selling costs are still significant, but the recent rebound suggests the current product mix is more favorable than it was a few years ago.
The broad pattern is encouraging: revenue has grown steadily, gross profit remains strong, and operating earnings improved materially in 2025 after a period weighed down by litigation, launch spending, and business transition costs.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $4.23B | |
| Beta ⓘ | 1.11 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.85 | 24.06 |
| P/B Ratio ⓘ | N/A | 3.08 |
| FCF Yield ⓘ | -2.62% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 9.29% | 0.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 13.60% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 17.21% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | N/A | 3.95% |
| Margin Growth (5Y Trend) ⓘ | -4.39% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 160.13% | 3.29% |
| ROA (Latest) ⓘ | 26.80% | 3.02% |
| ROIC (5Y Median) ⓘ | 10.52% | 4.75% |
| ROA (5Y Median) ⓘ | 0.13% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 0.68 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.55 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 0.66 | 0.99 |
| Net Debt / Assets ⓘ | 23.28% | 5.33% |
| EBITDA / Interest ⓘ | 16.00 | 9.63 |
| Operating Margin (Latest) ⓘ | 31.53% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 4.63% | 7.80% |
| Debt to Equity (Latest) ⓘ | -244.71% | 28.99% |
| Profit Margin (Latest) ⓘ | 26.75% | 3.60% |
| Free Cash Flow (Latest) ⓘ | -$111.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +61.77% | +37.48% |
| 12M Return (excl. last month) ⓘ | +42.34% | +20.85% |
| 6M Return ⓘ | +15.43% | +9.73% |
| Price vs. 200-Day MA ⓘ | -0.98% | +4.69% |
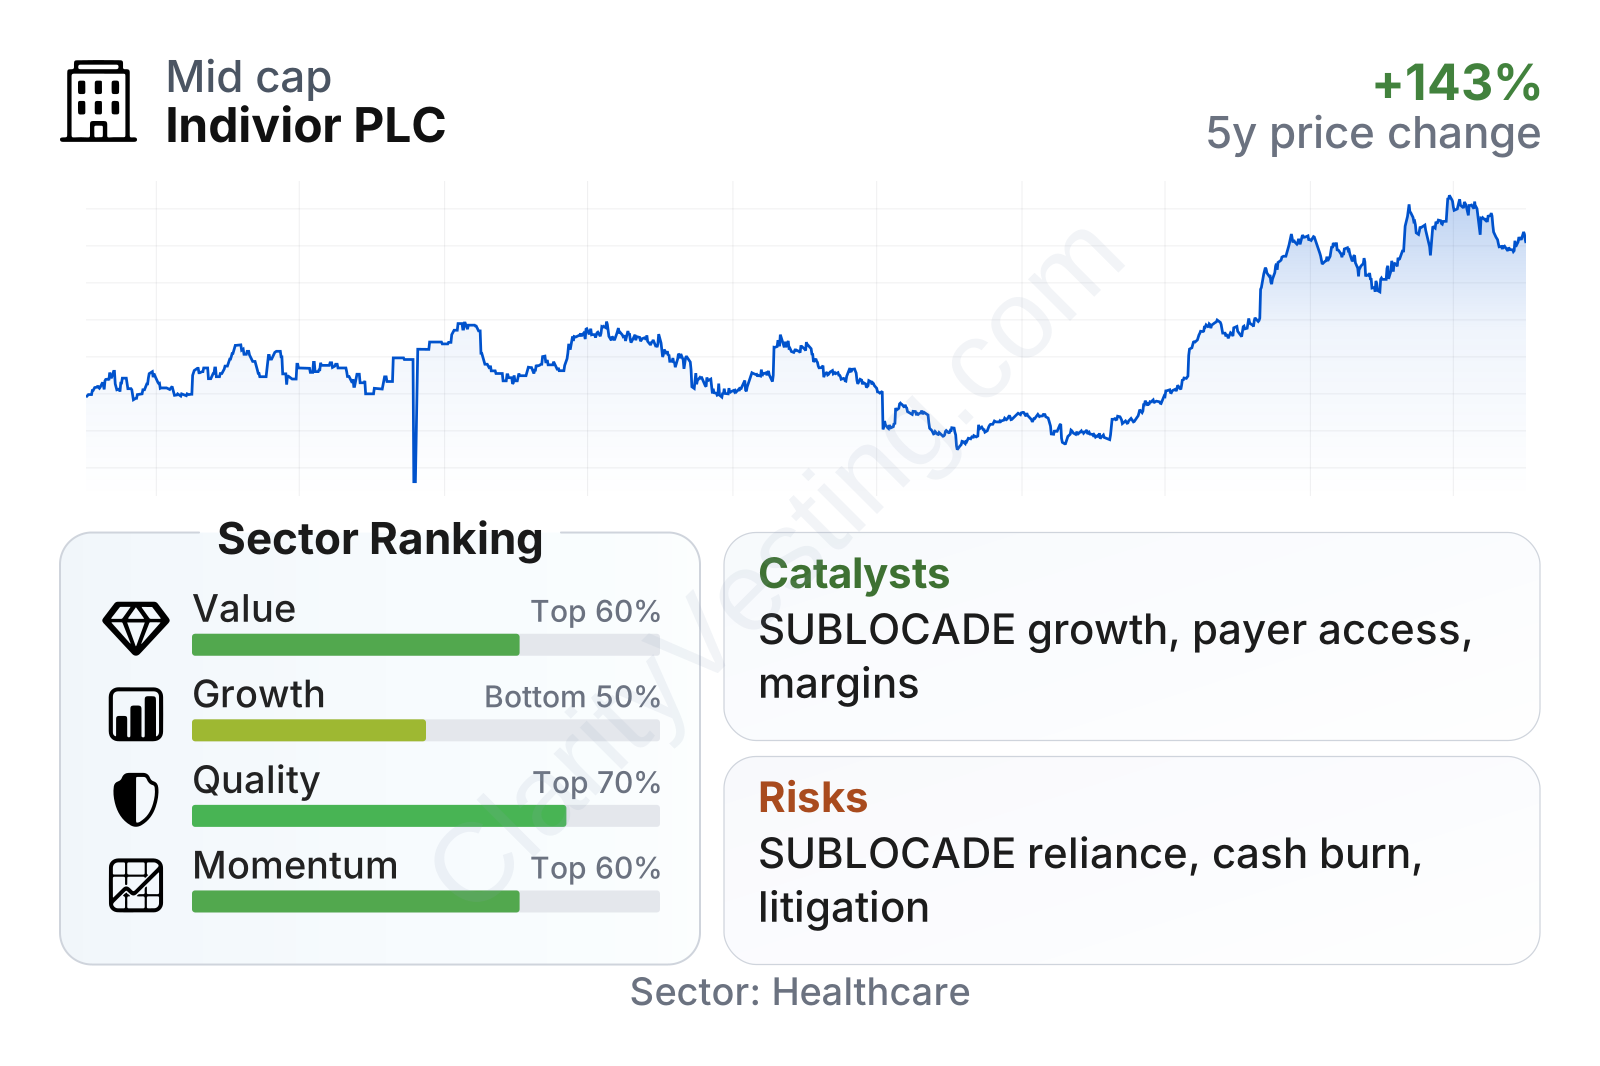
Indivior is a mid-sized healthcare company with above-average share price volatility for the sector. The metrics show a mixed but interesting profile: valuation appears lighter than the sector median on earnings, profitability is currently strong, and revenue growth has been ahead of many peers. At the same time, free cash flow is weak on a trailing basis, which is an important reminder that accounting profits and cash generation are not moving in perfect sync.
The quality indicators are particularly notable. Operating margin and profit margin are well above the healthcare sector median, and interest coverage looks solid. Growth metrics are less uniformly strong than the headline revenue trend suggests because margin progression over the last five years has been uneven. In other words, the company is growing, but it has not yet delivered a perfectly smooth compounding profile.
Growth
Indivior operates in a sector with long-term structural demand. Opioid use disorder remains a major public health issue, especially in the United States, and healthcare systems continue to search for treatments that improve adherence and reduce relapse risk. Long-acting injectable therapies fit that need well because they can be easier to supervise than daily medication and may improve treatment continuity.
The company’s strategy is logical for future expansion. Rather than relying mainly on mature products, management has pushed the portfolio toward differentiated, branded, long-acting treatments. SUBLOCADE is central to that plan, and PERSERIS provides a second growth platform in psychiatry. If the company can keep expanding physician adoption, treatment site access, and payer coverage, this positioning could continue to support revenue growth.
The recent growth trend has been favorable overall. Revenue growth moved at double-digit rates for much of 2023 and parts of 2024, cooled meaningfully in early 2025, and then reaccelerated into late 2025 and the first half of 2026. That pattern suggests demand has not been linear, but it does show that the company still has meaningful commercial momentum.
Cash generation is a more cautious part of the picture. Free cash flow has swung sharply between positive and negative territory over the last few years, including another negative reading in the latest trailing period. For a long-term business case, sustained cash conversion would be more reassuring than revenue growth alone, so this is one of the main items to monitor.
A major catalyst is the continued rollout of SUBLOCADE in a market where treatment access is still far from saturated. Another positive factor is the broader policy and clinical environment: public attention on addiction treatment remains high, and there is ongoing pressure to improve access to evidence-based therapies. In addition, the company has continued to communicate commercial progress and a stronger earnings profile in its more recent reporting, which helps support the idea that the business transition is moving in the intended direction.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


