Stock Analysis · Incyte Corporation (INCY)
Overview
Incyte Corporation is a biotechnology company focused on discovering, developing, and commercializing medicines, mainly in oncology and inflammation-related diseases. In simple terms, it makes drugs for serious diseases such as blood cancers, solid tumors, and chronic immune conditions, while also partnering with larger pharmaceutical companies in some markets and programs.
The business is still centered on a few key medicines, but it has broadened over time from one main product into a more diversified portfolio. The largest contributor remains Jakafi, a treatment used in myelofibrosis, polycythemia vera, and graft-versus-host disease in the United States. Outside the U.S., Incyte also earns royalties from Novartis on Jakavi, the ex-U.S. brand of the same medicine. The company has added newer growth products including Opzelura, used in dermatology, and Pemazyre, used in oncology, alongside other smaller product and collaboration streams.
Based on recent annual reporting, Incyte’s revenue mix is approximately:
- Jakafi net product revenue: about 63% of total revenue. This is the company’s core U.S. medicine and still drives most operating profit.
- Jakavi royalties from Novartis: about 10%. These are royalty payments from sales outside the U.S.
- Opzelura net product revenue: about 6%. This includes the topical cream franchise in atopic dermatitis and vitiligo.
- Monjuvi product and royalty revenue: about 6% combined. This includes collaboration-related economics tied to the drug.
- Pemazyre net product revenue: about 4%.
- Other product revenues: about 2%. This includes smaller commercial products such as Iclusig and Niktimvo.
- Collaboration and contract revenue: about 9%. This includes milestone, license, and research-related payments from partners.
This structure matters because it shows both strength and concentration. Incyte already has meaningful commercial scale, but a large share of revenue still depends on Jakafi.
The financial flow over the last several years shows a company with very high gross profit and heavy but purposeful research spending. Revenue rose from roughly $3.0 billion in 2021 to more than $5.1 billion in 2025, while research and development remained unusually large even for biotech, reflecting an active pipeline and a strategy of reinvesting current cash generation into future products.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $22.99B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 14.45 | 25.42 |
| P/B Ratio ⓘ | 3.84 | 3.08 |
| FCF Yield ⓘ | 8.35% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 9.28% | 0.56% |
| PEG ⓘ | 10.82 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 37.70% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 17.48% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | 14.45% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 10.97% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 13.26% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 24.24% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 29.64% | 3.17% |
| ROA (Latest) ⓘ | 22.70% | 2.98% |
| ROIC (5Y Median) ⓘ | 12.54% | 4.56% |
| ROA (5Y Median) ⓘ | 9.47% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | -2.00 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | -3.79 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | -1.91 | 1.00 |
| Net Debt / Assets ⓘ | -50.10% | 5.06% |
| EBITDA / Interest ⓘ | 889.83 | 9.55 |
| Operating Margin (Latest) ⓘ | 33.85% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 19.17% | 7.33% |
| Debt to Equity (Latest) ⓘ | 0.60% | 26.68% |
| Profit Margin (Latest) ⓘ | 27.71% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $1.92B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +112.21% | +51.61% |
| 12M Return (excl. last month) ⓘ | +49.81% | +19.90% |
| 6M Return ⓘ | +20.87% | +10.10% |
| Price vs. 200-Day MA ⓘ | +8.51% | +6.44% |
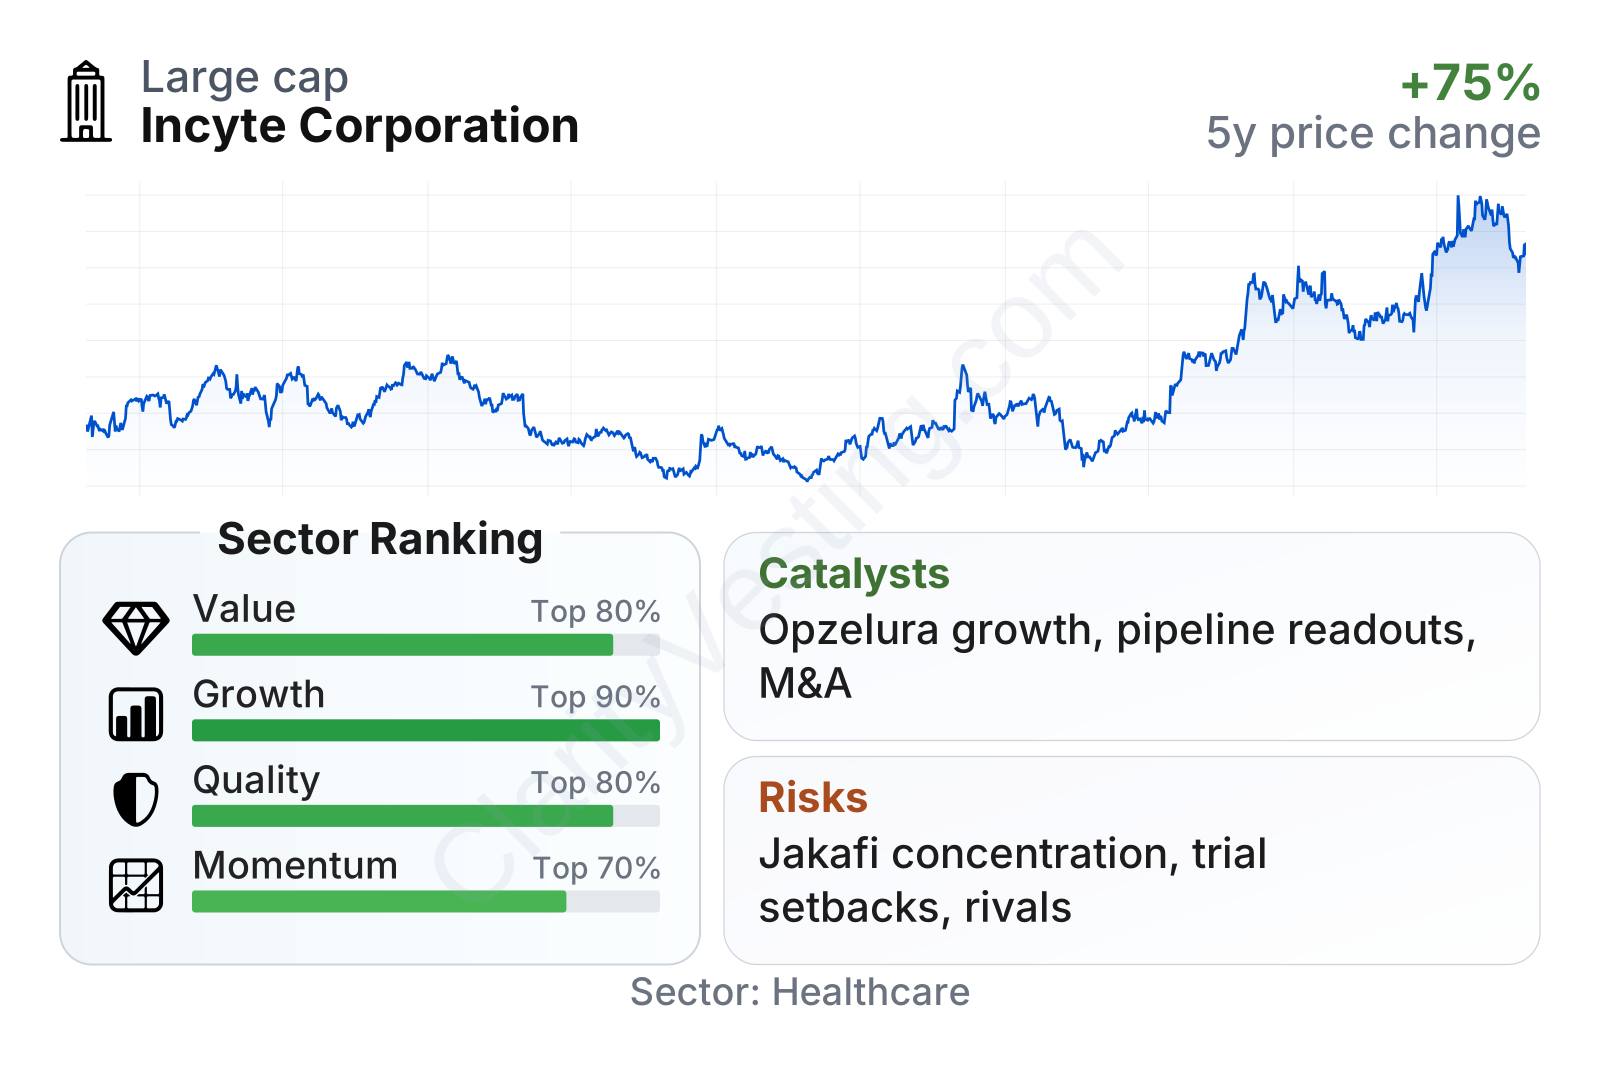
Incyte stands out as a large biotechnology company with a relatively defensive trading profile for the sector, reflected in a beta below 1. The broad picture from the latest metrics is strong growth, solid quality, and acceptable valuation. Growth ranks near the top of the healthcare peer group, helped by revenue expansion well above the sector median and strong multi-year gains in earnings and free cash flow. Quality is also notable: profitability is far above typical biotech levels, and the balance sheet remains exceptionally clean. Value is more mixed, but the earnings multiple is below the sector median while free cash flow yield is comfortably above it.
Growth
Biotechnology remains a growing sector over the long run because demand for cancer and immune-disease treatments tends to expand with aging populations, improved diagnosis, and broader access to specialty medicines. Within that sector, Incyte is active in attractive niches: blood cancers, targeted oncology, and dermatology conditions with significant unmet need. Those are markets where successful drugs can retain pricing power and generate long product lifecycles.
Incyte’s strategy for future growth is logical. The company uses cash from an established blockbuster, Jakafi, to fund internal research, acquire or license additional assets, and build a broader commercial base. That matters because biotech companies often struggle when a single medicine peaks, but Incyte is trying to convert one major franchise into several durable revenue lines.
Recent revenue momentum has clearly improved. Annual growth moved from mostly high-single-digit to mid-teen levels for a period, and then accelerated further into 2026, reaching roughly the high-30% range in the most recent quarter shown. That is far above the sector median and suggests the company is not relying only on mature products. The combination of Jakafi resilience, newer product contributions, and collaboration income appears to be supporting this step-up.
One important catalyst is Opzelura. Incyte has been expanding this dermatology franchise in a large market where awareness and adoption can build over time. Another catalyst is the broader oncology pipeline, including programs that could either become commercial products or generate milestone and royalty income through partnerships. The company has also been active in business development, which can add external growth on top of its internal research engine.
Cash generation has also strengthened materially after a temporary dip. Free cash flow has risen from the hundreds of millions of dollars into well above $1 billion on a trailing basis. For a biotech company, that is a valuable trait because it reduces dependence on external financing and gives management room to keep investing in trials, launches, and targeted acquisitions without stretching the balance sheet.
Recent company updates have reinforced the idea that Incyte is entering a more productive phase, with commercial execution improving and several pipeline programs moving forward. The most important long-term question is whether newer products can become large enough to offset the eventual maturation of Jakafi. So far, the direction is encouraging because revenue growth is no longer coming from one source alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


