Stock Analysis · Immunome Inc (IMNM)
Overview
Immunome Inc is a clinical-stage biotechnology company focused on developing targeted cancer therapies. Its current strategy centers on antibody-based medicines and antibody-drug conjugates, or ADCs, which are designed to deliver cancer-fighting payloads more precisely to tumor cells. The company expanded that focus materially through the 2024 acquisition of Morphimmune, which added a wider ADC platform and helped reposition Immunome more clearly around oncology.
Because Immunome is still in the development stage, it does not yet have a large commercial product business. Revenue is therefore small, uneven, and tied mainly to collaboration, licensing, and service-related activity rather than recurring medicine sales. Based on recent annual results, the revenue mix appears to be concentrated in a few non-commercial streams.
- Collaboration and licensing revenue: the main source historically, typically linked to research partnerships, milestone-related activity, or rights granted to other companies.
- Research and service revenue: smaller contributions from scientific services or contract-related work.
- Product revenue: currently negligible, because the company does not yet have an approved major commercial therapy.
For 2025, total revenue was only about $7 million, down from roughly $9 million in 2024, while operating expenses remained above $200 million. That gap shows the business is still being funded primarily by its balance sheet rather than by product sales. In practical terms, Immunome today is better understood as a drug developer with promising assets than as an established operating company with stable revenue.
The broader financial flow also highlights a familiar biotech pattern: very limited incoming revenue, heavy research spending, and large operating losses as the pipeline is built. Research and development has become the dominant expense line, which fits the company’s stage and priorities.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $2.03B | |
| Beta ⓘ | 2.56 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 3.75 | 3.08 |
| FCF Yield ⓘ | -10.79% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -11.36% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -100.00% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | N/A | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -23.61% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | 14.84% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -39.44% | 3.24% |
| ROA (Latest) ⓘ | -58.82% | 3.01% |
| ROIC (5Y Median) ⓘ | -42.75% | 4.60% |
| ROA (5Y Median) ⓘ | -90.02% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | -37.69% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | N/A | 9.27% |
| Operating Margin (5Y Median) ⓘ | -1127.01% | 7.38% |
| Debt to Equity (Latest) ⓘ | 0.87% | 28.58% |
| Profit Margin (Latest) ⓘ | N/A | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$219.09M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +95.07% | +42.80% |
| 12M Return (excl. last month) ⓘ | +152.64% | +18.50% |
| 6M Return ⓘ | -25.61% | +7.57% |
| Price vs. 200-Day MA ⓘ | -23.13% | +5.12% |
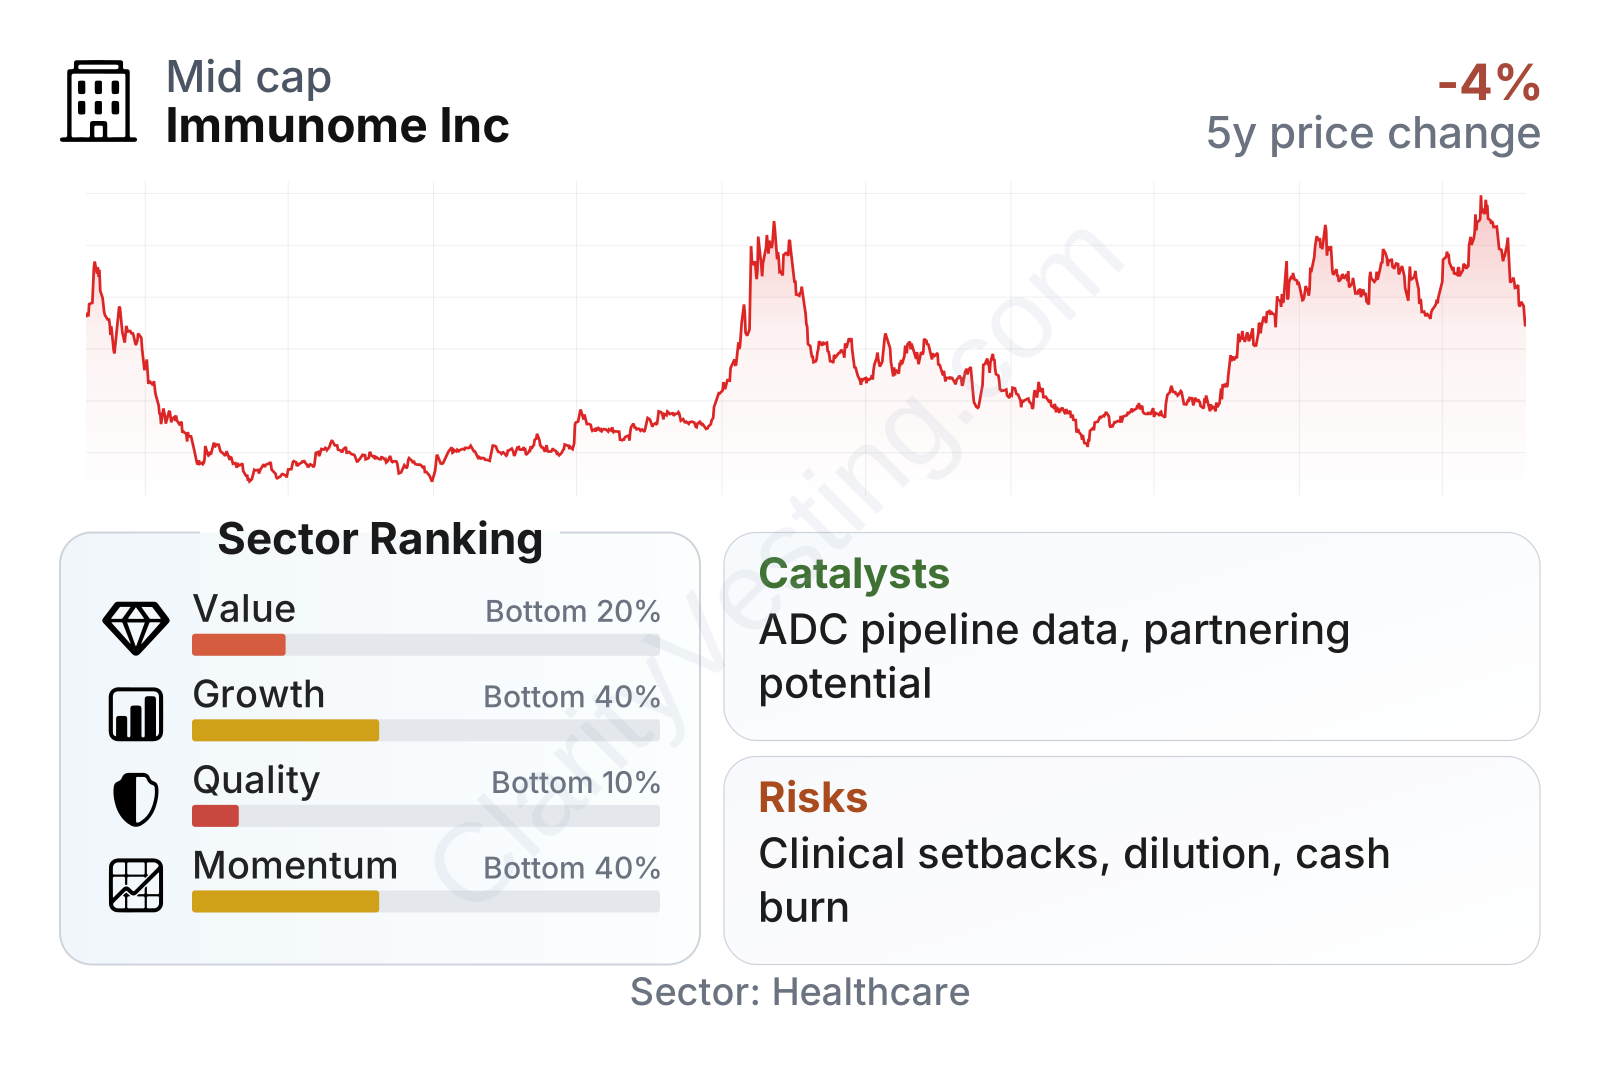
Immunome is a mid-sized biotech by market value, but its operating profile still looks like an early-stage company. The table points to weak value, growth, and quality rankings versus the healthcare sector, while share-price momentum has been much stronger than most peers over the past one to three years. That combination usually means the market is paying for pipeline potential rather than current business performance. The stock also carries high volatility, which is consistent with clinical-stage biotechnology names that can react sharply to trial updates and regulatory news.
Growth
Immunome operates in one of the most active areas of biotech: precision oncology, and more specifically ADCs and targeted antibody therapies. This remains a growing segment because large pharmaceutical companies continue to invest heavily in cancer treatments that can improve efficacy while reducing damage to healthy tissue. The commercial success of several approved ADCs across the industry has increased confidence in the category and raised the strategic value of companies with differentiated targets and payload technologies.
Immunome’s strategy broadly makes sense for long-term growth because it is concentrating resources on areas where industry demand is strong and partnership interest can be meaningful. The Morphimmune acquisition added technology and pipeline depth, giving the company more shots on goal than a single-asset biotech. It also increased Immunome’s relevance in an area where larger drugmakers have been actively seeking external innovation.
The near-term revenue line is not the main growth signal here, since it can move sharply from one period to another depending on milestones and accounting timing. Even so, recent year-over-year revenue swings show that reported sales are not yet a reliable measure of underlying business progress. For this company, clinical advancement matters much more than top-line consistency.
A more useful lens is cash use. Free cash flow has moved deeper into negative territory as the pipeline has expanded and development spending has increased. That is normal for a company at this stage, but it means future value creation depends on turning R&D spending into credible clinical data.
Recent company updates have highlighted progress across its oncology pipeline, including lead programs aimed at validated cancer targets and newer assets emerging from the ADC platform. The strongest catalysts are likely to be clinical trial initiations, early human data, and any partnership or licensing deal that validates the science. In this part of biotech, a credible data readout can reshape perceptions of an entire company much faster than conventional financial growth would.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


