Stock Analysis · Imdex Limited (IMDXF)
Overview
Imdex Limited is an Australian mining technology company that sells equipment, sensors, software, and drilling optimization services used in mineral exploration and mining. Its products help mining companies and drilling contractors collect geological data, improve drilling accuracy, and make faster decisions about where valuable ore may be located. In simple terms, Imdex sits at the intersection of mining and industrial technology: it does not mine commodities itself, but it provides the tools and digital systems that make exploration and drilling more efficient.
The company’s business is mainly tied to mining exploration activity, especially drilling. Demand therefore tends to rise when miners are spending more on discovering new deposits, expanding resources, or improving mine productivity. Imdex has also been pushing further into connected digital workflows, where physical drilling tools, downhole sensors, cloud platforms, and analytics work together as one operating system for field teams and geologists.
Based on the company’s recent reporting structure and business descriptions, revenue is primarily generated from drilling technologies and mining software-related solutions. A simple way to think about the mix is:
- Drilling optimization products and consumables: approximately 70% to 80% of revenue. This includes drilling fluids, core orientation tools, surveying instruments, and other products used directly at drill sites.
- Rock knowledge sensors, instruments, and data services: approximately 15% to 25% of revenue. This includes downhole instrumentation, orebody knowledge tools, and systems that capture geological information during drilling.
- Mining software and digital platforms: approximately 5% to 15% of revenue. This includes cloud-based data management, visualization, and decision-support software used by geologists and mining teams.
That mix matters because the first category usually provides recurring field-driven demand, while the software and data layer can support stickier customer relationships over time.
Revenue has expanded materially over the last several years, and the business still converts a large share of sales into gross profit. At the same time, the latest period shows that cost of revenue has risen sharply, so the quality of future growth will depend not only on sales expansion but also on whether margins remain resilient as the company scales.
The long-term pattern is one of higher revenue and improving net income, but the latest year also suggests a more complex cost picture than earlier periods. That makes execution on pricing, integration, and operating efficiency especially important.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Farm & Heavy Construction Machinery | |
| Market Cap ⓘ | $1.17B | |
| Beta ⓘ | 1.19 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.50 | 22.10 |
| P/B Ratio ⓘ | 1.75 | 1.97 |
| FCF Yield ⓘ | 12.50% | 6.38% |
| Dividend Yield ⓘ | 1.51% | 1.94% |
| EBIT / EV ⓘ | N/A | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 24.70% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 4.40% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 22.08% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 15.77% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -2.60% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -4.53% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | 13.88% | 5.41% |
| ROIC (5Y Median) ⓘ | 8.73% | 9.38% |
| ROA (5Y Median) ⓘ | 6.83% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.56 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.26 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.90 | 1.39 |
| Net Debt / Assets ⓘ | 21.53% | 19.28% |
| EBITDA / Interest ⓘ | 11.16 | 9.58 |
| Operating Margin (Latest) ⓘ | 16.44% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 16.18% | 10.29% |
| Debt to Equity (Latest) ⓘ | 41.59% | 65.48% |
| Profit Margin (Latest) ⓘ | 15.28% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $146.32M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +130.00% | +61.68% |
| 12M Return (excl. last month) ⓘ | +21.92% | +12.58% |
| 6M Return ⓘ | -24.06% | 0.00% |
| Price vs. 200-Day MA ⓘ | N/A | +0.02% |
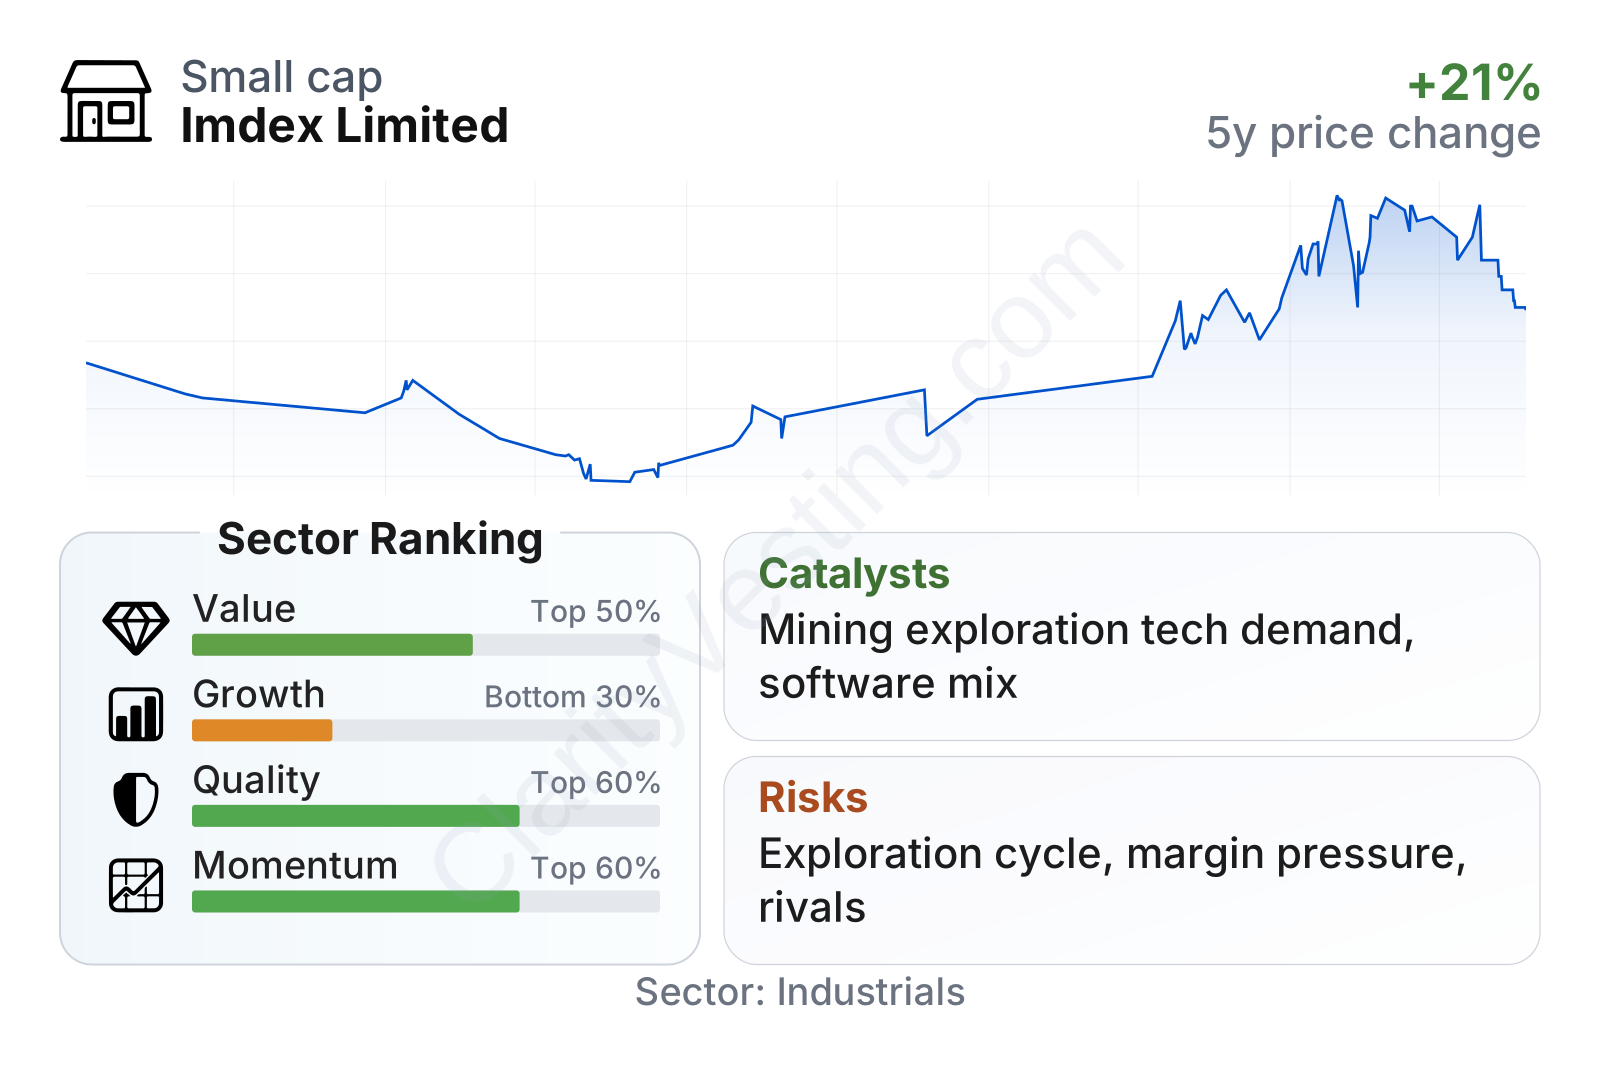
Imdex is a mid-sized industrial technology company with a stock that has outperformed much of its sector over the last three years, even though the last six months have been softer. Profitability looks stronger than many peers: operating margin is around the mid-teens versus a sector median near 10%, profit margin is also well above the median, and return on assets is strong. Cash generation stands out as well, with free cash flow yield around 12% compared with roughly 6% for the sector median.
The balance sheet appears manageable rather than stretched. Debt to equity is about 42%, below the sector median, while net debt is under 1.0 times EBITDA, which is a comfortable level for an industrial company. Interest coverage is also healthy. The weaker area is growth quality over a longer period: recent yearly revenue growth has been strong at about 25%, but five-year revenue-per-share growth is slower than the sector median, and margin trends over five years have softened slightly.
Growth
Imdex operates in a part of the mining supply chain that can benefit from two durable themes. The first is the need to find new mineral deposits as ore grades decline and as demand rises for metals linked to electrification, infrastructure, and energy transition. The second is the mining industry’s push toward better real-time data, automation, and more efficient drilling programs. Both trends support the kind of products Imdex sells.
The company’s strategy also makes industrial sense. Instead of depending on a single piece of hardware, Imdex combines consumables, instruments, and software into a broader workflow. That can improve customer retention because once a mining company or drilling contractor uses several connected products together, switching becomes less convenient. This does not make Imdex untouchable, but it does create a practical advantage compared with selling stand-alone tools.
A further growth driver is international diversification. Mining exploration spending is global, and Imdex serves customers across major resource regions rather than relying on one country. That helps the company participate in broader exploration cycles, although it does not remove the underlying cyclicality of mining budgets.
Recent company communications have continued to emphasize technology adoption, digital integration, and the expansion of its cloud and data capabilities. Those initiatives could be important because software-linked revenue typically carries better economics and stronger customer stickiness than purely transactional equipment sales. If the company can keep increasing the share of revenue tied to data workflows and recurring usage, future growth could become less dependent on one-off equipment demand.
Another supportive signal is that earnings and free cash flow remain solid even after a period of heavier cost pressure. That suggests the business still has operational strength while pursuing expansion. In a favorable exploration spending environment, the combination of field products and digital tools gives Imdex several ways to grow at once.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


