Stock Analysis · Infratil Limited (IFUUF)
Overview
Infratil Limited is a New Zealand-based infrastructure investor and operator. Rather than running one single business line, it owns stakes in a portfolio of assets tied to essential services and long-duration themes. The group is mainly exposed to renewable energy, digital infrastructure, airports, and healthcare-related property and services through its major investments.
Its portfolio has included Manawa Energy in New Zealand electricity generation, CDC Data Centres in Australia and New Zealand, One NZ in telecommunications, Wellington Airport, and RetireAustralia. This makes Infratil different from a traditional industrial company: its results depend on the operating performance, valuations, financing, and development pipelines of several underlying businesses.
The main sources of economic value are best understood through the company’s major investment platforms rather than a simple product list. Based on the latest public reporting, the mix is centered on the following areas:
- Digital infrastructure: CDC Data Centres is one of the most important assets in the portfolio and has become a major driver of value, supported by demand from cloud computing, enterprise workloads, and government-related data hosting.
- Telecommunications: One NZ contributes through mobile and connectivity services in New Zealand, giving the group exposure to recurring subscription-based revenue.
- Renewable energy and electricity: Manawa Energy adds earnings linked to hydro generation and the broader need for low-carbon power.
- Airports: Wellington Airport contributes through passenger traffic, retail, and aeronautical activity, although this business is naturally more cyclical than regulated or contracted infrastructure.
- Retirement living and other infrastructure interests: RetireAustralia and smaller holdings provide additional diversification.
Because Infratil reports as an investment company with major associates and controlled subsidiaries, a precise consolidated revenue split by portfolio company is not always directly comparable to a standard operating company. What is clear is that digital infrastructure and telecommunications have become increasingly important to the group’s current profile, while energy and airport assets remain meaningful contributors to cash generation and asset value.
The broader income flow also shows how the business has changed over time: revenue expanded sharply over the last few years, gross profit remained substantial, and net income has been more volatile because financing costs, portfolio mix, and valuation-related movements can materially affect reported results from one year to another.
That picture fits Infratil’s identity well: a diversified infrastructure owner with strong exposure to assets that can scale over many years, but with reported earnings that can look uneven from period to period.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Conglomerates | |
| Market Cap ⓘ | $7.84B | |
| Beta ⓘ | 0.08 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 49.06 | 22.29 |
| P/B Ratio ⓘ | 1.03 | 1.98 |
| FCF Yield ⓘ | -4.15% | 6.26% |
| Dividend Yield ⓘ | 2.66% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | 1.04 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -20.00% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 45.04% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -2.42% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 23.79% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | -11.05% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 7.26% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.75% |
| ROA (Latest) ⓘ | 1.54% | 5.41% |
| ROIC (5Y Median) ⓘ | 9.95% | 9.37% |
| ROA (5Y Median) ⓘ | 6.42% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 6.78 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 9.60 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 3.27 | 1.39 |
| Net Debt / Assets ⓘ | 41.83% | 19.27% |
| EBITDA / Interest ⓘ | 2.92 | 9.58 |
| Operating Margin (Latest) ⓘ | 15.09% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 34.28% | 10.30% |
| Debt to Equity (Latest) ⓘ | 103.15% | 64.82% |
| Profit Margin (Latest) ⓘ | 15.77% | 6.67% |
| Free Cash Flow (Latest) ⓘ | -$325.61M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +27.36% | +67.77% |
| 12M Return (excl. last month) ⓘ | +52.25% | +12.05% |
| 6M Return ⓘ | +0.18% | 0.00% |
| Price vs. 200-Day MA ⓘ | -10.36% | +0.67% |
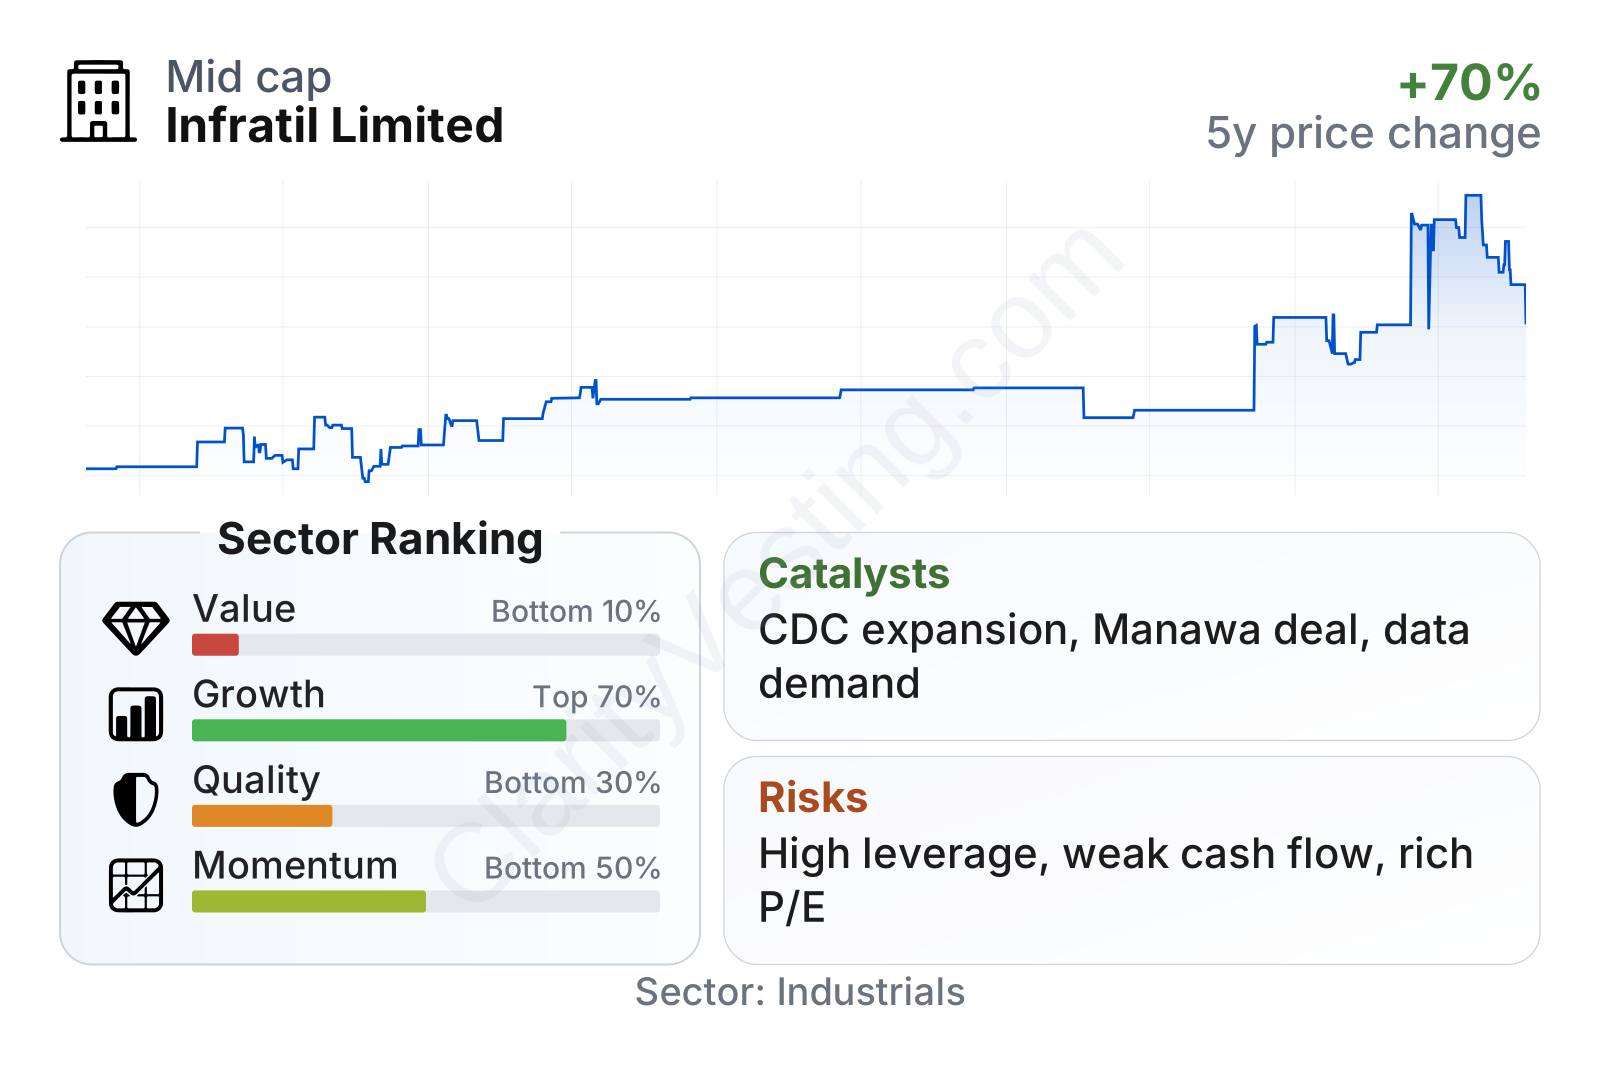
Infratil is a large infrastructure group by market value, and its share price has been strong over the last year. Momentum stands above much of the sector, but the valuation profile is demanding. The stock trades on a high earnings multiple relative to the sector median, while free cash flow is currently negative. On the other hand, book value multiples look low, which can happen with asset-heavy holding companies where underlying assets may not be fully reflected by a simple earnings-based lens.
The factor breakdown is mixed. Growth and market momentum rank better than value and quality. That combination suggests the market is paying up for future expansion, especially in higher-growth assets, even though current balance sheet pressure and cash conversion remain weaker than many industrial peers.
Growth
Infratil operates in several sectors with durable long-term demand. The strongest of these is digital infrastructure. Data centers are benefiting from cloud adoption, rising data use, enterprise outsourcing, and AI-related computing needs. That is especially relevant because CDC Data Centres has become one of the portfolio’s most strategically important assets. For a long-term view, this is likely the clearest growth engine inside the group.
Renewable energy is another supportive theme. Through Manawa Energy and the company’s broader interest in power infrastructure, Infratil has exposure to electrification and decarbonization, two trends that are likely to remain important for many years. Telecommunications also adds a layer of recurring demand, since mobile connectivity is now an essential service rather than a discretionary one.
The company’s strategy is coherent for future growth because it focuses on assets with high replacement costs, long development cycles, and essential-service characteristics. Infratil has often aimed to build or scale infrastructure platforms early, then compound value through expansion and operational improvement. That model can work particularly well in areas like data centers, where demand can rise faster than industry capacity.
Short-term growth looks less smooth than the long-term trend. Recent year-over-year revenue growth has been weak, but the longer record is much stronger: revenue per share over five years has compounded far above the sector median, and book value per share has also grown at a solid pace. This suggests the company has been expanding its asset base successfully, even if that has not translated into steady annual earnings progress.
A recent and significant catalyst is the proposed combination involving Manawa Energy and Contact Energy, which has the potential to reshape the value of Infratil’s energy exposure and crystallize part of the worth embedded in that holding. In parallel, ongoing expansion at CDC remains a major opportunity, particularly if hyperscale and government demand for secure capacity continues to rise in Australia and New Zealand.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


