Stock Analysis · Informa plc (IFPJF)
Overview
Informa plc is a business-to-business information group. In plain English, it helps specialized professional communities meet, learn, market products, and access industry intelligence. Its activities span live events, academic publishing, specialist data, and digital services. The company is best known for large trade shows and professional events, but it also owns academic journals and industry-focused intelligence products serving areas such as healthcare, life sciences, finance, maritime, and technology.
After reshaping the business over recent years, Informa is now centered on two main engines: events and academic markets. That mix matters because events can generate strong cash flow when attendance and exhibitor demand are healthy, while subscription-like publishing and information services can add more recurring revenue and stability.
Based on recent company reporting, the main revenue sources are approximately the following:
- Informa Markets and Informa Connect events businesses: about 60% to 70% of group revenue. This includes trade shows, exhibitions, conferences, corporate learning, and specialist audience-led events.
- Taylor & Francis academic publishing: about 25% to 35% of revenue. This business publishes academic journals, books, and digital research content, with a meaningful share from recurring institutional and library demand.
- Informa TechTarget and other digital information services: a smaller but strategically important share of revenue. This includes digital demand generation, specialist data, research, and business intelligence products, particularly in technology markets.
That revenue structure gives Informa exposure to both cyclical activity, especially trade events, and steadier knowledge-based income from publishing and subscription-oriented information products.
The long-term pattern is clear: revenue has expanded materially since 2021, and operating income has improved faster than sales. At the same time, bottom-line earnings have been more uneven than operating profit, which suggests that financing costs, taxes, acquisition effects, and non-operating items still have a meaningful influence on reported net income.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Publishing | |
| Market Cap ⓘ | $14.54B | |
| Beta ⓘ | 0.68 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 50.59 | 18.20 |
| FCF Yield ⓘ | 10.77% | 14.71% |
| Dividend Yield ⓘ | 1.88% | 2.86% |
| EBIT / EV ⓘ | N/A | 4.85% |
| PEG ⓘ | 0.14 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.40% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | 30.97% | 4.55% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -18.01% |
| Margin Growth (5Y Trend) ⓘ | 10.21% | 1.32% |
| FCF Growth (5Y CAGR) ⓘ | 19.91% | 5.96% |
| DPS Growth (5Y CAGR) ⓘ | 63.45% | 5.09% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.46% | 8.64% |
| ROIC (5Y Median) ⓘ | 4.98% | 8.11% |
| Net Debt / EBIT (Latest) ⓘ | 2.29 | 1.92 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.97 | 2.85 |
| Net Debt / EBITDA (Latest) ⓘ | 1.41 | 1.25 |
| Net Debt / Assets ⓘ | 22.91% | 18.77% |
| EBITDA / Interest ⓘ | 7.70 | 8.75 |
| Operating Margin (Latest) ⓘ | 17.02% | 15.58% |
| Operating Margin (5Y Median) ⓘ | 13.99% | 13.53% |
| Debt to Equity (Latest) ⓘ | 64.99% | 59.53% |
| Profit Margin (Latest) ⓘ | 5.43% | 8.78% |
| Free Cash Flow (Latest) ⓘ | $1.57B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +43.01% | +43.39% |
| 12M Return (excl. last month) ⓘ | +5.70% | +1.92% |
| 6M Return ⓘ | +10.60% | +2.94% |
| Price vs. 200-Day MA ⓘ | +22.54% | +0.74% |
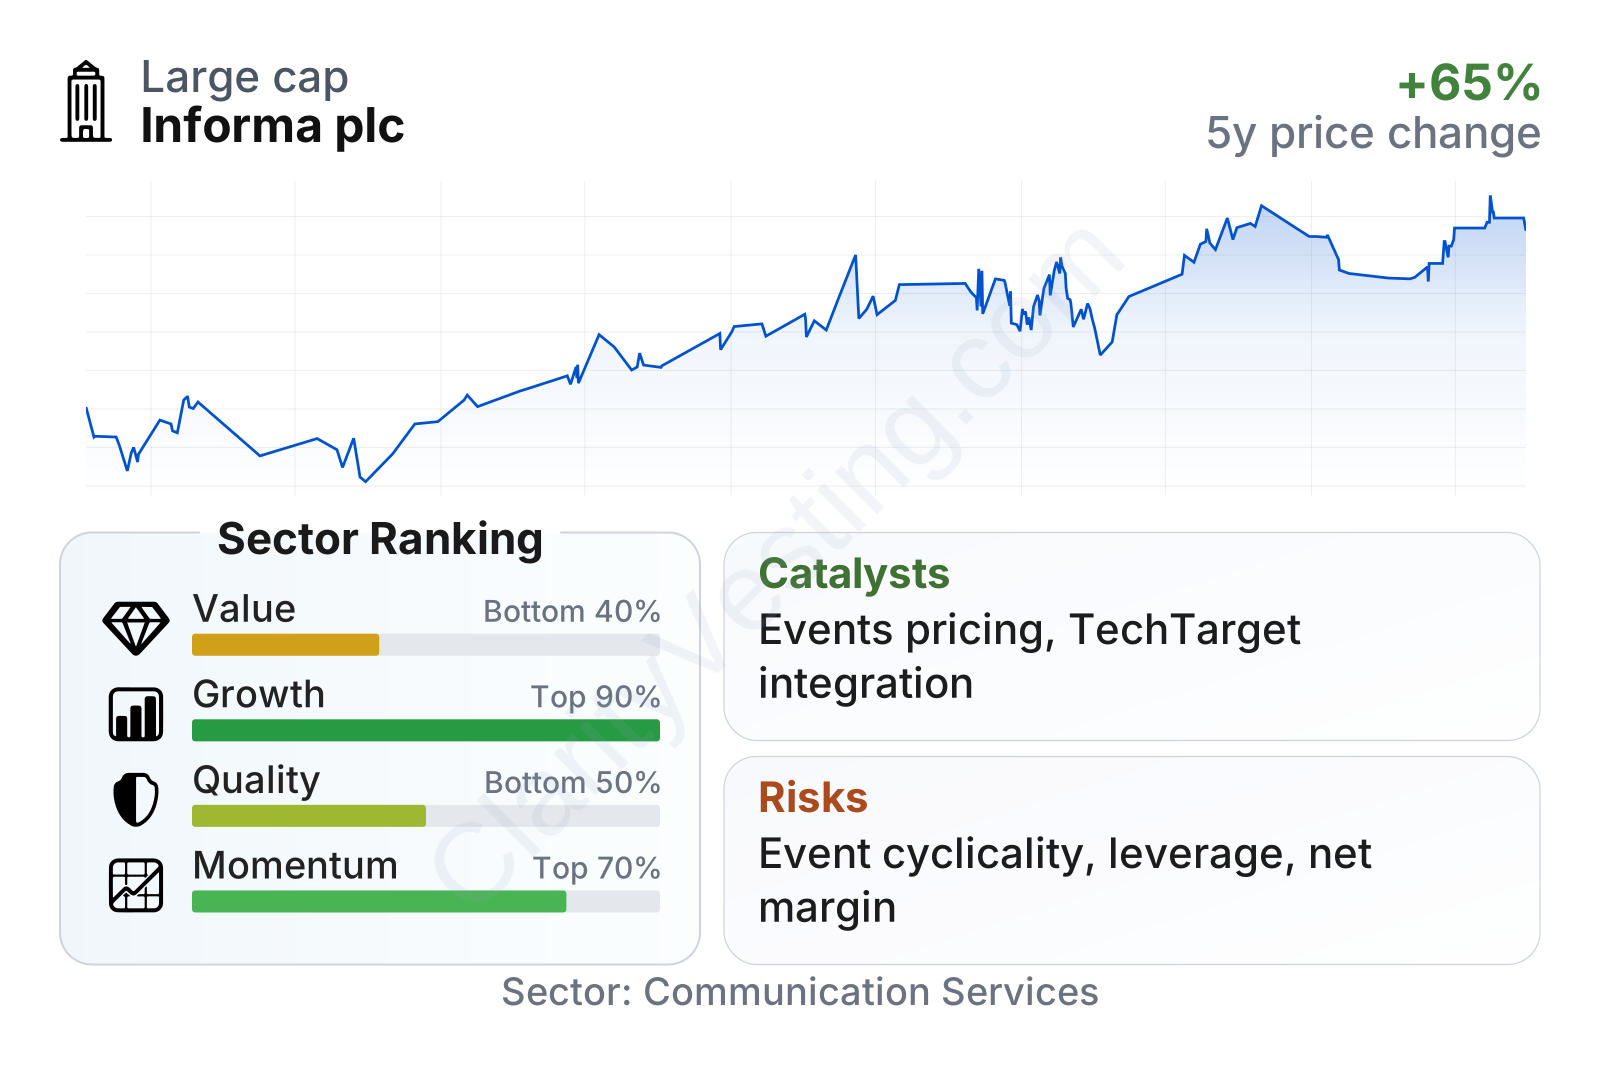
Informa sits in the large-cap range and its share price has shown lower volatility than the broader market, as reflected by a beta below 1. The company ranks strongly on growth measures versus much of its sector, helped by a very strong five-year expansion in revenue per share, free cash flow, margins, and dividends per share. Quality is more mixed: current returns on invested capital and operating margins are solid, but leverage is somewhat above sector medians and net profit margin remains comparatively modest. On valuation measures, the shares screen as expensive on earnings and not especially generous on dividend yield or free-cash-flow yield relative to peers.
The stock chart also points to a constructive trend over the past several years, with the shares well above their long-term average and recent price performance ahead of the sector median. That does not say whether the shares are cheap, but it does show that the market has generally rewarded the company’s post-pandemic rebuilding and portfolio repositioning.
Growth
Informa operates in markets with durable long-term demand. The events industry benefits from the continued importance of in-person commercial interaction, especially in complex sectors where buyers and sellers value product discovery, lead generation, and relationship building. Academic publishing has slower headline growth, but it remains supported by global research output, institutional subscriptions, and the steady need for peer-reviewed content. Digital B2B marketing and specialist intelligence also remain attractive because companies increasingly want measurable lead generation and data-driven customer acquisition.
Informa’s strategy broadly fits these trends. The company has spent several years simplifying the portfolio around categories where it can run scaled brands and repeatable platforms. Its event franchises benefit from network effects: large shows attract exhibitors, which attract attendees, which in turn reinforces the franchise. In academic publishing, scale supports editorial reach, distribution, and long customer relationships. In digital services, the combination of professional audiences and first-party data can improve monetization if executed well.
Short-term revenue growth is not especially fast relative to the wider Communication Services universe, but the longer arc looks much stronger. That is important for understanding Informa: this is not primarily a rapid early-stage growth company, but a more mature platform business that has been compounding through recovery, operational improvement, and acquisitions.
A notable catalyst is the company’s expansion in specialist digital markets through Informa TechTarget. That combination aims to connect high-value technology audiences, intent data, and B2B marketing services at a time when software and IT vendors are seeking better-quality leads and more efficient customer acquisition. If integration progresses well, this could gradually shift part of the group toward more digital and data-led revenue streams.
Another growth support is geographic and category breadth. Informa runs major brands across multiple regions and end markets, which can create room for venue expansion, pricing gains, adjacent product launches, and cross-selling. Large event brands in industries such as healthcare, pharmaceuticals, beauty, boating, and advanced manufacturing can become platforms rather than one-off gatherings.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


