Stock Analysis · International Flavors & Fragrances Inc (IFF)
Overview
International Flavors & Fragrances Inc. is a specialty ingredients company that sells the formulas, compounds, and functional ingredients used in everyday consumer products. Its work is usually invisible to shoppers, but it sits inside products such as perfumes, skin care, detergents, soft drinks, dairy items, snacks, dietary supplements, pharmaceuticals, and packaged foods. In practice, IFF helps customers improve taste, smell, texture, shelf life, and product performance.
The company operates through several business lines that serve consumer goods, food, health, and industrial markets around the world. Following major portfolio reshaping in recent years, the business mix is more focused than it was after the large DuPont nutrition merger.
Based on the latest annual reporting structure, revenue is mainly generated from the following segments, ranked from largest to smallest:
- Taste — about 31% of revenue. This includes flavors and ingredient systems used in beverages, savory products, sweets, dairy, and other food applications.
- Scent — about 18%. This business develops fragrance compounds and scent technologies for fine fragrance, personal care, home care, and fabric care.
- Health & Biosciences — about 18%. This segment includes enzymes, cultures, probiotics, pharma solutions, and biotechnology-based ingredients used in food, health, and industrial applications.
- Pharma Solutions — about 17%. This unit supplies excipients and other ingredients used in drug formulation and delivery.
- Nourish and smaller activities within the current reporting perimeter — the remaining share, roughly 16%, tied to food ingredients and solutions not captured above or affected by portfolio changes and reporting updates.
One important point for long-term readers is that IFF is not a commodity chemical producer in the usual sense. Its products are often customized, embedded in customer formulations, and supported by application know-how, regulatory expertise, and long development cycles. That tends to create stickier customer relationships than in more price-driven chemical markets.
The flow of the business over the past few years shows a company that kept a large gross profit base, invested heavily in research and commercial support, but saw earnings swing sharply because of restructuring, impairments, and portfolio actions. Revenue stayed around the low tens of billions of dollars, while profitability was much more volatile than sales.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $21.75B | |
| Beta ⓘ | 0.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.61 |
| P/B Ratio ⓘ | 1.54 | 1.77 |
| FCF Yield ⓘ | 2.46% | 5.87% |
| Dividend Yield ⓘ | 1.87% | 2.06% |
| EBIT / EV ⓘ | 1.95% | 6.43% |
| PEG ⓘ | 1.77 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.80% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | -2.96% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | -23.17% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | -10.67% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | -29.56% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | -12.65% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.19% | 9.31% |
| ROA (Latest) ⓘ | 1.14% | 4.94% |
| ROIC (5Y Median) ⓘ | -0.66% | 7.91% |
| ROA (5Y Median) ⓘ | -1.33% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 10.55 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 3.82 | 0.91 |
| Net Debt / Assets ⓘ | 22.56% | 13.69% |
| EBITDA / Interest ⓘ | 7.95 | 11.93 |
| Operating Margin (Latest) ⓘ | 5.39% | 13.07% |
| Operating Margin (5Y Median) ⓘ | -1.68% | 11.86% |
| Debt to Equity (Latest) ⓘ | 44.67% | 40.43% |
| Profit Margin (Latest) ⓘ | 2.57% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $536.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +30.88% | +65.06% |
| 12M Return (excl. last month) ⓘ | +30.97% | +36.05% |
| 6M Return ⓘ | +16.22% | +1.89% |
| Price vs. 200-Day MA ⓘ | +10.68% | +1.03% |
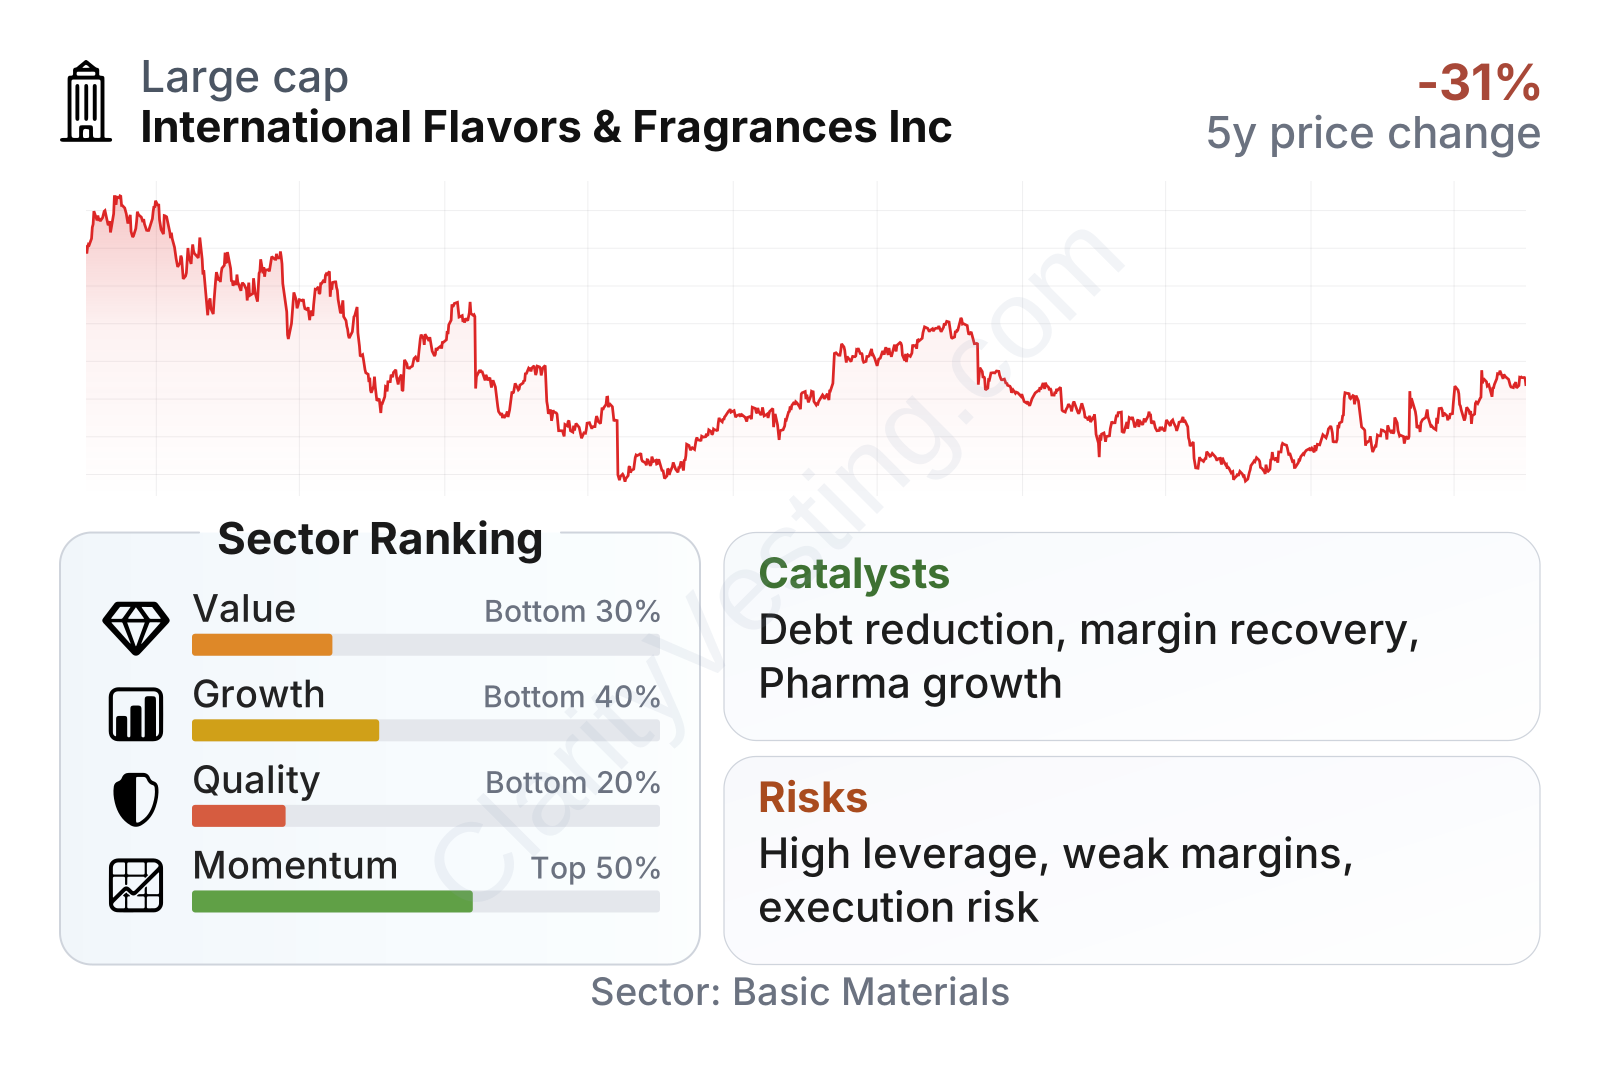
IFF is a large global specialty ingredients company with a market value around the low-$20 billion range and a stock volatility close to the broader market. The overall factor picture is mixed. Momentum has improved recently, but value, growth, and especially quality rank below much of the sector. That combination suggests the market has recognized some operational stabilization, while the underlying business still has meaningful work to do on returns, margins, and balance-sheet efficiency.
Free cash flow remains positive, but the yield is below the sector median. Profitability and returns on capital also trail peers by a wide margin. In simple terms, the company is generating cash, but not yet with the consistency or efficiency usually associated with stronger specialty chemical franchises.
Growth
IFF operates in markets that generally benefit from long-term demand rather than short-lived fads. Flavors, fragrances, food ingredients, health ingredients, and pharmaceutical excipients are tied to population growth, rising consumption of packaged products, premiumization, wellness trends, and continuous product reformulation by major consumer brands. These are attractive end markets because demand usually comes from thousands of daily-use products rather than one narrow category.
Its strategy also has a clear industrial logic. The company is trying to sharpen focus after years of heavy integration work and asset reshaping. Management has emphasized productivity, cost savings, portfolio simplification, and debt reduction while keeping research spending substantial. That matters because IFF’s competitive position depends on formulation know-how, customer co-development, and regulatory capabilities as much as on manufacturing scale.
Near-term growth, however, has been uneven. Sales growth was very strong during the major merger period, then turned negative for several quarters, recovered modestly, and weakened again more recently. The current pattern looks less like a structurally broken franchise and more like a business still digesting portfolio changes, customer destocking cycles, and a softer demand backdrop in some end markets. Even so, recent revenue growth remains below the sector median, so the turnaround is not yet broad-based.
Cash generation has improved from the weak point reached in 2023, although it remains volatile. Positive free cash flow is important for IFF because it supports debt reduction and gives the company flexibility to invest in innovation and operations without relying too heavily on external financing. A return to steadier cash conversion would be one of the clearest signs that the restructuring phase is maturing into a healthier operating model.
As for catalysts, the most important ones are internal rather than speculative. Continued debt reduction, better margins after cost actions, stronger execution in Pharma Solutions and biosciences, and a more normalized demand environment could all improve the earnings profile. The broader sector backdrop also helps: global consumer companies keep launching new products and reformulating existing ones, and that creates recurring demand for flavor, scent, and functional ingredient partners with global reach.
Recent company updates in 2026 have continued to highlight productivity actions, portfolio discipline, and efforts to improve profitability. For a company in IFF’s position, these are significant because even modest operating improvements can have a large effect on earnings after several years marked by weak margins and heavy charges.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


