Stock Analysis · INFICON Holding AG (IFCNF)
Overview
INFICON Holding AG is a Swiss industrial technology company that makes instruments, sensors, and software used to measure, detect, and control gases, leaks, pressure, and vacuum conditions in advanced manufacturing and industrial processes. Its products are especially important in semiconductor equipment, where tiny process variations can affect chip yields, but the company also serves refrigeration and air-conditioning, automotive, battery production, industrial vacuum systems, and security-related applications.
The business is built around selling specialized measurement and control tools that customers integrate into production lines, service operations, and research environments. That tends to make INFICON less dependent on one single product cycle than a pure-play chip equipment name, even though semiconductors are a major driver of results.
Based on the company’s recent annual reporting, revenue is organized across end markets rather than simple product families. Approximate revenue sources, from largest to smallest, are as follows:
- Semiconductor and vacuum coating: about 50% to 55% of revenue. This includes sensors and process-control tools used in wafer fabrication and thin-film deposition.
- General vacuum: about 15% to 20%. This covers vacuum measurement and control products used in industrial, research, and analytical systems.
- Refrigeration, air-conditioning, and automotive: about 15% to 20%. This includes leak detectors and service tools used in HVAC and vehicle-related applications.
- Security and energy: about 10% to 15%. This area includes detection technologies used in specialized industrial and public-sector environments.
Over the last several years, the company has expanded revenue meaningfully while keeping healthy profitability. The income flow also shows a business with solid gross margins and disciplined spending on research and selling costs, although 2025 appears weaker on earnings than 2024 despite similar sales, indicating margin pressure rather than a demand collapse.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Scientific & Technical Instruments | |
| Market Cap ⓘ | $5.29B | |
| Beta ⓘ | 1.53 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 54.08 | 29.95 |
| FCF Yield ⓘ | N/A | 4.22% |
| Dividend Yield ⓘ | 1.17% | 1.30% |
| EBIT / EV ⓘ | N/A | 2.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 16.40% | 15.80% |
| RPS Growth (5Y CAGR) ⓘ | 6.91% | 8.55% |
| EPS Growth (5Y CAGR) ⓘ | -6.79% | -11.72% |
| Margin Growth (5Y Trend) ⓘ | -3.18% | 0.39% |
| FCF Growth (5Y CAGR) ⓘ | 2.51% | 9.72% |
| DPS Growth (5Y CAGR) ⓘ | 8.32% | 7.73% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.36% |
| ROIC (5Y Median) ⓘ | 28.15% | 8.32% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.46 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.28 |
| Net Debt / Assets ⓘ | N/A | 3.44% |
| EBITDA / Interest ⓘ | N/A | 12.67 |
| Operating Margin (Latest) ⓘ | N/A | 9.81% |
| Operating Margin (5Y Median) ⓘ | 19.30% | 8.50% |
| Debt to Equity (Latest) ⓘ | N/A | 33.33% |
| Profit Margin (Latest) ⓘ | 13.48% | 7.15% |
| Free Cash Flow (Latest) ⓘ | N/A | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +219.39% | +49.46% |
| 12M Return (excl. last month) ⓘ | +70.73% | +16.51% |
| 6M Return ⓘ | +62.25% | +24.29% |
| Price vs. 200-Day MA ⓘ | +50.12% | +4.74% |
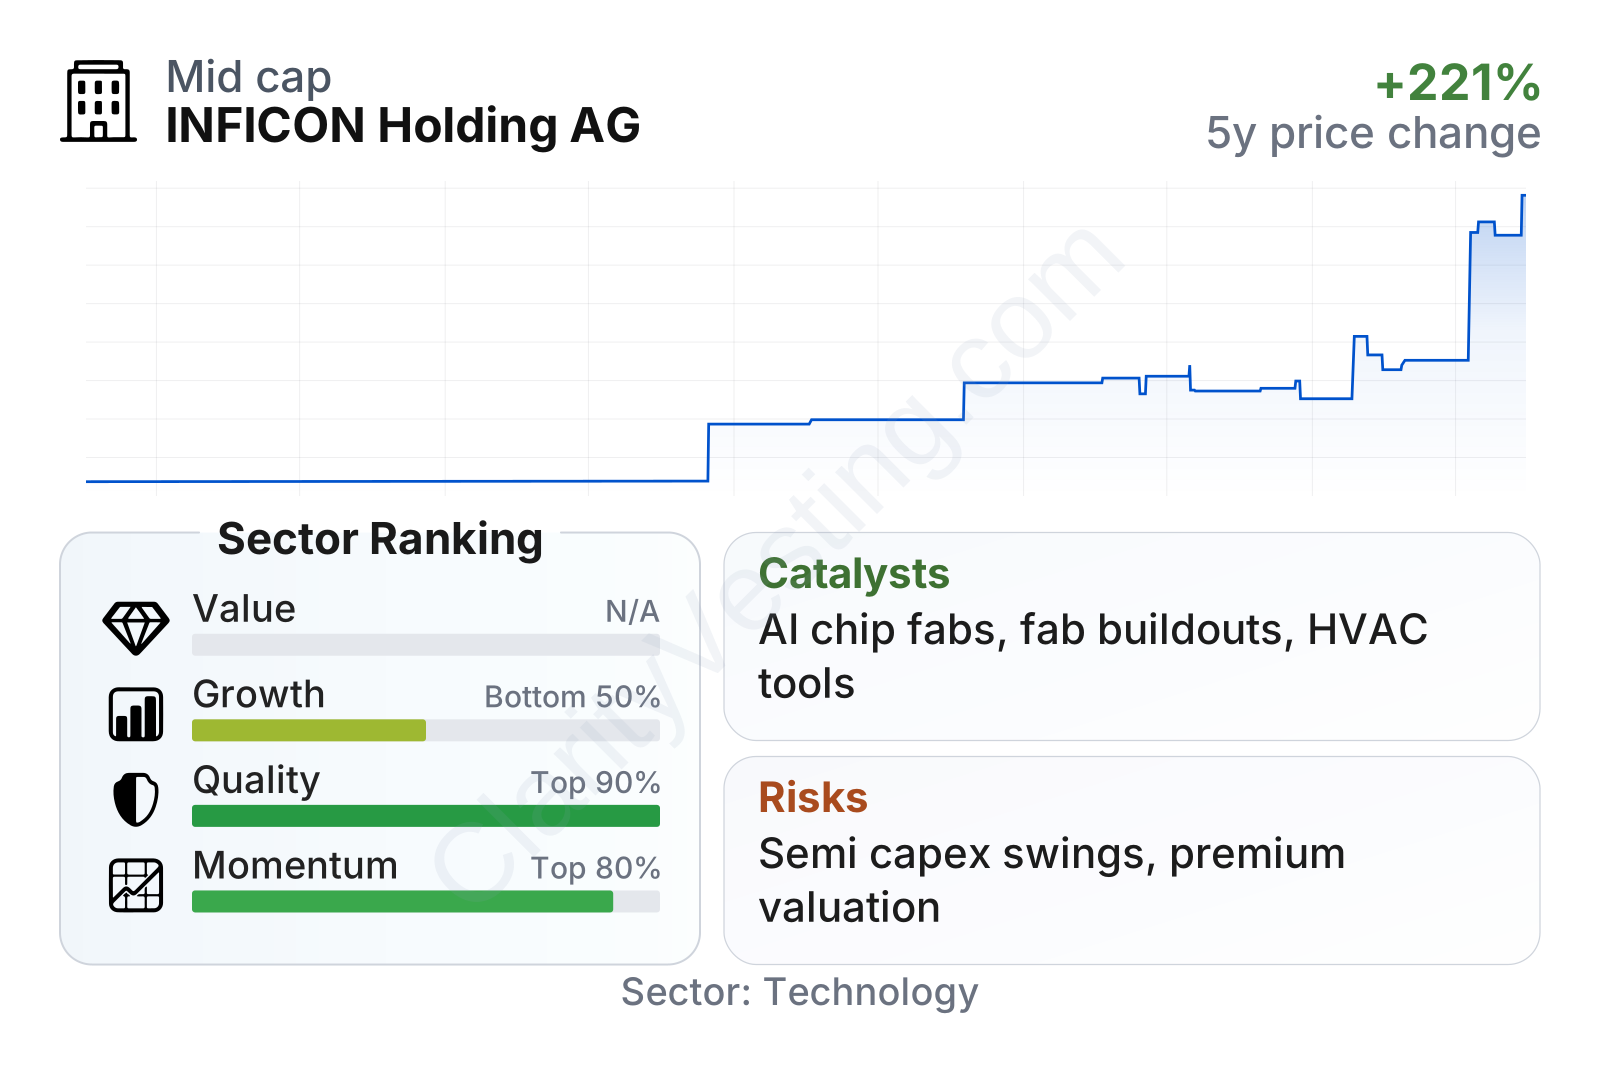
INFICON is a mid-sized technology instrumentation company with a share price that has moved strongly upward over the last three years, far ahead of the sector median. Recent growth metrics are respectable rather than exceptional: revenue growth is a little above the sector median, but five-year revenue-per-share and free-cash-flow growth trail broader technology peers. Profitability stands out more clearly, with a net margin of roughly 13% versus a sector median near 7%. The dividend yield is modest at a little above 1%, and the stock’s beta of about 1.5 suggests above-average volatility.
This mix points to a company that is financially solid and operationally efficient, but one whose market performance has already been much stronger than its underlying long-term growth profile. That matters because it helps explain why valuation looks demanding.
Growth
INFICON operates in markets with favorable long-term tailwinds. The most important one is semiconductor manufacturing, where rising chip complexity, more process steps, and tighter quality requirements increase the need for precision measurement and vacuum control. Demand is also supported by broader digitization, artificial intelligence infrastructure, advanced packaging, and the geographic expansion of chip fabrication capacity.
The company’s strategy makes industrial sense. Instead of chasing volume in commoditized equipment, it focuses on high-value tools that solve difficult process-control problems. That usually supports pricing power, customer stickiness, and recurring replacement demand. Its research spending has also remained meaningful year after year, which is important in markets where product performance and reliability matter more than headline branding.
Another growth pillar is diversification outside semiconductors. Leak detection and gas-analysis tools are relevant to HVAC efficiency rules, electric-vehicle battery manufacturing, and industrial automation. These are not all explosive markets, but together they broaden the company’s opportunity set and reduce dependence on a single customer category.
A notable catalyst is the continued buildout of advanced semiconductor fabs in the United States, Europe, and Asia. As new production lines are equipped and existing ones upgraded, INFICON has room to capture more content per tool set. In addition, public company updates in 2026 indicate ongoing focus on semiconductor-related demand and on expanding capacity and product capabilities, which supports the idea that management is positioning for another phase of industry investment rather than managing for stagnation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


