Stock Analysis · Ivanhoe Electric Inc (IE)
Overview
Ivanhoe Electric Inc is a U.S.-listed mineral exploration and development company focused mainly on copper in the United States. Its core ambition is to discover and advance domestic sources of critical metals, especially copper, using a mix of traditional mine development and proprietary exploration technology. The company’s best-known asset is the Santa Cruz Copper Project in Arizona, and it also owns the Typhoon geophysical survey platform used to identify underground mineral targets.
For a long-term reader, the important point is that Ivanhoe Electric is not yet a mature mining producer with large recurring metal sales. It is still in the development stage, which means its economic value depends heavily on proving resources, advancing projects toward production, securing permits, and eventually building mines at attractive returns. That makes the business more speculative than established miners, but also more exposed to major upside if its projects are successfully de-risked.
Its revenue base is currently small and uneven. Based on company filings, revenue has come from a limited mix of early commercial activities rather than broad mining production.
- Equipment and technology-related activity: historically the largest source in some periods, tied mainly to the company’s geophysical services and related commercial work through its exploration technology platform.
- Project and mining-related activity: includes early-stage operational revenue associated with mineral projects, though this remains limited because the company is still developing, not operating, a large producing copper mine.
- Other revenue: a smaller category that can include ancillary items and does not yet represent a stable, large-scale earnings engine.
Because the company is still pre-scale, precise segment percentages are not consistently meaningful across periods. What is clear is that revenue remains very small relative to operating costs, and the company’s investment case is driven much more by asset development potential than by current sales.
The business flow also shows a familiar pattern for an early-stage resource developer: modest revenue, high operating expenses, and persistent losses while projects are advanced. Losses narrowed from 2023 to 2025, but the company is still spending far more than it generates from current operations.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Copper | |
| Market Cap ⓘ | $1.27B | |
| Beta ⓘ | 1.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 2.49 | 1.65 |
| FCF Yield ⓘ | -11.61% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 0.79% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -32.20% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -16.62% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -24.15% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 89.58% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 3.66% | 9.26% |
| ROA (Latest) ⓘ | -7.09% | 4.91% |
| ROIC (5Y Median) ⓘ | -37.65% | 7.70% |
| ROA (5Y Median) ⓘ | -52.67% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -18.56 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -15.17 | 0.95 |
| Net Debt / Assets ⓘ | -37.66% | 13.69% |
| EBITDA / Interest ⓘ | 2.49 | 12.34 |
| Operating Margin (Latest) ⓘ | 392.46% | 13.20% |
| Operating Margin (5Y Median) ⓘ | -3726.70% | 11.80% |
| Debt to Equity (Latest) ⓘ | 6.97% | 40.56% |
| Profit Margin (Latest) ⓘ | N/A | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$148.04M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -18.51% | +68.89% |
| 12M Return (excl. last month) ⓘ | +12.85% | +30.21% |
| 6M Return ⓘ | -43.09% | -4.16% |
| Price vs. 200-Day MA ⓘ | -35.07% | -1.27% |
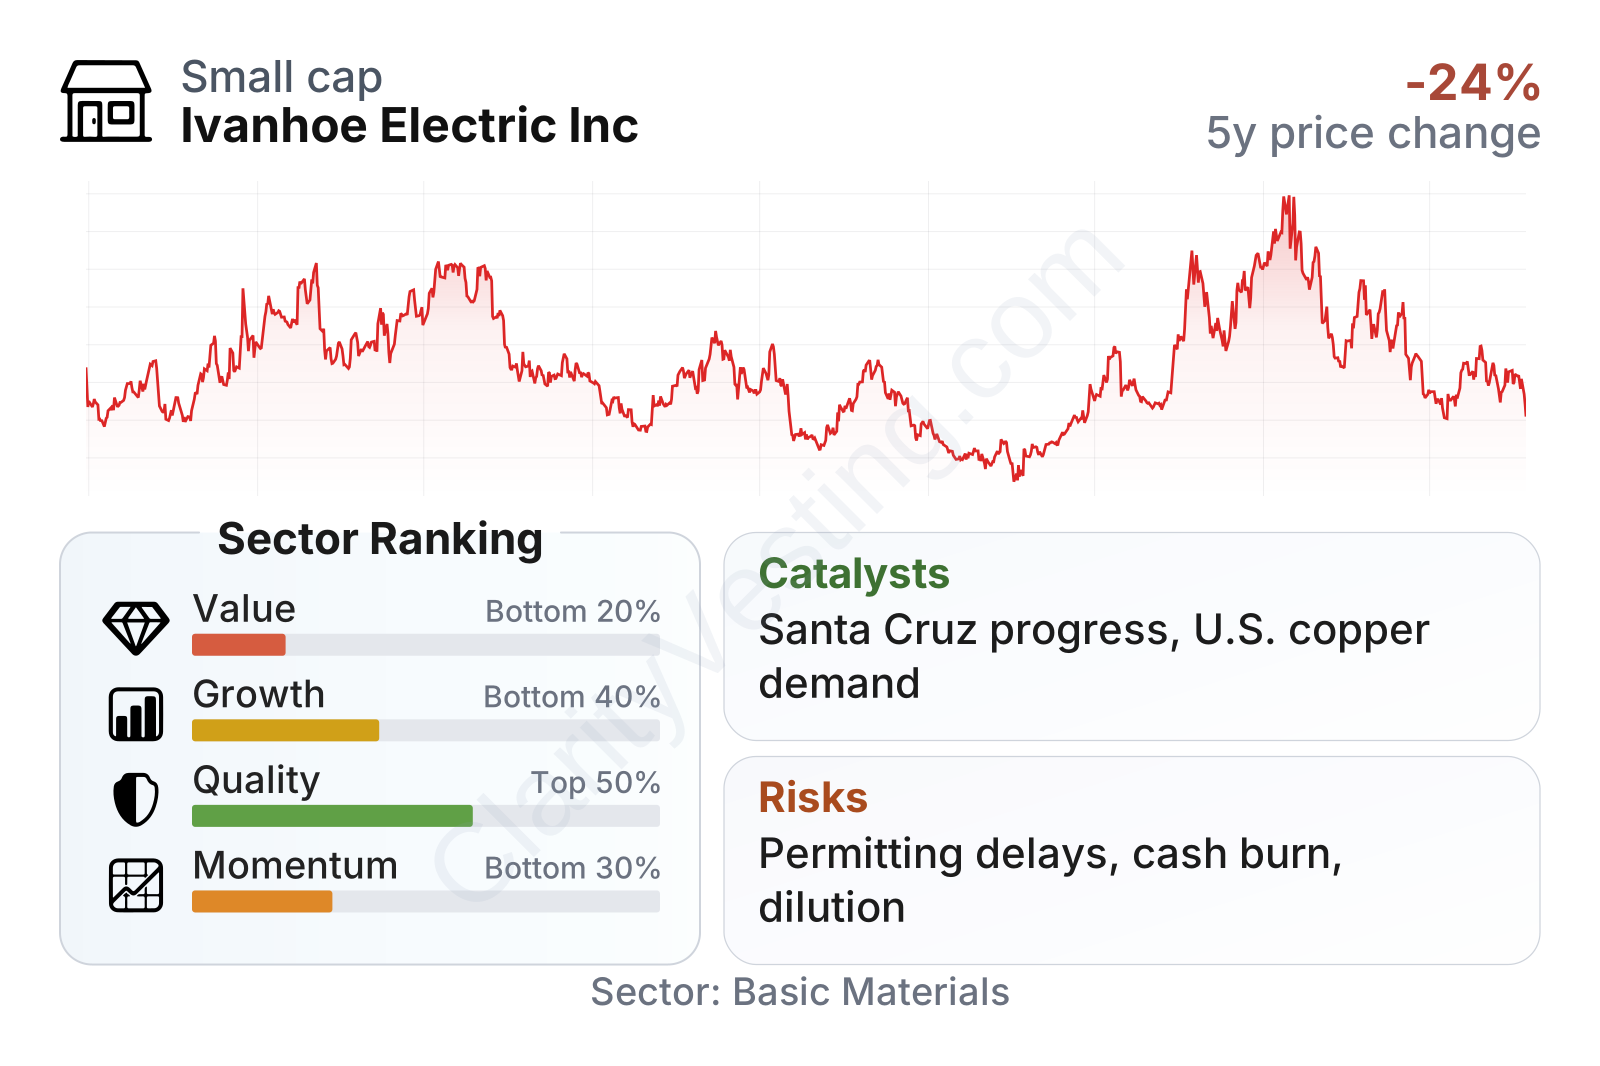
Ivanhoe Electric is a mid-sized company by mining-development standards, with a market value around the lower end of large-cap mining peers and well below the major diversified copper groups. The factor profile is mixed. Quality ranks around the middle of the sector, helped by a very low debt load and a cash-rich balance sheet relative to borrowings. By contrast, value and growth rank in the lower part of the sector because the company is still generating negative free cash flow, limited operating earnings, and uneven revenue. Momentum has also lagged the broader materials group, reflecting how dependent the share price remains on project milestones and market sentiment toward copper developers.
Growth
Ivanhoe Electric operates in a sector with a strong long-term backdrop. Copper is central to grid expansion, electrification, electric vehicles, renewable power systems, and data-center infrastructure. The United States also wants more domestic supply of critical minerals, which gives strategic value to projects located in Arizona and other mining-friendly jurisdictions. In that sense, the company is positioned in a growing part of the materials market even if its own revenue line is still unstable.
The company’s strategy broadly makes sense for future growth. It combines one potentially significant U.S. copper development project with an in-house exploration technology platform that could improve discovery efficiency. If Santa Cruz moves further toward construction and eventual production, Ivanhoe Electric would shift from a developer with limited revenue toward an operating copper company with a much larger financial base. That transition is the central growth catalyst.
Recent revenue trends, however, are not yet showing a smooth operating ramp. Growth has been highly volatile from quarter to quarter, with large swings between expansion and contraction. The latest year-over-year reading remains below the sector median, which is a reminder that current sales do not yet reflect the underlying size of the project portfolio.
Cash generation tells a more constructive but still incomplete story. Free cash outflow remains large, yet the trailing twelve-month burn improved materially from the deeper negative levels seen in earlier periods. That suggests spending discipline or timing benefits, but it does not change the main point: the company is still consuming cash while it develops assets.
A notable catalyst is the broader push for secure U.S. copper supply. Large future demand, permitting pressure on new mines, and the scarcity of advanced domestic projects could all increase the strategic relevance of Santa Cruz if technical studies, financing, and approvals continue to progress. The company has also highlighted progress around project advancement and exploration work in its public updates, which matters because this type of stock often responds more to milestone delivery than to near-term income statement figures.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


