Stock Analysis · IDEXX Laboratories Inc (IDXX)
Overview
IDEXX Laboratories is a healthcare diagnostics company best known for products and services used by veterinarians. Its core business is helping animal clinics test for disease, monitor health, and manage lab workflows. The company also has smaller operations in livestock and poultry testing, water quality testing, and diagnostic products used in human and life-science laboratories. In simple terms, IDEXX sells both the instruments that run tests and the recurring consumables, software, and reference-lab services that clinics use every day.
The business is centered on companion animals, especially dogs and cats. That matters because pet healthcare has been one of the more resilient areas of healthcare spending, supported by long-term trends such as rising pet ownership, greater willingness to pay for advanced care, and the ongoing shift of veterinary medicine toward more frequent testing and data-driven treatment.
Based on the company’s recent annual reporting structure, the main revenue sources are approximately:
- Companion Animal Group: about 91% of revenue. This includes in-clinic diagnostic instruments, rapid test kits, consumables, veterinary software, imaging, services, and reference laboratory testing for small-animal practices.
- Water: about 4% of revenue. This business provides testing solutions that help detect microbiological contamination in drinking water and other water samples.
- Livestock, Poultry and Dairy: about 3% of revenue. This segment includes diagnostic tests used in herd health, disease surveillance, and milk quality applications.
- Other: about 2% of revenue. This mainly covers products and services for human and life-science laboratories.
IDEXX’s revenue mix is attractive for long-term analysis because a large share comes from repeat purchases after instruments are installed. Once a veterinary clinic adopts an IDEXX system, it often continues buying test consumables, software subscriptions, service support, and lab testing, creating a sticky customer relationship. Over the last several years, revenue, gross profit, operating income, and net income have all moved higher, while research and development spending has also remained meaningful, showing that expansion has not come only from cost cutting.
The business model has become larger and more profitable over time. Revenue has climbed from a little above $3.2 billion in 2021 to more than $4.3 billion in 2025, while operating income and net income have also increased materially. That combination suggests IDEXX has been scaling efficiently rather than simply growing volume at lower profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $41.14B | |
| Beta ⓘ | 1.54 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 37.46 | 24.06 |
| P/B Ratio ⓘ | 25.90 | 3.08 |
| FCF Yield ⓘ | 3.04% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 3.49% | 0.63% |
| PEG ⓘ | 2.85 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.70% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 9.47% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -0.98% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 25.70% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | 2.67% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | 13.44% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 46.32% | 3.29% |
| ROA (Latest) ⓘ | 33.38% | 3.02% |
| ROIC (5Y Median) ⓘ | 46.22% | 4.75% |
| ROA (5Y Median) ⓘ | 28.14% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 0.61 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.66 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 0.56 | 0.99 |
| Net Debt / Assets ⓘ | 26.12% | 5.33% |
| EBITDA / Interest ⓘ | 41.38 | 9.63 |
| Operating Margin (Latest) ⓘ | 32.14% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 29.40% | 7.80% |
| Debt to Equity (Latest) ⓘ | 67.97% | 28.99% |
| Profit Margin (Latest) ⓘ | 25.03% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $1.25B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +20.14% | +37.48% |
| 12M Return (excl. last month) ⓘ | -15.75% | +20.85% |
| 6M Return ⓘ | -8.31% | +9.73% |
| Price vs. 200-Day MA ⓘ | -12.08% | +4.69% |
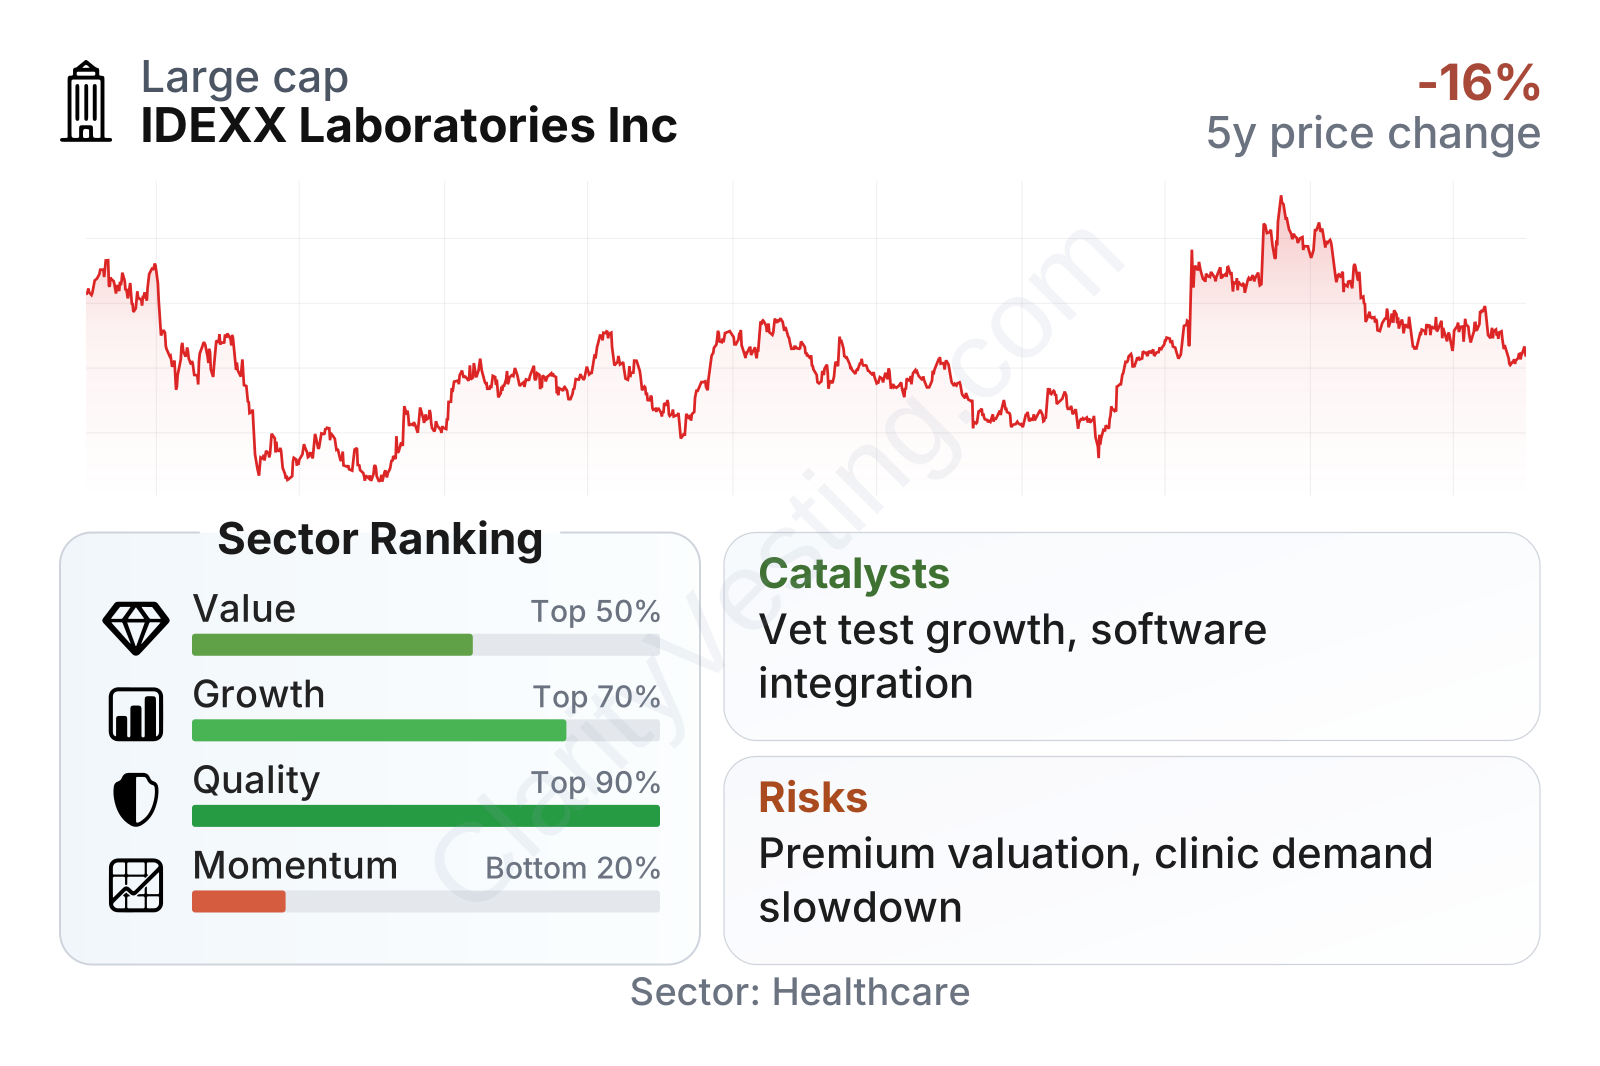
IDEXX stands out most on business quality. Profitability, returns on capital, and returns on assets are well above typical healthcare peers, which points to a strong operating model and disciplined execution. Growth metrics are also solid, with revenue growth slightly ahead of the sector median and free cash flow compounding at a much faster pace over five years. The weaker area is recent share-price momentum, which has lagged much of the sector even though the underlying business remains financially strong.
The stock’s history also shows that valuation can swing sharply. Shares fell heavily in 2022, recovered, then experienced another period of volatility. For long-term analysis, that matters because the market has repeatedly repriced the company based not only on business performance, but also on how much investors are willing to pay for a premium franchise.
Growth
IDEXX operates in a sector with favorable long-term drivers. Companion animal healthcare has benefited from a larger pet population, increasing medical spending per pet, and broader use of preventive diagnostics. Veterinary medicine is also becoming more sophisticated, with clinics using more bloodwork, imaging, software integration, and lab-based monitoring. These trends support demand for both IDEXX’s in-clinic testing systems and its reference laboratory network.
The company’s strategy is coherent: place instruments in veterinary practices, deepen software integration, expand menu offerings, and generate recurring revenue from consumables and services. This creates a flywheel effect. The more testing a clinic performs on an IDEXX platform, the harder it becomes to switch away, especially when diagnostic equipment, workflow software, and external lab services are connected.
Recent growth has not been perfectly smooth, but the broader trend remains constructive. Revenue growth slowed after the unusually strong post-pandemic period, then improved again, reaching low-double-digit levels at several points more recently. That pattern suggests the underlying market is still expanding, even if quarterly demand can move around with clinic traffic, pricing, and customer purchasing timing.
Cash generation has also strengthened meaningfully. Trailing free cash flow has risen from roughly $0.6 billion a few years ago to more than $1.0 billion more recently. For a business like IDEXX, this is important because it shows growth is translating into real cash that can support acquisitions, product development, debt management, and share repurchases.
A notable catalyst is continued diagnostic penetration within veterinary practices. Many clinics still have room to increase test utilization per visit, and IDEXX continues to expand its installed base, software capabilities, and test menu. The company has also emphasized innovation in point-of-care testing and workflow connectivity, which can make clinics more efficient and support premium pricing. In addition, water testing remains a smaller but useful niche with regulatory and public-health relevance, offering some diversification beyond animal health.
Recent company updates have also pointed to continued product launches and workflow improvements across veterinary diagnostics and software. Those developments matter because IDEXX’s growth is often driven less by one-time breakthroughs and more by steady increases in test volumes, menu expansion, and deeper customer integration.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


