Stock Analysis · Incitec Pivot Limited (ICPVF)
Overview
Incitec Pivot Limited is an Australian industrial company focused on explosives used in mining and quarrying, and on fertilizers and plant nutrition products used in agriculture. In simple terms, it sells products that help mines break rock efficiently and help farmers improve crop yields. The company has long operated across Australia, with additional exposure to international mining markets through its explosives activities.
Its business mix has changed materially in recent years. The largest earnings driver has been the explosives segment, especially products and services supplied to mining customers under the Dyno Nobel brand. The fertilizer activities remain important, but the company has been simplifying its portfolio and placing more emphasis on mining-related explosives, where customer relationships, logistics, and technical support can create stronger barriers to entry.
Based on recent company reporting and the group structure in place before the most recent portfolio changes, the main revenue sources can be summarized as follows:
- Explosives and blasting services: approximately 55% to 65% of group revenue. This includes ammonium nitrate, initiating systems, blasting technology, and on-site services for mining, quarrying, and construction customers.
- Fertilizers and agricultural inputs: approximately 35% to 45% of group revenue. This includes fertilizers, soil nutrition products, and related distribution to farmers, mainly in Australia.
That revenue split should be viewed as indicative rather than fixed because the company has been reshaping its asset base. The broad direction is clear: explosives are increasingly central to the investment case, while fertilizer exposure is becoming less dominant than it was historically.
The business also shows how cyclical industrial companies work. Revenue can be large, but profits can swing sharply because earnings depend on commodity markets, gas and ammonia input costs, contract pricing, plant utilization, and one-off asset charges. Over the last few years, sales stayed in the multibillion-dollar range, but profitability moved from very strong levels to losses and then partial recovery, illustrating that headline revenue alone does not tell the full story.
The flow of revenue and costs over time highlights a company with meaningful scale but uneven earnings conversion. Revenue has trended down from the unusually strong 2022 level, and operating profit has been far more volatile than sales. That pattern suggests margins, asset write-downs, and input-cost pressure have mattered more than simple volume growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $4.71B | |
| Beta ⓘ | 0.41 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 29.89 | 16.92 |
| P/B Ratio ⓘ | 1.20 | 1.66 |
| FCF Yield ⓘ | 4.83% | 5.83% |
| Dividend Yield ⓘ | 3.52% | 2.07% |
| EBIT / EV ⓘ | N/A | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 9.20% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | -12.54% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -8.64% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | -3.81% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -2.23% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 54.77% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 0.13% | 4.92% |
| ROIC (5Y Median) ⓘ | 4.71% | 7.91% |
| ROA (5Y Median) ⓘ | 1.60% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 2.06 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.52 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 1.12 | 0.93 |
| Net Debt / Assets ⓘ | 20.43% | 13.69% |
| EBITDA / Interest ⓘ | 5.05 | 12.38 |
| Operating Margin (Latest) ⓘ | 9.38% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 9.26% | 11.82% |
| Debt to Equity (Latest) ⓘ | 39.67% | 40.30% |
| Profit Margin (Latest) ⓘ | -1.04% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $227.43M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +83.87% | +73.47% |
| 12M Return (excl. last month) ⓘ | +47.89% | +27.59% |
| 6M Return ⓘ | +26.89% | -4.02% |
| Price vs. 200-Day MA ⓘ | +21.54% | -0.65% |
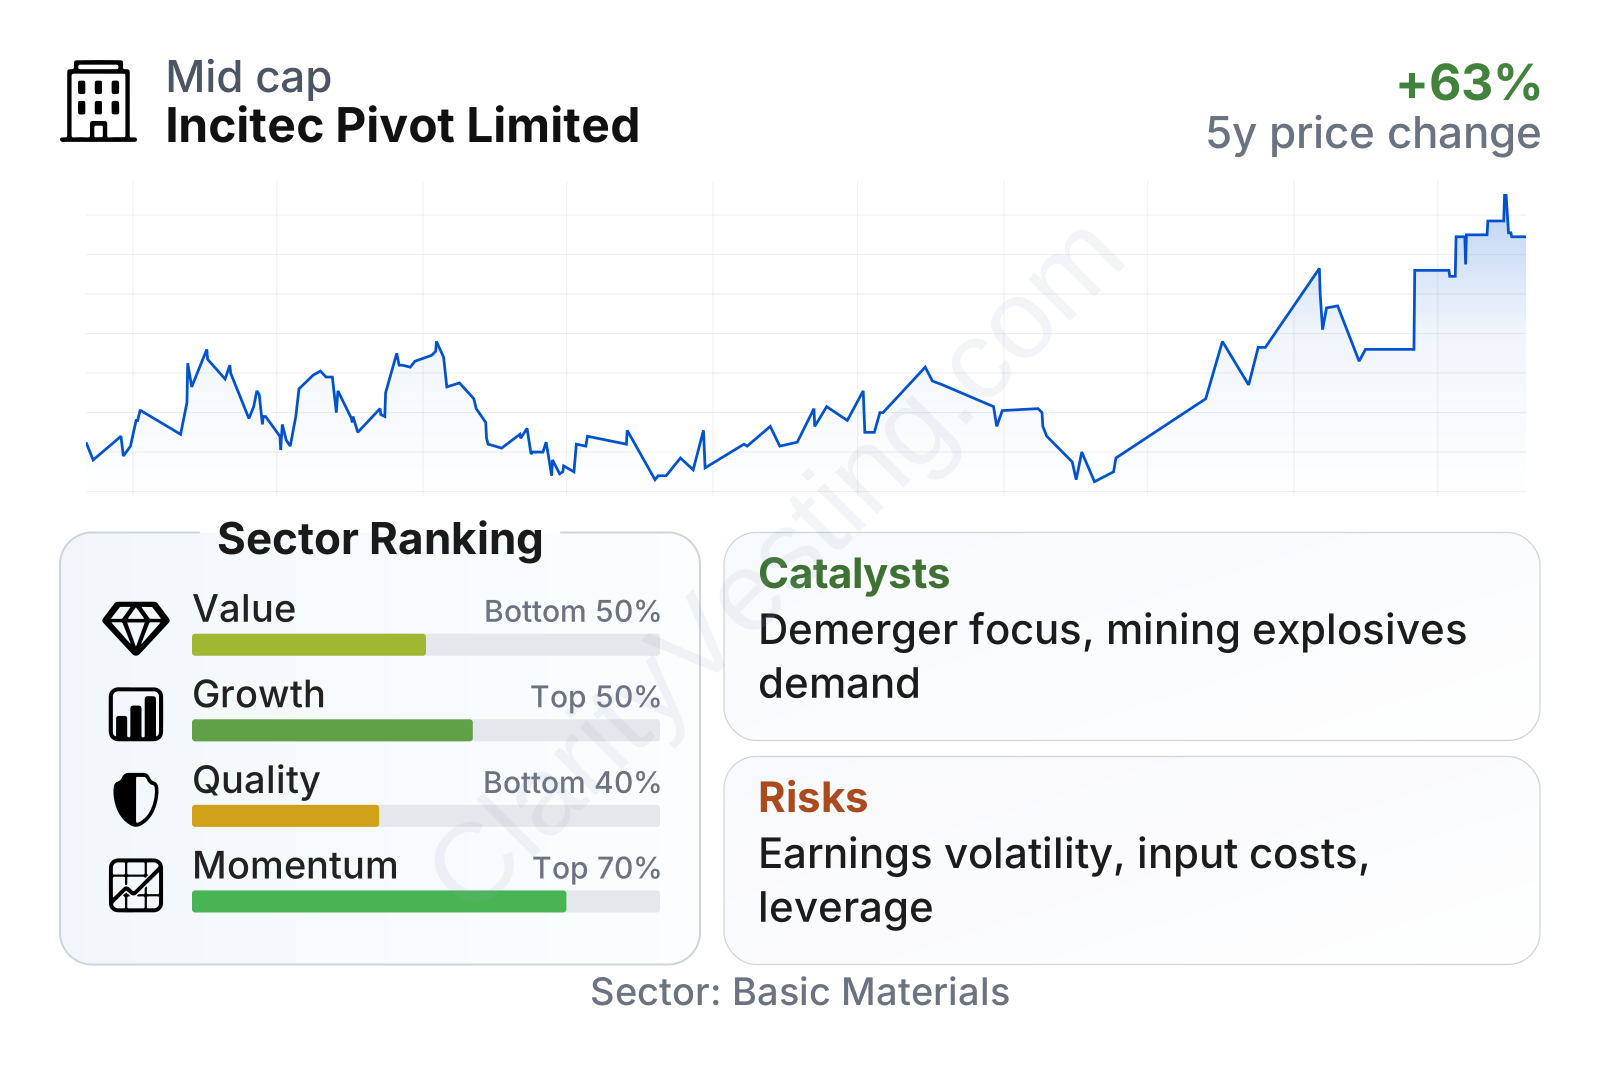
Incitec Pivot sits in the mid-cap range and has had a strong share-price run over the last year, clearly outperforming much of its sector in shorter-term momentum. At the same time, the valuation picture is mixed: the earnings multiple is above the sector median, while the price-to-book ratio is lower. That usually points to a market that is paying up for expected improvement, but still attaching some caution to the quality and durability of those earnings.
Income generation remains a relevant part of the profile. The trailing dividend yield is above the sector median, and free cash flow is positive, but cash generation is not so strong that it erases the company’s balance-sheet and profitability questions. Debt is not extreme by industrial standards, yet leverage and interest coverage are weaker than many peers in specialty chemicals and related materials businesses.
The quality indicators are the weakest part of the current picture. Profit margin is negative on a trailing basis, returns on assets are very low, and operating margins sit below the sector median. Growth indicators are more balanced: recent year-over-year revenue growth has been positive, but the longer five-year trend for revenue per share and book value per share is still unfavorable. In short, recent market performance has improved faster than the underlying quality metrics.
Growth
Incitec Pivot operates in sectors with durable long-term demand, but not in a smooth, high-growth way. Mining explosives benefit from structural demand for copper, gold, iron ore, and other minerals that support electrification, infrastructure, and industrial production. Fertilizers benefit from the long-term need to raise agricultural productivity. These are essential industries, even if yearly demand can fluctuate with crop prices, mining output, and commodity cycles.
The more convincing growth angle is in explosives rather than fertilizers. Mining customers typically require reliable supply, technical integration, safety performance, and site-specific blasting expertise. That can support repeat business and long-term contracts. If the company continues concentrating on higher-quality explosives assets and customer relationships, the strategy has a clearer logic than trying to be equally strong across unrelated cyclical segments.
A notable catalyst has been the company’s portfolio simplification. In 2024, Incitec Pivot completed the separation of its fertilizer business through the demerger of Dyno Nobel and changed its corporate identity toward fertilizer operations under the Incitec Pivot Fertilisers name, while Dyno Nobel became the explosives-focused listed entity. Because the U.S. over-the-counter symbol can lag corporate restructuring, readers should pay close attention to which listed entity the security currently represents and which assets remain inside it. That corporate change is highly important for interpreting historical financials versus the future business mix.
That restructuring can create opportunity if management executes well. A more focused company is often easier to analyze, can allocate capital more cleanly, and may earn a valuation closer to direct peers rather than to a mixed portfolio. Recent operating updates have also emphasized cost discipline, plant reliability, and sharper business focus, all of which matter in cyclical chemical businesses.
Another useful near-term support is that the stock’s recent momentum suggests the market has started to price in operational stabilization after a weak period. Stronger agricultural conditions, more normal plant performance, and fewer exceptional charges could all help reported earnings look materially better than the depressed levels seen recently. That does not remove cyclicality, but it does mean the baseline for comparison has become easier.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


