Stock Analysis · Immunitybio Inc (IBRX)
Overview
ImmunityBio is a biotechnology company focused on cancer immunotherapy. Its main goal is to help the immune system recognize and attack cancer more effectively. The company’s best-known commercial asset is ANKTIVA, an IL-15 agonist used with BCG for certain patients with non-muscle invasive bladder cancer. Beyond that first commercial product, ImmunityBio also has a broader pipeline in oncology and immune-based therapies, which means the company is still in a transition period from a research-focused biotech into a commercial-stage business.
At this stage, revenue is still concentrated. Based on recent annual results, the business appears to be driven mainly by product sales and closely related commercialization activity, with only a limited contribution from other sources.
- Product revenue: approximately 99% of 2025 revenue. This primarily reflects ANKTIVA-related sales following launch in bladder cancer.
- Other revenue: approximately 1% or less. This can include smaller items such as service-related or collaboration-related amounts when reported, but these are not currently the economic core of the business.
The bigger picture is straightforward: ImmunityBio is not a diversified pharmaceutical company with many established cash-generating medicines. It is currently a single-product commercial biotech with a large research base, meaningful operating expenses, and a valuation that depends heavily on whether ANKTIVA adoption expands and whether the pipeline produces additional approvals.
The financial flow shows a major change over the last two years: revenue moved from almost negligible levels to more than $100 million in 2025, while research and administrative spending remained very high. That is an important shift because the company is no longer pre-revenue, but it is still far from self-funding.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $9.16B | |
| Beta ⓘ | 0.03 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | N/A | 3.08 |
| FCF Yield ⓘ | -3.15% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | -9.47% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 93.90% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 167.66% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -39.47% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -3.12% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | -36.22% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.17% |
| ROA (Latest) ⓘ | -172.96% | 2.98% |
| ROIC (5Y Median) ⓘ | -173.51% | 4.56% |
| ROA (5Y Median) ⓘ | -100.22% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | 117.32% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | -548.47% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -35866.17% | 7.33% |
| Debt to Equity (Latest) ⓘ | -77.68% | 26.68% |
| Profit Margin (Latest) ⓘ | N/A | 3.34% |
| Free Cash Flow (Latest) ⓘ | -$288.51M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +481.12% | +51.61% |
| 12M Return (excl. last month) ⓘ | +247.94% | +19.90% |
| 6M Return ⓘ | +2.97% | +10.10% |
| Price vs. 200-Day MA ⓘ | +7.56% | +6.44% |
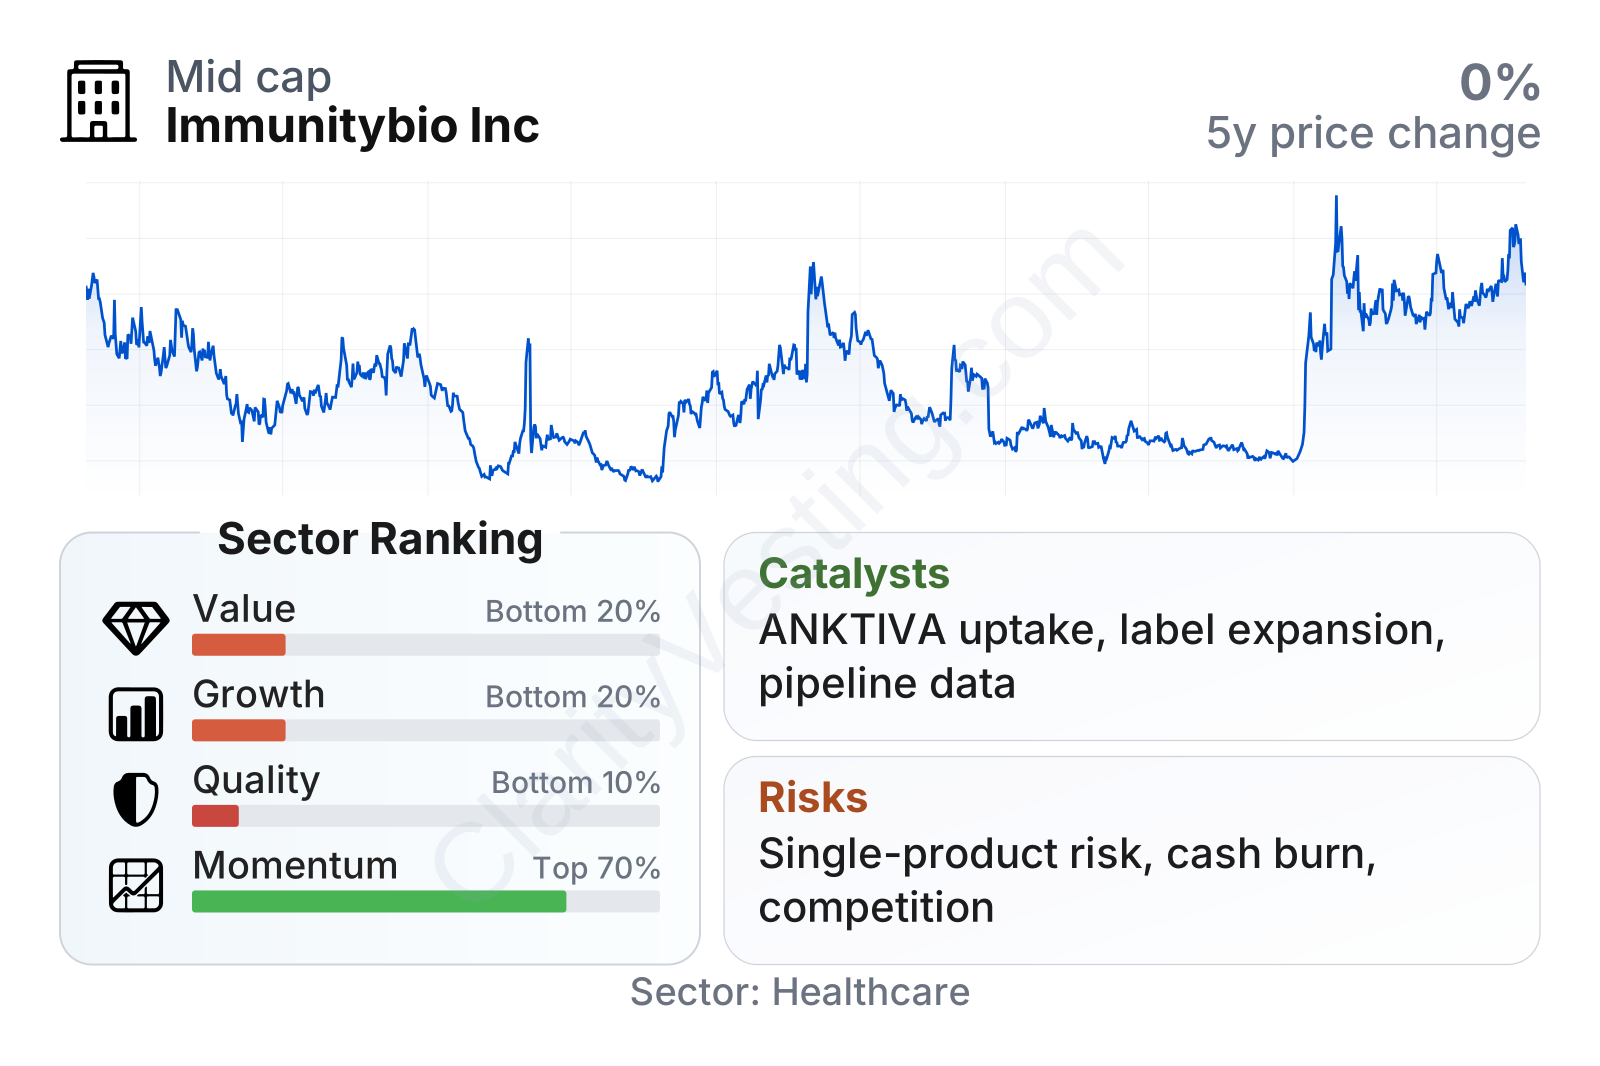
ImmunityBio now sits in the large-cap range for biotech, but its operating profile still looks like an early commercial company rather than a mature drug maker. Growth and market momentum have been strong, helped by the first product launch, yet quality and valuation measures remain weak versus the healthcare sector. In plain terms, the market is giving significant credit to future expansion, even though profitability, cash generation, and balance-sheet strength are still under pressure.
The stock’s historical path also shows how sentiment-driven this name can be. Shares fell sharply after earlier disappointments, then rebounded strongly as commercialization became real and expectations improved. That pattern matters for long-term readers because it highlights a company whose market value can shift quickly when clinical, regulatory, or launch milestones change.
Growth
ImmunityBio operates in a sector with long-term structural support. Cancer treatment remains one of the largest areas of drug development, and immunotherapy continues to attract heavy medical and commercial interest because it aims to improve outcomes without relying only on traditional chemotherapy. Bladder cancer is also an area where physicians still need more options, especially for patients who do not respond adequately to standard therapy.
The company’s strategy has a clear logic. It is building around an approved asset first, then trying to broaden its medical and commercial relevance through label expansion, combination use, and additional oncology programs. That is generally the most credible path for a biotech of this size: prove the first launch can work, then use that platform to support future growth.
Revenue growth has been exceptionally strong on a year-over-year basis, but that needs context. The company is growing from a very small base, so large percentage gains are easier to produce. Even so, the recent pattern is important because it confirms that commercialization has started to translate into real sales rather than remaining only a regulatory milestone.
Cash flow is improving, but it remains deeply negative. That means commercial traction is visible, yet the business has not reached the scale needed to cover its research, manufacturing, and operating costs. For a long-term view, the key question is whether revenue can keep climbing faster than the cash burn.
Recent company updates have kept attention on ANKTIVA rollout, manufacturing scale-up, and the potential to expand use across additional settings. Those are meaningful catalysts because a biotech with one approved product can change very quickly if prescribing activity builds, distribution broadens, and physicians gain confidence in real-world use. Any progress in additional trials or regulatory submissions would also matter because it could reduce reliance on a single indication.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


