Stock Analysis · IAMGold Corporation (IAG)
Overview
IAMGOLD Corporation is a gold mining company. It explores for gold deposits, develops new mines, and operates producing sites that sell gold into the global market. For a long-term reader, the business is relatively simple: IAMGOLD spends capital to build and maintain mines, extracts ore, processes it into gold, and earns revenue mainly from the ounces it sells and the gold price it receives.
The company’s producing asset base has recently centered on its operations in Canada and West Africa, with its newest and most important growth asset being the Côté Gold mine in Ontario. IAMGOLD also keeps a pipeline of exploration and development properties that may support future production, but those projects usually do not contribute much revenue until they enter commercial operation.
Revenue is overwhelmingly tied to gold, with only a small contribution from by-products and other mining-related items when applicable. Based on the company’s business mix in recent filings, the main sources of revenue can be summarized as follows:
- Gold sales: approximately 95% to 99% of revenue. This includes production from operating mines and the company’s share of output from major assets such as Côté Gold.
- Silver and other by-products: approximately 1% to 5% of revenue. These amounts are usually linked to metals recovered alongside gold at certain operations.
- Other items: generally minimal. This can include occasional non-core activity, but it is not a meaningful part of the investment case.
Recent financial direction shows a sharp step-up in scale. Over the last few years, the business moved from sub-$1.0 billion annual revenue to about $1.6 billion in 2024 and roughly $2.9 billion in 2025, while profitability also improved materially. That suggests IAMGOLD is no longer just a mature producer with limited change; it is in the middle of a portfolio transformation led by new production capacity.
The financial flow over the last several years points to a major earnings reset. Revenue expanded strongly from 2024 onward, while profit moved from losses in 2021 and 2022 to sizable positive income in 2024 and 2025. That kind of change usually reflects a mix of new mine contribution, operating leverage, and stronger realized gold prices.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $10.43B | |
| Beta ⓘ | 2.35 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 9.23 | 16.90 |
| P/B Ratio ⓘ | 2.28 | 1.65 |
| FCF Yield ⓘ | 15.15% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | 14.21% | 6.30% |
| PEG ⓘ | 13.52 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 47.50% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 28.37% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 141.52% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 10.89% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 43.97% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 28.17% | 9.26% |
| ROA (Latest) ⓘ | 20.43% | 4.91% |
| ROIC (5Y Median) ⓘ | 2.34% | 7.70% |
| ROA (5Y Median) ⓘ | 2.10% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.02 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.53 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.02 | 0.95 |
| Net Debt / Assets ⓘ | 0.65% | 13.69% |
| EBITDA / Interest ⓘ | 36.70 | 12.34 |
| Operating Margin (Latest) ⓘ | 46.44% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 9.49% | 11.80% |
| Debt to Equity (Latest) ⓘ | 12.27% | 40.56% |
| Profit Margin (Latest) ⓘ | 31.40% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.58B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +638.10% | +68.89% |
| 12M Return (excl. last month) ⓘ | +77.33% | +30.21% |
| 6M Return ⓘ | -17.31% | -4.16% |
| Price vs. 200-Day MA ⓘ | -7.04% | -1.27% |
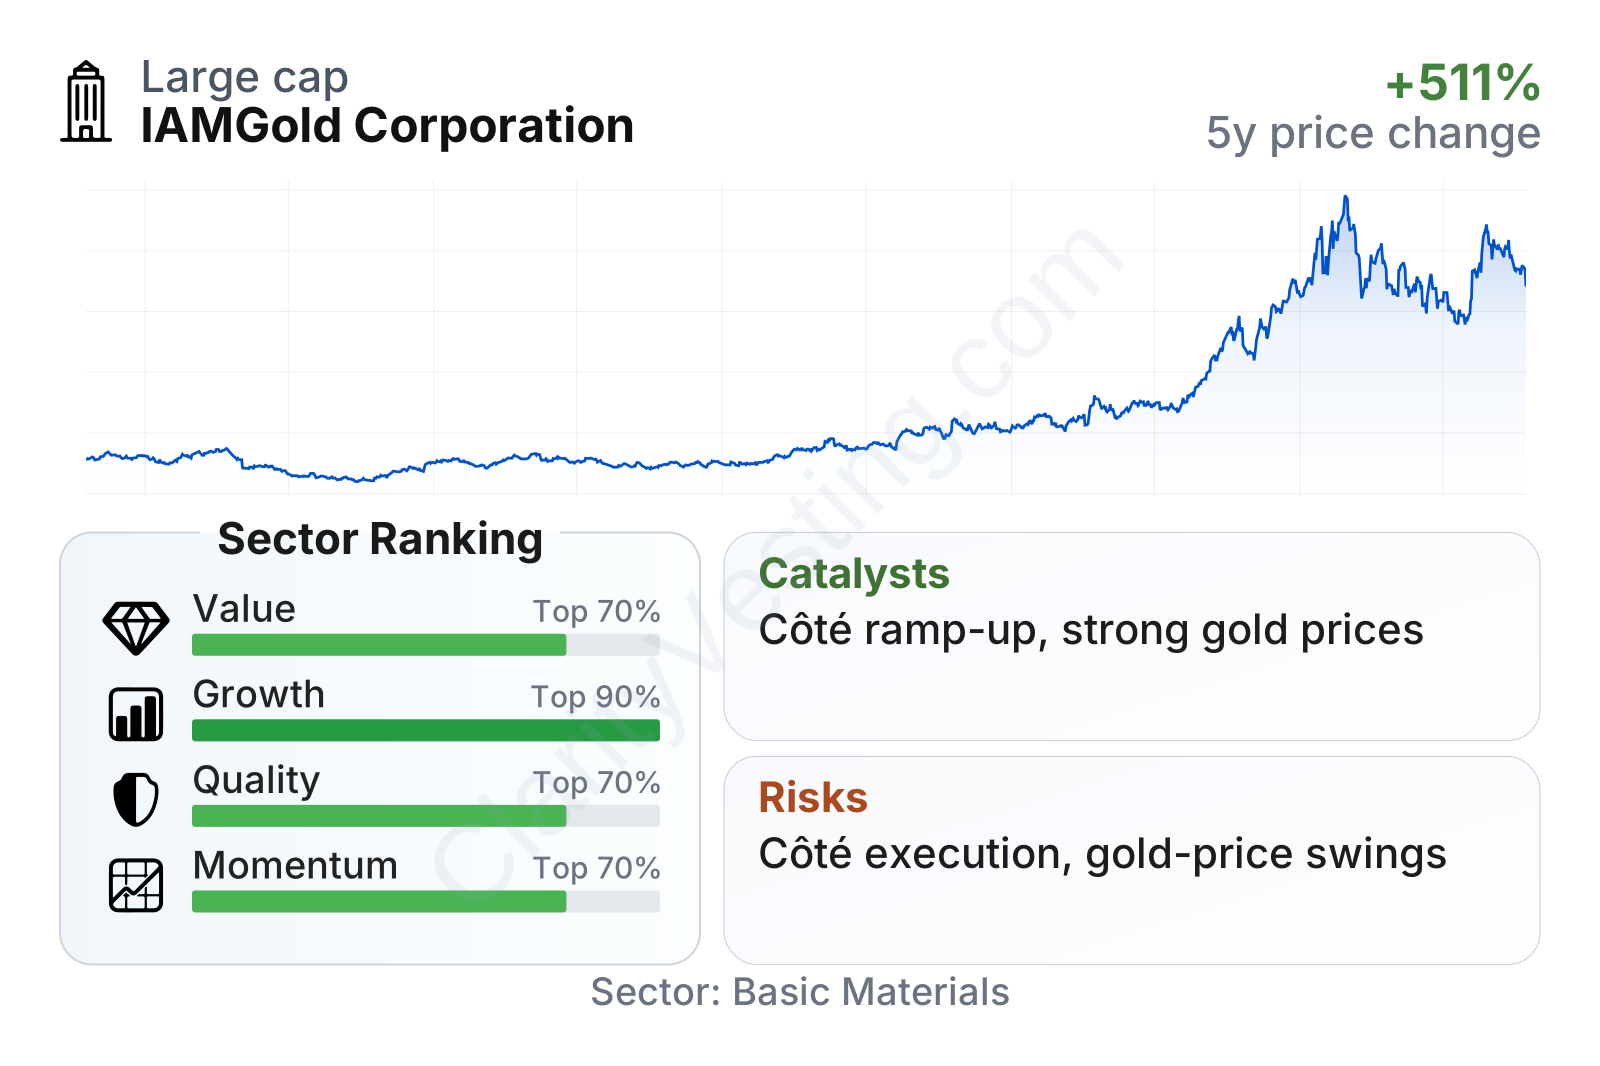
IAMGOLD is now a large gold producer by market value, but it still carries higher share-price volatility than the average mining stock, with a beta above 2. The stock’s long-term price performance has been very strong since late 2022, which matches the company’s operational turnaround and the market’s focus on Côté Gold. On the factor breakdown, growth stands out the most, while value and quality also look favorable versus much of the sector. The combination of a low earnings multiple, high free cash flow yield, and very strong recent profitability suggests the market is recognizing improvement, but not valuing it as richly as some other mining names.
Growth
Gold mining is not a high-growth industry in the same way as software or semiconductors, but it can still be attractive when new supply is hard to bring online and gold prices remain firm. The sector benefits from gold’s role as a store of value, central bank demand, jewelry demand, and interest from investors during periods of inflation, geopolitical stress, or pressure on real interest rates. In that context, companies that can add production without overloading the balance sheet usually get the most attention.
IAMGOLD’s strategy makes sense on that basis. The company has spent years repositioning itself around higher-quality assets, and the key milestone has been the ramp-up of Côté Gold. This mine is important because it gives IAMGOLD exposure to a large, modern Canadian operation with long-life potential. A successful ramp-up can raise total production, improve cost absorption, and diversify the company away from heavier dependence on older operations.
Revenue growth has been exceptionally strong in the last two years, clearly above the sector median. That acceleration supports the idea that IAMGOLD has moved into a new production phase rather than merely benefiting from short-term gold-price fluctuations. Strong multi-year growth in revenue per share and earnings also points to real business expansion, not only financial engineering.
Free cash flow is another important change. After several periods of negative cash generation during the heavy investment phase, IAMGOLD has shifted into strongly positive territory. That matters for long-term analysis because mines are capital-intensive: positive free cash flow can help fund development, reduce debt, strengthen liquidity, and lower the need for shareholder dilution.
A major catalyst is continued execution at Côté Gold. If the operation keeps ramping toward design expectations, IAMGOLD could maintain elevated production and cash generation. Another opportunity is a supportive gold price backdrop. Because fixed costs are meaningful in mining, a stronger realized gold price can expand margins disproportionately once production is already in place. Recent company updates have also emphasized operating progress and production guidance, reinforcing the view that the company’s recent jump in earnings power is tied to a real asset transition.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


