Stock Analysis · Howden Joinery Group Plc (HWDJF)
Overview
Howden Joinery Group Plc is a U.K.-based supplier of kitchens, joinery products, and hardware sold mainly to trade professionals such as builders, carpenters, and kitchen installers. Its model is slightly unusual for the sector: it manufactures many of its own kitchen cabinets, keeps products in stock, and sells through a dense depot network rather than relying mainly on large retail showrooms. That matters because trade customers usually value speed, product availability, and reliable local service more than a highly curated in-store experience.
The business is concentrated in the United Kingdom, with a much smaller but developing presence in continental Europe. In practical terms, Howden earns most of its money when homes are renovated, kitchens are replaced, and tradespeople need cabinets, doors, flooring, worktops, and fittings quickly. The company also generates recurring demand from repair, refresh, and small-scale improvement work, which can be steadier than demand for brand-new housing construction.
Based on company reporting, revenue is primarily split across product groups rather than many separate business lines. Approximate revenue sources are:
- Kitchens and kitchen products: about 60% to 65% of sales. This includes rigid kitchen cabinets, fronts, worktops, sinks, taps, and related accessories.
- Joinery products: about 20% to 25% of sales. This typically includes internal and external doors, flooring, and other fitted joinery items.
- Hardware and appliances: about 10% to 15% of sales. This includes handles, fixings, appliances, and complementary installation items.
- Geography: the U.K. accounts for well above 90% of group revenue, while France, Belgium, and the Republic of Ireland remain relatively small.
One useful point for long-term analysis is that Howden is not just a distributor. Its blend of manufacturing, sourcing, logistics, and local depots gives it more control over service levels and margins than a pure reseller. The flow of revenue into profit also shows a business that has kept gross profit resilient even when final earnings have moved around with operating costs and taxes.
Over the past five years, sales moved from just above £2.0 billion to about £2.4 billion, while gross profit stayed strong. Operating profit and net income have softened from the 2022 peak, but the overall picture still points to a business with solid pricing power and a relatively efficient operating model.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Furnishings, Fixtures & Appliances | |
| Market Cap ⓘ | $5.50B | |
| Beta ⓘ | 1.28 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.58 | 16.89 |
| P/B Ratio ⓘ | 4.86 | 1.61 |
| FCF Yield ⓘ | 5.35% | 8.99% |
| Dividend Yield ⓘ | 2.89% | 2.73% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | 1.53 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.30% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 5.80% | 8.91% |
| EPS Growth (5Y CAGR) ⓘ | -32.13% | -17.41% |
| BVPS Growth (5Y CAGR) ⓘ | 6.84% | 5.62% |
| Margin Growth (5Y Trend) ⓘ | -4.27% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | -0.66% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | -1.36% | 9.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.38% |
| ROA (Latest) ⓘ | N/A | 5.49% |
| ROIC (5Y Median) ⓘ | 28.90% | 10.75% |
| ROA (5Y Median) ⓘ | 12.43% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.69 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.97 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | 0.47 | 1.50 |
| Net Debt / Assets ⓘ | 15.92% | 21.57% |
| EBITDA / Interest ⓘ | 22.95 | 9.13 |
| Operating Margin (Latest) ⓘ | 14.03% | 9.10% |
| Operating Margin (5Y Median) ⓘ | 15.02% | 9.56% |
| Debt to Equity (Latest) ⓘ | 62.35% | 75.99% |
| Profit Margin (Latest) ⓘ | 10.86% | 5.31% |
| Free Cash Flow (Latest) ⓘ | $294.33M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +37.04% | +15.94% |
| 12M Return (excl. last month) ⓘ | -11.59% | -2.82% |
| 6M Return ⓘ | -7.95% | -1.58% |
| Price vs. 200-Day MA ⓘ | -5.59% | -3.31% |
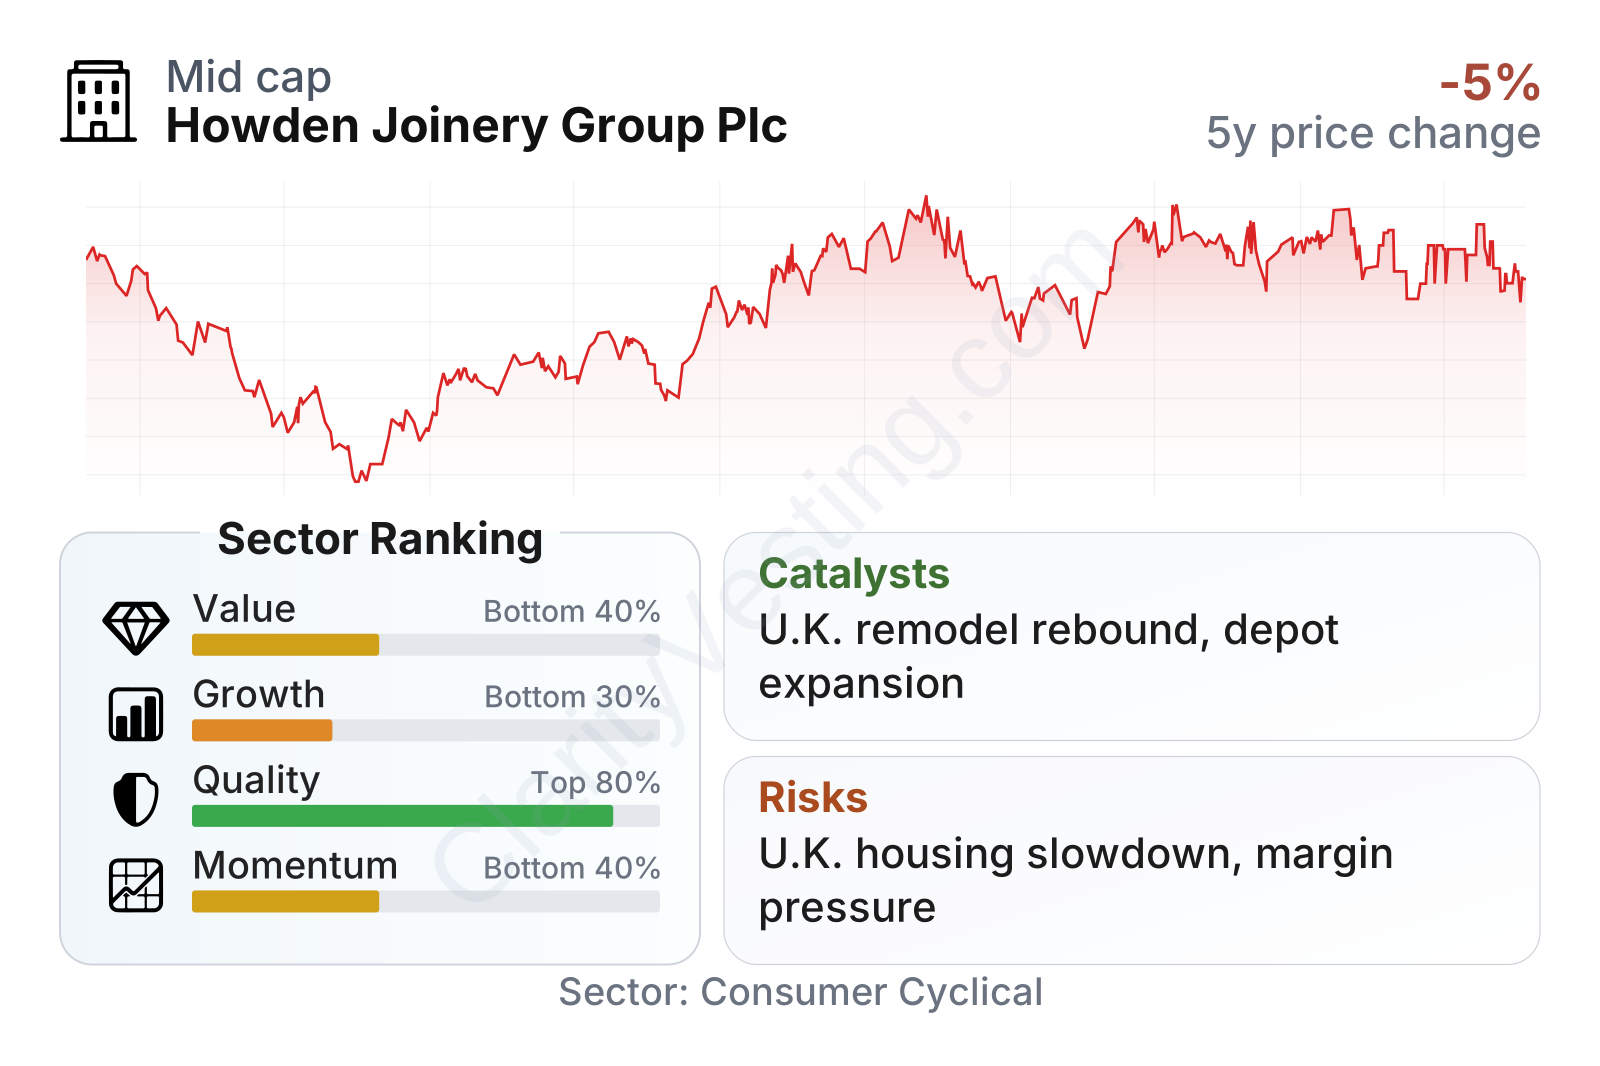
Howden sits in the mid-to-large range within its niche, with a market value of roughly $5.4 billion and a share price that has been volatile but resilient over the last several years. The factor mix is a bit unusual: quality is clearly strong, while growth and recent momentum look weaker. Profitability metrics remain comfortably above the sector median, leverage is moderate, and cash generation is still meaningful. By contrast, growth metrics and recent share-price trend place it in the lower part of the sector range, which suggests the market is recognizing business quality but remains cautious about near-term expansion.
Growth
Howden operates in a market tied to housing turnover, repair and remodeling activity, and household confidence. That means it is exposed to cyclical swings, but it also serves a category with long-term relevance: kitchens and home improvement remain essential spending areas over time, especially in aging housing stock like the U.K.’s. This is not a fast-growth technology market, but it can still support steady expansion for a well-run operator with strong local share.
The company’s strategy is coherent for that environment. Its depot network keeps it close to trade customers, its in-stock model reduces project delays, and its product development supports repeat business. Expansion is also coming from new depot openings, deeper penetration of existing catchment areas, and gradual development outside the U.K. In addition, kitchen demand is often driven by renovation and replacement rather than just new-home construction, which provides some diversification within the housing cycle.
Recent growth has been modest rather than rapid. Year-over-year revenue growth is positive, but it trails the sector median, and five-year revenue-per-share growth has also been slower than many peers. Even so, revenue has held up reasonably well through a tougher consumer backdrop, which suggests that the company’s trade-focused model is helping it defend volumes better than a more discretionary retail concept might. A meaningful catalyst over the next few years would be a recovery in U.K. housing transactions and broader remodeling demand, because operational leverage could lift profit faster than sales once volumes improve.
Another important growth lever is category depth. Howden can sell more to the same trade account by bundling cabinets, surfaces, doors, flooring, and hardware into one job. That can raise wallet share without needing dramatic market expansion. Recent company updates have also emphasized continued investment in depots, digital tools, and product ranges, all of which support share gains even in a subdued market.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


