Stock Analysis · HighPeak Energy Inc (HPK)
Overview
HighPeak Energy is an independent oil and gas producer focused on the Midland Basin, a core part of the Permian Basin in West Texas. Its business is straightforward: it acquires acreage, drills wells, produces crude oil, natural gas, and natural gas liquids, and sells those commodities into the market. The company’s asset base is concentrated, which can help operational focus, but it also means results depend heavily on one region and on commodity prices.
Revenue comes primarily from the sale of produced hydrocarbons. Based on the company’s recent annual reporting mix, crude oil is the main driver by a wide margin, with natural gas liquids and natural gas making up the rest.
- Crude oil: approximately 70% to 80% of revenue. This is the company’s largest earnings engine and usually carries the strongest pricing impact.
- Natural gas liquids: approximately 10% to 20% of revenue. This includes products such as propane, butane, and related liquids separated during production.
- Natural gas: approximately 5% to 15% of revenue. This is the smallest of the three streams and tends to be the most exposed to weak U.S. gas pricing.
Over the last several years, HighPeak expanded rapidly, lifting annual revenue from about $220 million in 2021 to more than $1.1 billion in 2023 before easing to roughly $1.07 billion in 2024 and about $863 million in 2025. The broad pattern is clear: production growth built scale quickly, but weaker margins and heavier financing costs reduced how much of that revenue turned into profit.
Another important point for long-term readers is that HighPeak is not a diversified integrated energy company. It is a smaller exploration and production company, so its fortunes are closely tied to well performance, drilling economics, oil prices, and access to capital.
The multi-year flow of revenue to profit shows a business that achieved meaningful scale, but with profitability compressed by rising costs and especially higher interest expense. Operating expenses remained relatively controlled, yet the drop in gross profit and net income after 2023 highlights how sensitive the model is to commodity pricing and financing structure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas E&P | |
| Market Cap ⓘ | $1.28B | |
| Beta ⓘ | 0.36 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 15.44 |
| P/B Ratio ⓘ | 0.81 | 1.73 |
| FCF Yield ⓘ | -1.15% | 8.20% |
| Dividend Yield ⓘ | 0.82% | 3.59% |
| EBIT / EV ⓘ | -1.04% | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 25.80% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 31.25% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 21.53% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | -13.97% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | -47.96% | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | 8.35% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -0.46% | 11.40% |
| ROA (Latest) ⓘ | -2.78% | 6.06% |
| ROIC (5Y Median) ⓘ | 10.21% | 10.30% |
| ROA (5Y Median) ⓘ | 8.05% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.29 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 2.50 | 1.08 |
| Net Debt / Assets ⓘ | 32.86% | 17.29% |
| EBITDA / Interest ⓘ | 2.92 | 9.64 |
| Operating Margin (Latest) ⓘ | -2.51% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 34.05% | 20.39% |
| Debt to Equity (Latest) ⓘ | 76.68% | 54.76% |
| Profit Margin (Latest) ⓘ | -10.28% | 8.82% |
| Free Cash Flow (Latest) ⓘ | -$14.73M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -41.28% | +67.38% |
| 12M Return (excl. last month) ⓘ | +18.24% | +49.19% |
| 6M Return ⓘ | +68.25% | +7.07% |
| Price vs. 200-Day MA ⓘ | +47.99% | +9.56% |
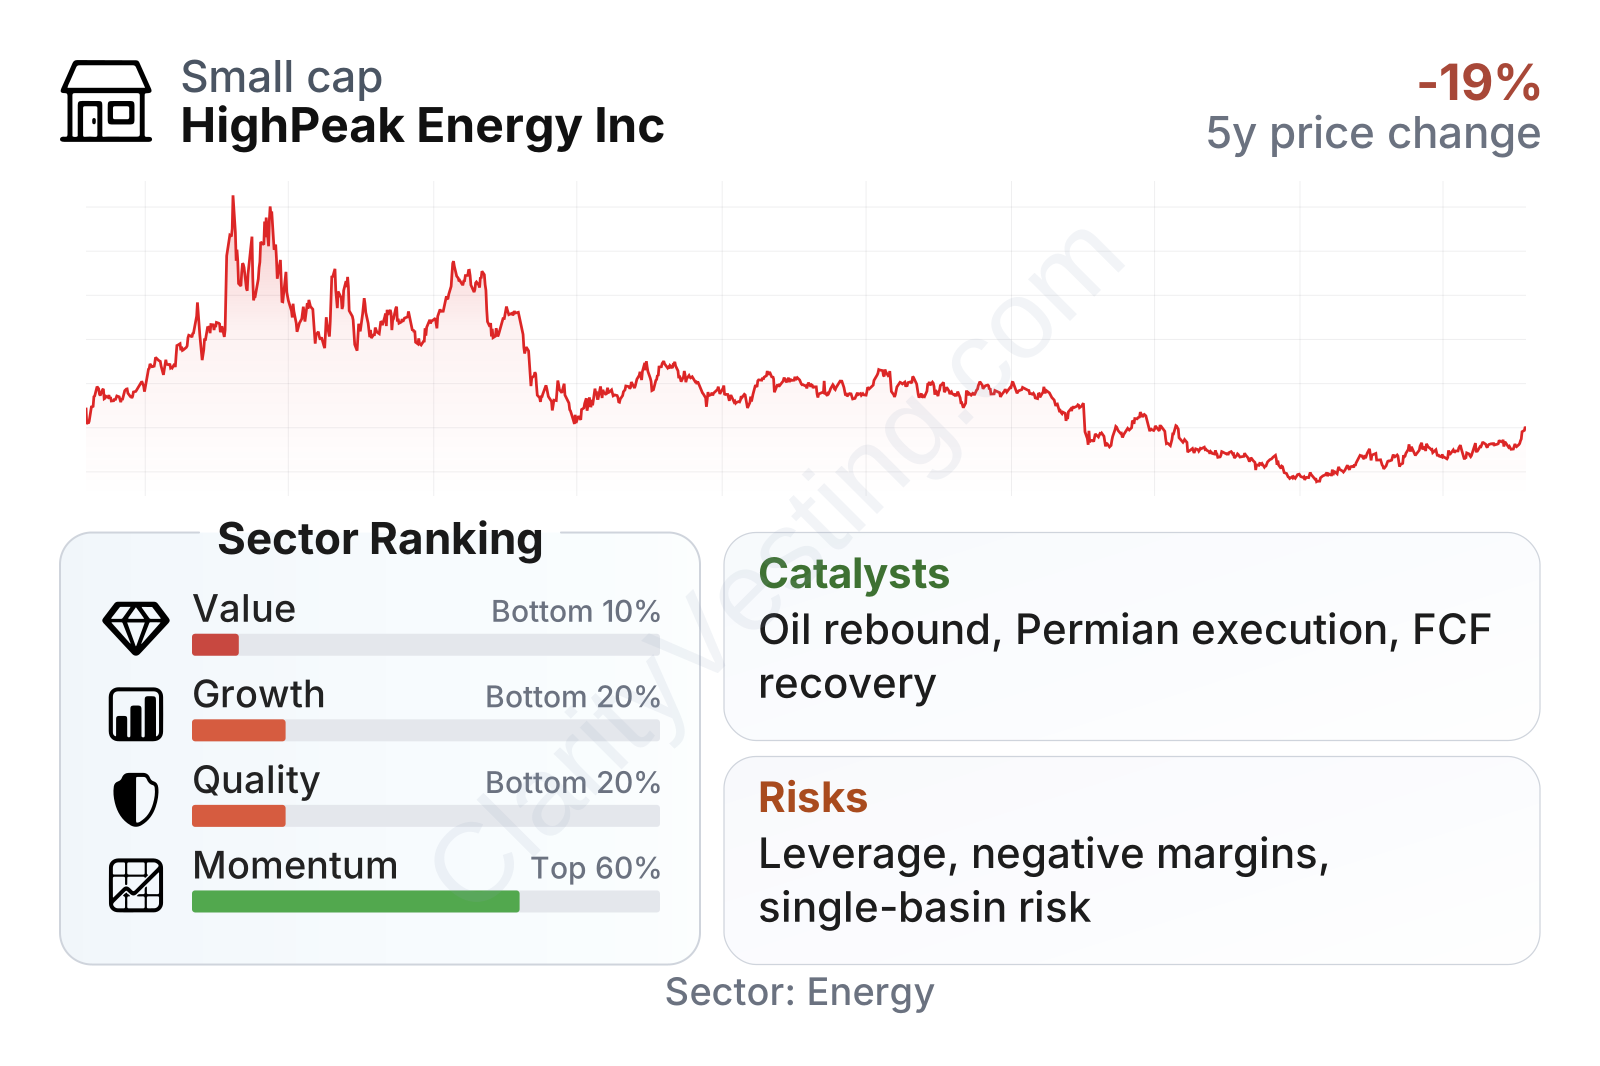
HighPeak is a small-cap energy producer with an unusually low stock beta, meaning its share price has moved less aggressively than many energy names in recent periods. Even so, the longer stock history has been volatile, with a sharp drop from 2023 highs followed by a partial recovery in 2026.
The latest overall factor picture is mixed. Growth over a five-year period has been strong in revenue per share and book value per share, which reflects how quickly the company built production and asset value. However, current quality and value indicators rank weakly against the sector because profitability has slipped into negative territory on a trailing basis, free cash flow is slightly negative again, and leverage metrics are heavier than typical peers. Momentum has improved recently, helped by a stronger six-month price trend, but the underlying operating picture remains more fragile than the share rebound alone would suggest.
Growth
HighPeak operates in the Permian Basin, one of the most important oil-producing regions in North America. For the industry as a whole, this remains an attractive area because of its deep inventory, established infrastructure, and generally better economics than many other U.S. shale regions. That gives the company exposure to a sector with continuing long-term relevance, even as energy markets cycle through stronger and weaker periods.
The company’s strategy is built around developing a concentrated acreage position in Howard County and surrounding areas, improving production efficiency, and using scale to support cash generation. In principle, that strategy makes sense for an upstream company: if drilling results remain solid and oil prices cooperate, a focused Permian operator can grow production and spread fixed costs across a larger base.
Recent revenue growth has been uneven. After extremely rapid expansion in earlier years, year-over-year growth turned negative through much of 2025 before improving again in mid-2026. That pattern suggests HighPeak is no longer in the easy early-stage growth phase. Future expansion looks more dependent on execution, well productivity, and price support than on simple scale-up.
Free cash flow has also been inconsistent. The company moved from deeply negative cash generation during heavier investment periods to a brief positive stretch, then back near break-even to negative. For long-term analysis, this matters because sustained value creation in oil and gas usually depends less on headline production growth and more on whether that growth can fund itself while still covering debt service and shareholder returns.
A practical catalyst is any combination of stronger oil prices, steadier production growth, and lower financing pressure. If those three line up, HighPeak’s earnings profile could improve quickly because the company already has meaningful scale. Another supportive element is that its acreage is in a basin where larger operators and capital markets tend to keep paying attention, which can preserve strategic flexibility.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


