Stock Analysis · Helmerich and Payne Inc (HP)
Overview
Helmerich & Payne is a U.S.-based drilling contractor serving oil and natural gas producers. In simple terms, the company owns and operates drilling rigs that energy companies use to drill wells, mainly on land. It is best known for its high-specification “FlexRig” fleet in the United States, and it also offers related digital tools, automation, and performance services that help customers drill faster, more consistently, and with better well data.
The business is still centered on contract drilling, so its results depend heavily on customer drilling activity, daily rig pricing, and how many rigs are working at a given time. Over time, Helmerich & Payne has tried to make its offering more than just renting rigs by adding software, directional drilling capabilities, and automation features that can strengthen customer relationships and improve rig economics.
Based on recent company reporting, revenue is concentrated in a few major areas:
- North America Solutions: approximately 80% to 90% of total revenue in recent periods. This is the core U.S. land drilling business and includes most of the company’s active rig fleet, performance-driven contracts, and related drilling services.
- International Solutions: approximately 5% to 10% of revenue. This includes land drilling operations outside the United States, with activity levels depending on local contracts and country exposure.
- Offshore Gulf of Mexico: approximately 1% to 5% of revenue. This is a much smaller segment tied to offshore platform rigs.
- Other solutions and ancillary services: a small remaining share. This includes technologies, software-related offerings, and other support activities that complement the drilling business.
The broader financial picture shows a business that expanded revenue strongly through the upcycle, but with profitability narrowing sharply more recently as costs rose, utilization shifted, and acquisition-related pressure increased.
Over the last several years, revenue grew materially from the 2022 base and stayed elevated through 2025, but earnings conversion weakened. Gross profit remained meaningful, yet operating income and net income compressed sharply by 2025 as interest expense and operating costs moved higher.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Drilling | |
| Market Cap ⓘ | $3.91B | |
| Beta ⓘ | 0.69 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 15.44 |
| P/B Ratio ⓘ | 1.56 | 1.73 |
| FCF Yield ⓘ | 8.07% | 8.20% |
| Dividend Yield ⓘ | 2.58% | 3.59% |
| EBIT / EV ⓘ | 1.11% | 7.46% |
| PEG ⓘ | 5.78 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -0.60% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 35.17% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | -0.58% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | 34.21% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | 21.05% | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | 0.06% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 0.06% | 11.40% |
| ROA (Latest) ⓘ | -2.12% | 6.06% |
| ROIC (5Y Median) ⓘ | 0.55% | 10.30% |
| ROA (5Y Median) ⓘ | 0.15% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | 26.74 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 4.72 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 2.09 | 1.08 |
| Net Debt / Assets ⓘ | 26.37% | 17.29% |
| EBITDA / Interest ⓘ | 7.65 | 9.64 |
| Operating Margin (Latest) ⓘ | 1.55% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 2.45% | 20.39% |
| Debt to Equity (Latest) ⓘ | 72.34% | 54.76% |
| Profit Margin (Latest) ⓘ | -3.43% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $315.29M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +0.43% | +67.38% |
| 12M Return (excl. last month) ⓘ | +108.11% | +49.19% |
| 6M Return ⓘ | +14.49% | +7.07% |
| Price vs. 200-Day MA ⓘ | +5.75% | +9.56% |
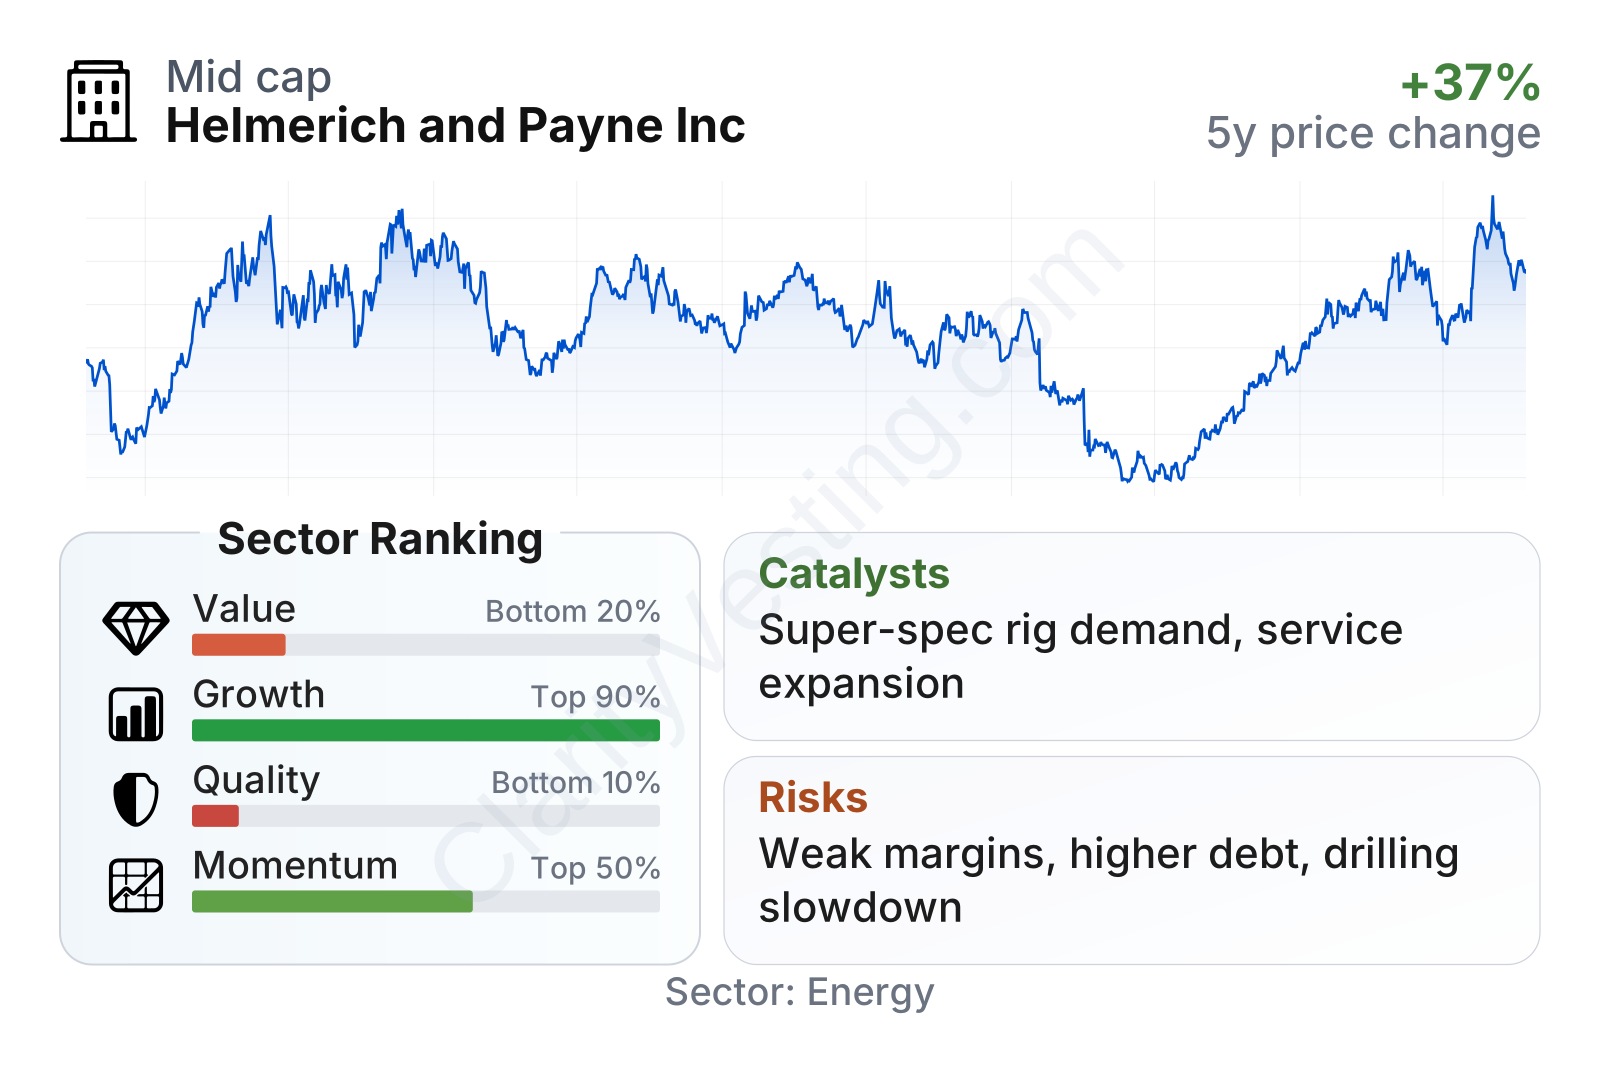
Helmerich & Payne is a mid-sized energy services company with a relatively low share-price sensitivity to the broader market. The overall scorecard is mixed: long-term growth measures look strong compared with much of the sector, but current profitability and capital efficiency are weak. Value metrics do not stand out positively because operating earnings have fallen so much, even though free cash flow generation remains respectable and the price-to-book ratio is not stretched.
The stock history also shows how cyclical this business is. Shares moved sharply with the drilling cycle, fell hard during the 2025 downturn, and then recovered significantly into 2026. That kind of pattern is common in oilfield services and matters for anyone assessing long-term durability rather than only short-term momentum.
Growth
Helmerich & Payne operates in a sector with long-term importance but uneven growth. Oil and gas drilling is not a steady compounding industry like software or consumer staples. Instead, it moves in cycles tied to oil and natural gas prices, producer budgets, and the need to replace declining wells. That means the sector can produce strong growth for periods of time, followed by abrupt slowdowns.
For Helmerich & Payne, the strategic logic is clear. The company is focused on premium land rigs, automation, drilling optimization, and bundled services that can help customers lower well costs and improve reliability. In a cautious spending environment, that value proposition can matter because exploration and production companies are looking for fewer mistakes, faster drilling times, and better returns on each well rather than simply adding more rigs.
Revenue growth has been highly cyclical. The company posted extremely strong year-over-year gains through much of 2022 and early 2023, then growth cooled, and the latest readings have turned slightly negative. That slowdown does not erase the bigger five-year expansion, but it shows that the business is now dealing with a less favorable activity backdrop than during the post-2021 recovery.
A notable strategic catalyst is Helmerich & Payne’s push to broaden its offering beyond core rig rental. Recent company disclosures highlight interest in automation, digital drilling tools, and integrated service capabilities. The company also expanded its position through acquisitions, including assets that add directional drilling and other well-construction capabilities. If that broader platform gains traction, it could increase revenue per customer and make the company less dependent on a pure day-rate model.
Cash generation remains an important bright spot. Free cash flow has improved substantially from the negative level seen in 2022 and stayed positive despite operating pressure. That matters because it gives the company more flexibility to support capital spending, dividends, debt service, and integration needs even when accounting earnings are under strain.
Recent company updates also suggest a meaningful opportunity tied to super-spec rigs and technology-enabled drilling performance in the U.S. land market. Even if total industry rig counts are not rising strongly, a shift toward more capable rigs can still favor companies with a premium fleet and established customer relationships. Helmerich & Payne remains one of the most recognized names in that part of the market.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


