Stock Analysis · Houlihan Lokey Inc (HLI)
Overview
Houlihan Lokey is an investment bank focused on advice rather than balance-sheet-heavy lending or trading. The firm helps companies, financial sponsors, creditors, boards, and other institutions navigate major corporate events such as mergers, acquisitions, restructurings, liability management transactions, capital solutions, and valuation assignments. That makes it a specialized professional-services business inside financial services, with results driven mainly by deal activity and advisory fees.
The company reports revenue across three main business lines. Based on its recent annual mix, the largest to smallest sources are approximately:
- Corporate Finance: about 55% to 60% — advisory on mergers and acquisitions, capital solutions, private capital raising, and other strategic transactions.
- Financial Restructuring: about 20% to 25% — advice to debtors, creditors, and other stakeholders on restructurings, liability management, distressed situations, and bankruptcies.
- Financial and Valuation Advisory: about 20% — valuation opinions, portfolio valuation, dispute consulting, transaction opinions, and related financial advisory work.
One important feature of Houlihan Lokey’s model is that it is less dependent on financing commitments than many larger Wall Street banks. In practice, that means revenue comes primarily from fees earned on advice. It also means the company usually carries less balance-sheet risk than universal banks, while remaining exposed to the ups and downs of corporate dealmaking.
Over the last several years, the business has shown a cyclical revenue pattern rather than a straight line. Revenue and profit fell after the exceptionally strong 2021-2022 period, then recovered meaningfully through fiscal 2025 and into fiscal 2026. The latest operating picture suggests the firm is still highly profitable, but like most advisory firms, it remains sensitive to the timing of closings and the broader transaction environment.
The broad trend points to a recovery from the post-boom slowdown: revenue has moved back above prior trough levels, operating income has improved, and net income has rebounded. At the same time, compensation and operating expenses remain substantial, which is typical for an advisory firm where talent is the core asset.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Capital Markets | |
| Market Cap ⓘ | $8.83B | |
| Beta ⓘ | 0.97 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 21.41 | 12.60 |
| P/B Ratio ⓘ | 4.05 | 1.23 |
| FCF Yield ⓘ | 5.49% | 10.16% |
| Dividend Yield ⓘ | 1.96% | 2.96% |
| EBIT / EV ⓘ | 6.35% | 7.77% |
| PEG ⓘ | 6.54 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -15.50% | 9.50% |
| RPS Growth (5Y CAGR) ⓘ | 3.56% | 12.10% |
| EPS Growth (5Y CAGR) ⓘ | -29.27% | -9.45% |
| BVPS Growth (5Y CAGR) ⓘ | 11.43% | 5.01% |
| Margin Growth (5Y Trend) ⓘ | -5.52% | -4.07% |
| FCF Growth (5Y CAGR) ⓘ | -1.62% | 4.96% |
| DPS Growth (5Y CAGR) ⓘ | 10.89% | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.93% | 9.60% |
| ROE (Latest) ⓘ | 18.50% | 13.84% |
| ROA (Latest) ⓘ | 10.82% | 1.53% |
| ROIC (5Y Median) ⓘ | 19.25% | 7.86% |
| ROE (5Y Median) ⓘ | 19.32% | 12.20% |
| ROA (5Y Median) ⓘ | 10.47% | 1.29% |
| Net Debt / EBIT (Latest) ⓘ | -0.45 | 0.91 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.96 | 0.74 |
| Net Debt / EBITDA (Latest) ⓘ | -0.42 | 0.97 |
| Operating Margin (Latest) ⓘ | 22.19% | 22.12% |
| Operating Margin (5Y Median) ⓘ | 21.48% | 24.39% |
| Debt to Equity (Latest) ⓘ | 21.86% | 60.37% |
| Profit Margin (Latest) ⓘ | 16.08% | 26.62% |
| Free Cash Flow (Latest) ⓘ | $484.63M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +27.58% | +89.23% |
| 12M Return (excl. last month) ⓘ | -31.93% | +17.35% |
| 6M Return ⓘ | -8.03% | +10.00% |
| Price vs. 200-Day MA ⓘ | -13.50% | +3.73% |
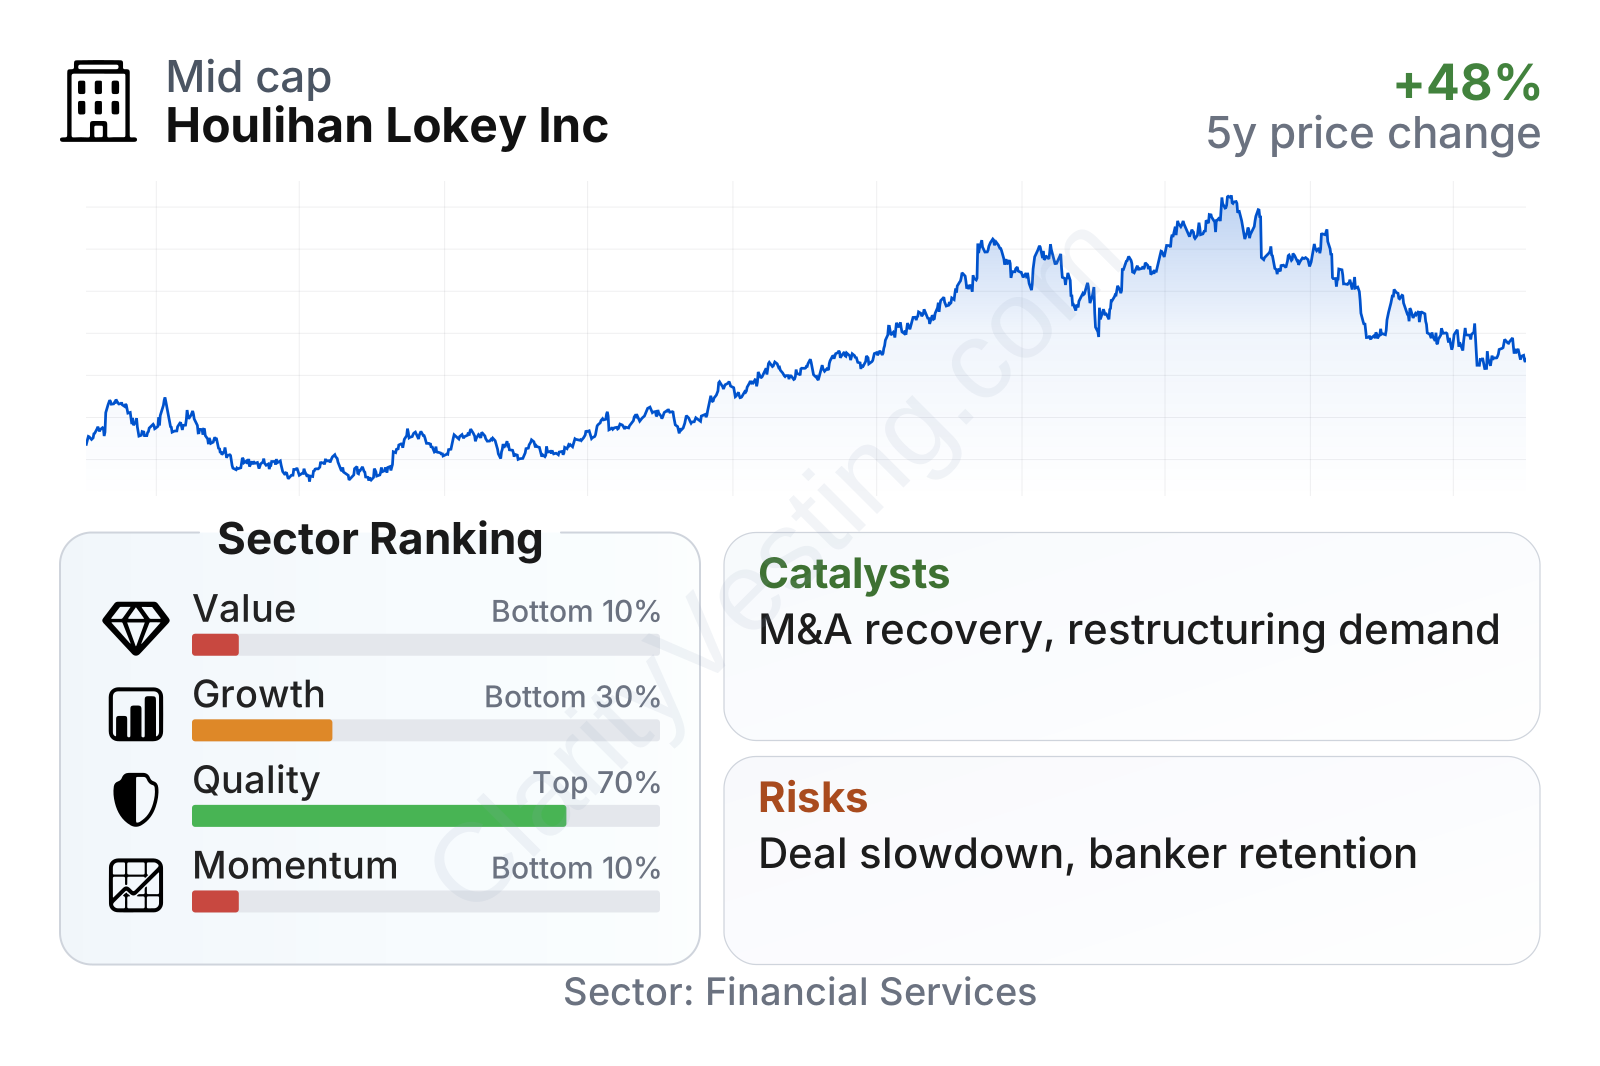
Houlihan Lokey stands out more on business quality than on cheapness or recent market performance. Profitability and capital efficiency remain well above sector medians, and the balance sheet is notably conservative with net cash rather than heavy leverage. On the other hand, valuation multiples sit clearly above sector norms, while recent growth and share-price momentum have been weaker than much of the broader financial sector.
The stock’s history over the last five years reflects that mix. After a strong run into 2025, the share price pulled back sharply in 2026. Even with that decline, the company is still valued as a premium franchise rather than an average capital-markets name, which suggests the market continues to give weight to its profitability, niche position, and cleaner balance sheet.
Growth
Houlihan Lokey operates in parts of finance that are cyclical, but the underlying need for advisory work is durable. Companies regularly need help with acquisitions, divestitures, fairness opinions, valuations, restructurings, and capital structure decisions. In that sense, the company is tied to long-term corporate complexity rather than to a single short-lived trend. Its growth potential comes less from explosive industry expansion and more from gaining market share, adding senior bankers, expanding internationally, and broadening capabilities in sectors and products where clients need specialized advice.
The strategy appears coherent for long-term expansion. Houlihan Lokey has spent years building scale in middle-market and large-cap advisory while keeping a relatively asset-light model. This can be attractive because advisory firms do not need large amounts of capital to grow; instead, growth depends on recruiting productive teams, preserving reputation, and converting relationships into mandates. The company has also benefited from having countercyclical elements in its business mix: restructuring activity can strengthen when M&A slows, helping reduce reliance on any single market backdrop.
Earnings per share show why the business should be viewed through a cycle. Profits dropped after the unusually strong fiscal 2022 period, then recovered materially by fiscal 2025 and fiscal 2026. That pattern suggests the franchise itself remained intact even when the market environment softened. It also shows that earnings can rebound quickly when transaction conditions improve.
Book value per share has moved steadily upward over the last five years, which supports the idea that the company has been compounding capital even through uneven markets. That is a useful sign for an advisory firm because it indicates value creation was not limited to a single boom year. Dividend growth has also been solid over that period, adding another signal of financial resilience.
A meaningful catalyst is the possibility of a broader recovery in mergers and acquisitions after a period of slower volumes caused by higher rates and macro uncertainty. If financing conditions stabilize and board confidence improves, corporate finance revenue could benefit. At the same time, if credit stress remains elevated, Houlihan Lokey’s restructuring franchise could stay active. That dual exposure is one of the more appealing elements of the business model.
Recent company updates have also pointed to continued investment in headcount and strategic hires. For an advisory firm, senior banker recruitment matters because future revenue often follows talent. In addition, Houlihan Lokey has consistently emphasized its position in restructuring and valuations, areas where client demand can remain strong even when standard M&A is uneven.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


